- Turkiye: Weak rebar demand pressured imported scrap buying
- Japan: Kanto tender rose, with cargo awarded to Bangladesh
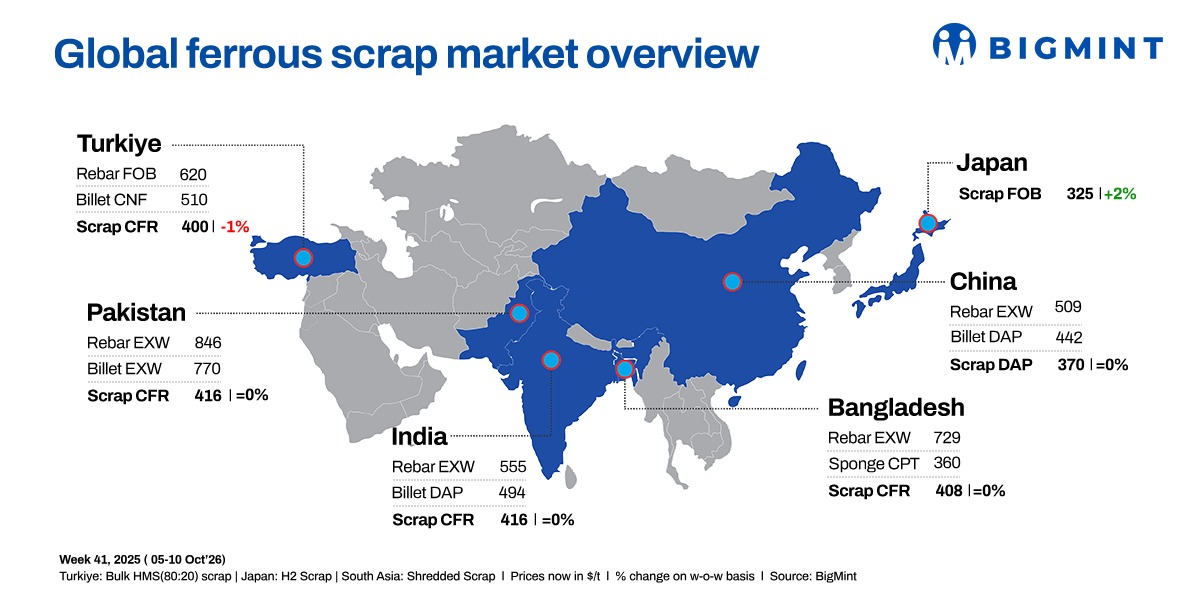
Global ferrous scrap markets remained subdued in the week ended 10 October, with cautious buying and weak steel demand pressuring prices across Turkiye, India and Pakistan. Bangladesh faced high freight costs and firm offers, while Japanese scrap prices rose on stronger tender results and mill hikes. UAE domestic prices remained stable amid uncertainty over scrap export restrictions.
Turkiye: Deep-sea imported scrap prices fell shortly fell by $4/t on October 9, amid muted trading, weak rebar demand and a persistent buyer-seller price gap. Early in the week, US-origin HMS 80:20 was assessed at $400-405/t CFR, while Baltic offers stood at $402-403/t and EU-origin material at $395-399/t. Sellers remained firm due to elevated freight costs and stronger US domestic prices, while mills resisted high offers.
UK-origin scrap deals in Türkiye eased to $390-391/t CFR, while US HMS 80:20 offers stood at $404-407/t CFR. Tradable values clustered at $404-406/t, as rebar prices fell nearly $20/t over two weeks, weakening mills’ buying interest.
India: Imported scrap market remained subdued to firm through the week, as weak finished-steel demand and cautious buying kept negotiations under pressure. UK HMS 80:20 with 3% impurities was bid at $340/t against offers of $360-365/t, while quality HMS was indicated at $390/t CFR India or above, though these levels remained largely unachieved.
Trading included UK-origin turnings at $340/t CNF Nhava Sheva, Senegal- and Mozambique-origin HMS 80:20 at $380/t CFR Mundra, and US-origin HMS 80:20 at $390/t CFR Mundra. UK shredded offers stood at $410-415/t, while US shredded was offered at $415-420/t. Buyers favoured prompt-arrival cargoes from Southeast Asia and nearby origins. Australia-origin HMS in Chennai was heard at $360-365/t and shredded at $375-380/t. A weaker rupee and subdued steel demand continued to limit import activity.
In the last seven days, 2,500-3,500 t of scrap was booked, including 1,500-2,000 t of HMS 80:20 at $372-380/t CFR, alongside 1,000-1,500 t of turning boring at $340/t.
Freight: India-bound scrap freight rates fell by $50 to $1,400-1450/container on the Melbourne-Chennai route, while London Gateway-Chennai and JNPT rates rose by $25 to $1,650-1700 and $1,550-1600/container, respectively, amid container shortages and port space constraints.
Pakistan: Imported scrap market remained subdued, with UK shredded deals easing from $422-427/t to $412-415/t CFR Qasim. Brazilian sheared HMS was booked at $392/t, while buyers remained price-sensitive and sought shredded scrap near $420/t.
Pakistan’s scrap buying remained constrained by high freight costs, vessel delays, port congestion and mill activity of around 35%. Middle East fabrication scrap traded at $423/t and structural scrap at $473-477/t CFR Qasim. Domestic scrap stood at PKR 135,000-138,000/t and billet at PKR 215,000-218,000/t, with imported scrap prices potentially nearing a bottom.
Bangladesh: Imported scrap market remained subdued through the week amid firm offers, limited buying and high freight costs. UK shredded offers eased to $400-405/t, while deals included Panama-origin HMS 80:20 at $376/t and Hong Kong-origin PNS at $415/t CFR Chattogram. Australia/New Zealand HMS-PNS mix offers stood at $390-400/t against bids of $380-385/t. Singapore PNS reached $430/t, A Chattogram-based steel mill secured 20,000 t in the October Kanto tender through a Japanese trading company.
Japan: FOB Tokyo Bay scrap prices rose JPY 900/t to JPY 51,400/t ($325/t). Tokyo Steel raised H2 scrap purchase prices by JPY 500-1,000/t effective 9 October, marking its second hike in October ahead of the Kanto tender.
Japan’s October Kanto scrap tender rose JPY 3,964/t to JPY 52,077/t FAS ($329/t), ending four consecutive monthly declines, with the cargo awarded to Bangladesh. Yen depreciation limited the dollar gain to $16/t, while higher ocean freight pressured FOB prices.
UAE: Domestic ferrous scrap prices remained broadly stable in the week ended 9 October, supported by good availability and consistent quality. Buying remained selective as market participants awaited clarity on a possible resumption of scrap exports. The BigMint assessment for processed HMS 80:20 fell AED 1/t w-o-w to AED 1,032/t ($279/t), excluding 5% VAT. Domestic HMS 80:20 stood at AED 940-960/t, processed HMS at AED 1,020-1,030/t, shredded scrap at AED 1,130-1,140/t, processed PNS at AED 1,050-1,070/t and LMS at AED 840-860/t.
Leave a Reply