- Surplus scrap arrivals and weak steel demand pressure mills
- Patra prices decline INR 1,100/t w-o-w
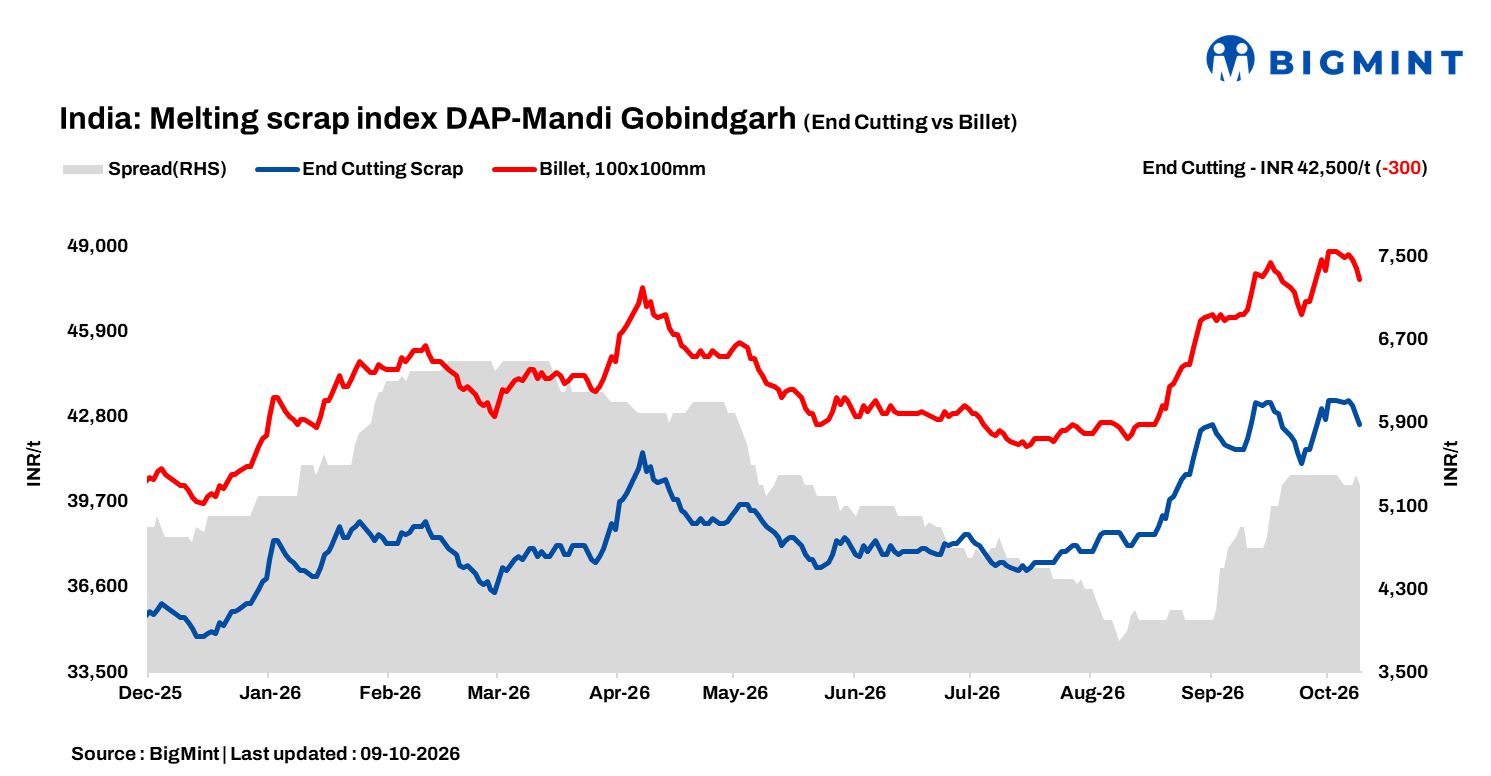
BigMint’s domestic end-cutting scrap index, tracking the Mandi Gobindgarh market, eased by INR 300/tonne (t) d-o-d to INR 42,500/t DAP on 9 October 2026. The scrap index remained largely stable week-on-week, while other scrap grades also witnessed stable price trends.
Mandi, a key secondary steel hub, witnessed subdued demand in the finished steel segment during the current week. Patra prices declined significantly by around INR 1,100/t, while the rebar segment also saw muted buying activity with a minor price correction.
Semi-finished steel prices remained largely stable week-on-week, although buying activity remained slow. Most mills continued to face pressure, primarily due to weak finished steel demand and limited downstream offtake.
Scrap arrivals in Mandi remained surplus during the week, adding to the pressure on local mills. Several mills either reduced or stopped scrap purchases amid weak demand, while power-cut issues further affected production and market activity.
Overall, the steel market trend remained unsupportive for secondary steel makers during the current week. The price momentum seen in September failed to carry into the first week of October, with demand recovery yet to gain pace.
Alternative raw material prices
Sponge iron (CDRI) prices in Mandi Gobindgarh declined by INR 300/t day-on-day to INR 34,500/t DAP. The downward movement reflected subdued demand and cautious procurement by mills, supported by surplus scrap arrivals and lower scrap quotations in the market. On a weekly basis, sponge iron prices declined by INR 300/t.
Steel-grade pig iron prices in Ludhiana edged lower by INR 100/t day-on-day to INR 44,000/t DAP. The marginal decline indicates relatively balanced conditions in the segment, with prices holding near recent levels despite softer buying sentiment. As per weekly change pig iron prices fell by INR 320/t in the region.

Steel market
Semi-finished steel prices in Mandi Gobindgarh decreased by INR 300/t d-o-d to INR 47,900/t DAP. Prices across other major steel-producing centres decreased by around INR 100-500/t, indicating broad-based weakness across the secondary steel market. As per weekly basis ingot prices remained unchanged in Mandi.
In finished steel, Fe500 rebar prices in Mandi Gobindgarh remained stable d-o-d at INR 53,500/t ex-works, while HR strip (patra) prices eased by INR 600/t to INR 51,900/t ex-works.W-o-w prices moved down by INR 1,100/t.
Price highlights.
End-cutting to billet spread: In Mandi, the spread between end-cutting scrap and billets stood in the range of INR 5,200-5,600/t.
Domestic vs imported scrap: Imported melting scrap prices at Nhava Sheva Port were assessed at $371/t, approximately INR 38,200/t (inclusive of freight). HMS (80:20) prices in Mumbai decreased by INR 100/t d-o-d to INR 36,900/t DAP. Indicative prices of shredded from Europe stood at $416/t CFR Nhava Sheva.
Raipur sponge iron-billet spread: The conversion spread (margin) between pellet-based DRI (P-DRI) and steel billets in Raipur stood at INR 16,250/t.

To see BigMint’s melting scrap assessment, pricing methodology and specification documents, click here
To provide feedback on this index or if you would like to contribute by becoming a data partner, please contact – support@bigmint.co
Leave a Reply