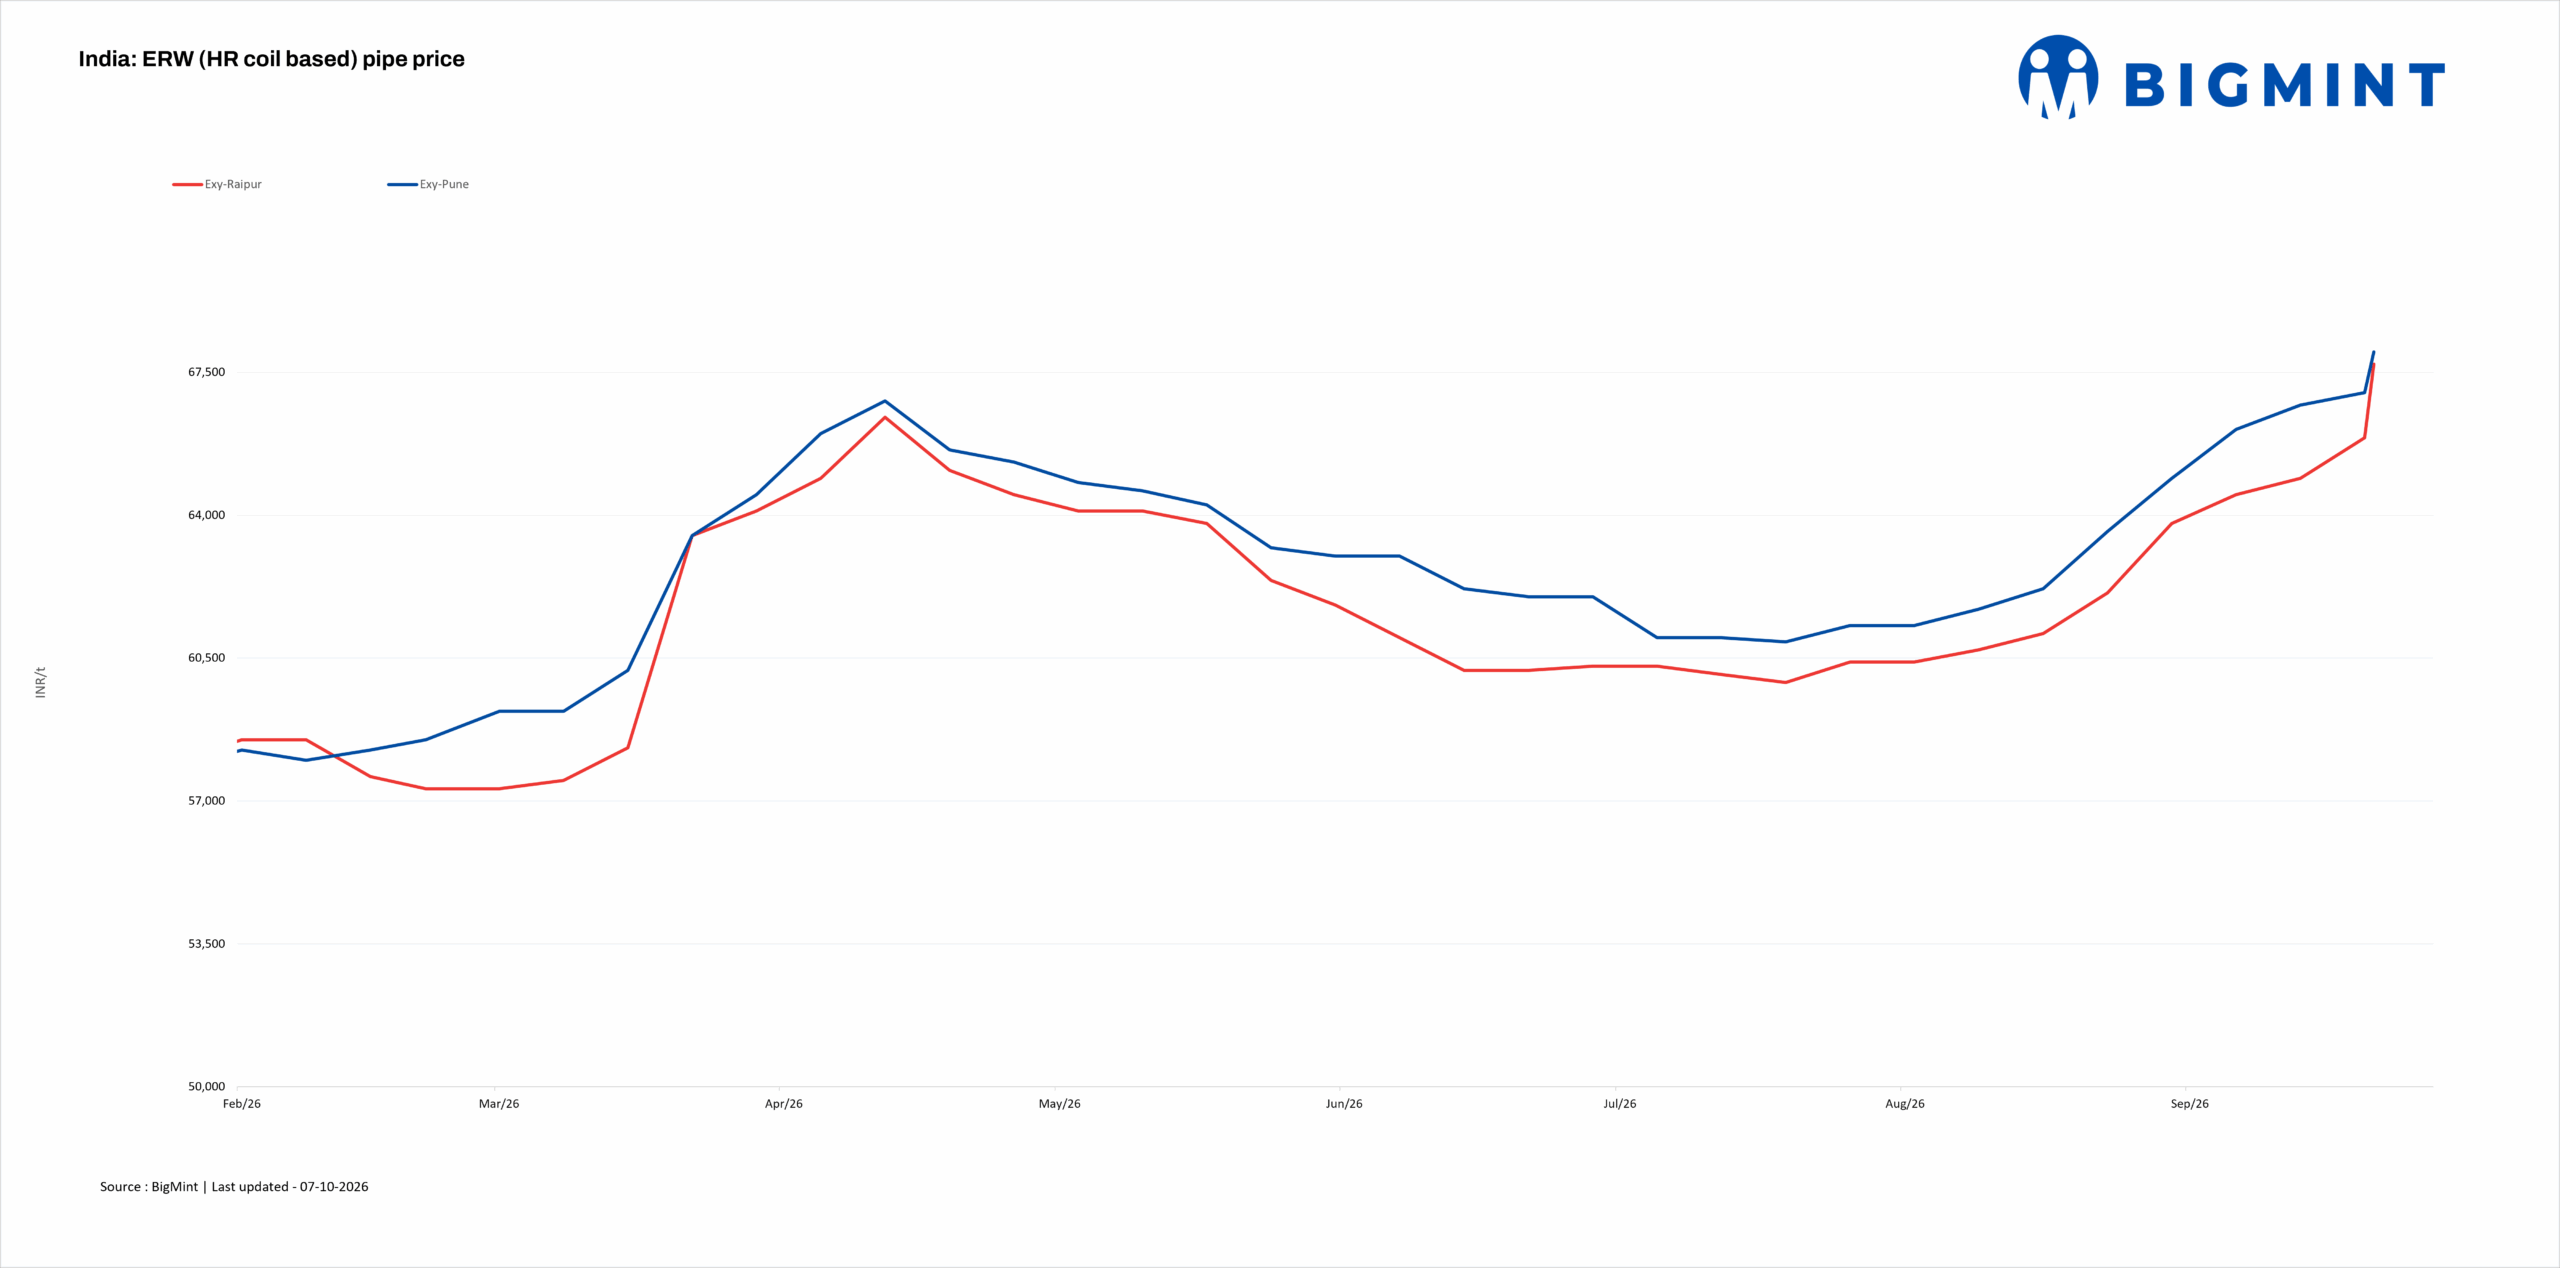
- Higher HRC costs support distributor price increases
- Buyers remain cautious amid comfortable inventories
Indian electric resistance welded (ERW) pipe prices based on hot-rolled coil (HRC) increased by INR 700-1,800/t ($7-18/t) w-o-w across major markets in the week ended 8 October 2026, supported by higher HRC costs and stronger mill price indications. However, the increase was not accompanied by a corresponding improvement in distributor-to-dealer demand, with buyers continuing to procure mainly for immediate requirements.
HRC prices provide cost support
HRC prices edged higher across key markets following recent price increases by domestic mills. BigMint’s bi-weekly benchmark assessment for Mumbai HRC (2.5-8 mm/CTL, IS 2062, Grade E250 BR) rose to INR 64,700/t ex-Mumbai as of 6 October.
Demand remained largely need-based across western and northern India, with buyers showing limited willingness to build inventories at higher price levels. In southern India, demand was mixed, with some participants reporting healthy enquiries while others described market activity as moderate and cautious.
Comfortable inventory levels among traders and distributors continued to limit buying urgency. Market participants said further price increases may face resistance unless inventory levels decline or underlying demand improves.
Distributor prices move higher
Higher HRC replacement costs and firmer mill indications pushed ERW pipe prices higher across key markets.
In Raipur, the weekly average price increased by INR 1,800/t ($18/t) w-o-w to INR 67,700/t ($701/t) on 8 October, from INR 65,900/t ($681/t) a week earlier.
In Pune, the weekly average price rose by INR 1,000/t ($10/t) w-o-w to INR 68,000/t ($702/t), compared with INR 67,000/t ($692/t) in the previous week.
Despite the second price increase in October, buying activity remained subdued. A market participant said, “Many people have enough inventory at previous lower prices, and now there is no uniform pricing in the market as people are trying to sell off existing stock.”
A market participant in South said, “Continuous price increases are not allowing demand to return to normal levels in key regions. People are also preferring secondary pipe brands, especially those who do not have the contract liability associated with primary brands.”
The comments indicate that higher replacement costs are supporting selling prices, but distributors remain cautious about passing on the full increase to end-users amid weak demand visibility.
Major producer raises prices again
Adding to the upward price momentum, a major Indian ERW pipe producer increased its list prices for round pipes by INR 1,500/t ($15/t) across key markets, effective 8 October, compared with its 1 October price list.
Revised list prices for base-grade round pipes of 25-125 NB and 2.2-6 mm thickness stand at INR 69,500/t ($717/t) ex-Raipur, excluding 18% GST.

The latest increase was initially planned for 6 October but was deferred by two days amid concerns over distributor and dealer market conditions. The eventual implementation indicates that the producer continues to prioritise higher realisations while closely monitoring downstream market response.
Outlook
The latest October price increase by a major producer could encourage other suppliers to raise offers further, particularly if HRC costs remain elevated.
However, the sustainability of further increases is likely to depend on buyer response. With distributor demand still subdued and inventories at comfortable levels, buyers may resist additional price increases and continue to limit purchases to immediate requirements.
If pipe prices rise further without a corresponding improvement in end-user demand, distributors may face greater difficulty passing on higher replacement costs, potentially widening the gap between mill indications and actual transaction levels.
Leave a Reply