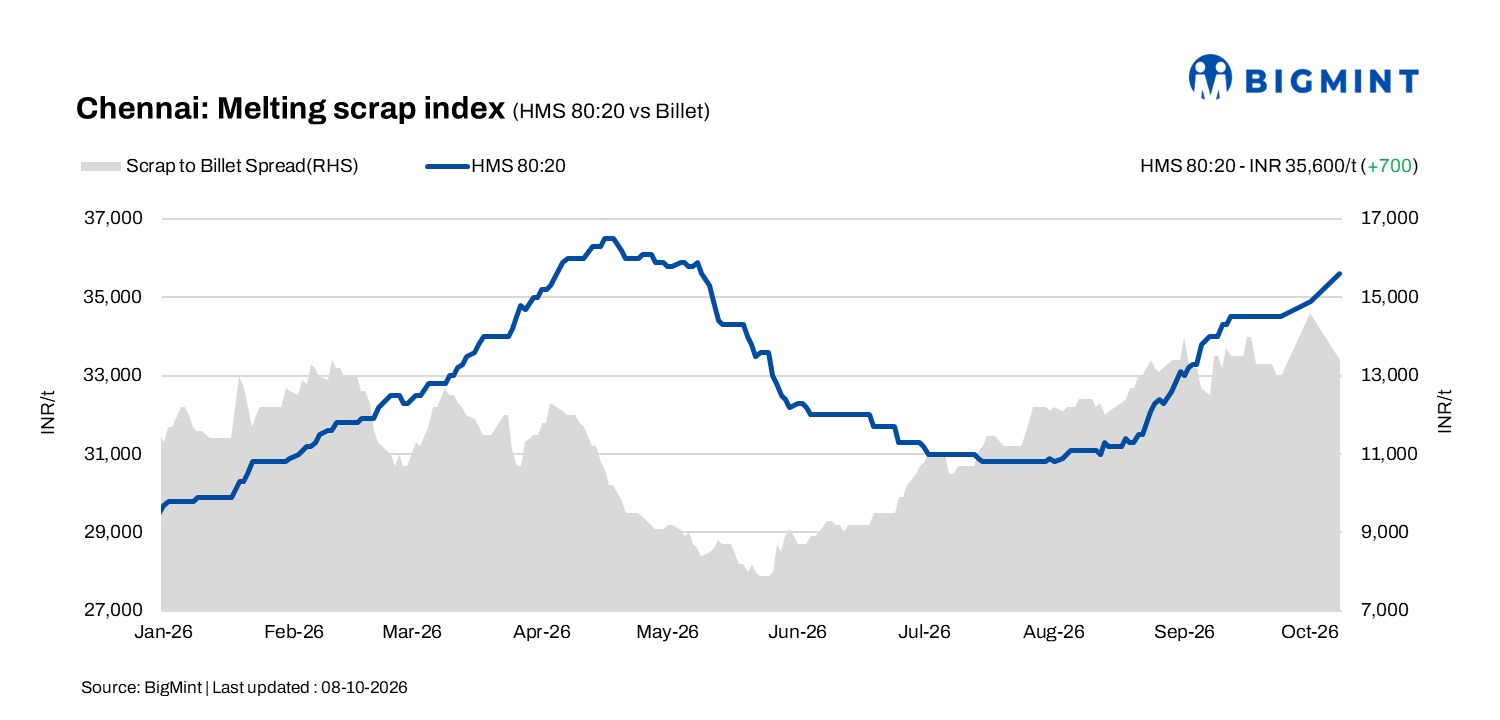
- Domestic scrap availability remains relatively tight
- Project-led rebar demand provides some support to finished steel sales
HMS (80:20) scrap prices in Chennai increased by INR 700/t w-o-w to INR 35,600/t, according to BigMint’s latest assessment on 8 October. In the semi-finished steel segment, billet prices corrected by INR 500/t w-o-w to INR 49,000/t. Billet prices had gained around INR 1,000-1,500/t during the last week of September and first week of October, supported by good demand for Chennai billets and a sudden improvement in project-led rebar demand.
Ferrous scrap prices continued to remain firm, supported by limited domestic scrap availability and steady demand from steelmakers. Rebar prices also increased by INR 500/t w-o-w to INR 53,000/t.
The recent correction in billet prices indicates some moderation in semi-finished steel demand, although improved rebar demand from the project segment continues to provide support to the finished steel market.
Imported and domestic price trends
Market participants reported that Australia-origin shredded scrap was offered at around $380-385/t CFR Chennai, while HMS (80:20) was quoted at $360-365/t CFR. In the domestic market, HMS (80:20) scrap prices increased to around INR 34,900-35,600/t. Limited availability of domestic scrap has continued to support seller price expectations, while buyers remain cautious about taking larger positions at higher levels.

From the second week of October, billet prices corrected by around INR 500/t as MS billet demand from re-rolling mills remained subdued and some trades were concluded at lower levels.
Buyer-supplier sentiments
Market sentiment remains mixed, with improved project-led rebar demand providing support to finished steel sales, while subdued billet demand from re-rolling mills is limiting further upside.
According to market participants, buyers are maintaining a cautious procurement strategy and largely purchasing against immediate requirements. The recent correction in billet prices has made mills more selective in scrap purchases, particularly as higher raw-material costs could put pressure on conversion margins.
Some market participants expect billet prices to remain under pressure if re-rolling mill demand does not improve. However, limited scrap availability is likely to provide downside support to HMS (80:20) prices.
Outlook
Billet prices may remain range-bound in the near term, as improved project-led rebar demand is providing support, while subdued MS billet demand from re-rolling mills is limiting further upside.
HMS (80:20) scrap prices are expected to remain stable to firm, supported by limited domestic scrap availability and steady steelmaker demand. However, cautious mill buying and weaker billet demand could limit further price gains. Further price movement will depend on billet demand, finished steel offtake, mill procurement activity and scrap availability.
Leave a Reply