- Tight cargo availability supports South African coal prices
- Freight markets firm amid tighter prompt vessel availability
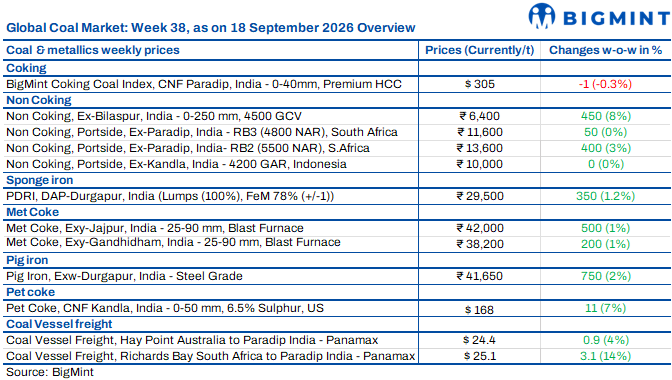
Coal market sentiment remained firm this week as domestic coal availability tightened and imported coal enquiries increased. Lower auction frequency, high premiums and declining port stocks supported import demand. South African and Indonesian coal markets remained supported by tight availability, while overseas demand added further pressure on cargo supply. Steel demand also strengthened, although elevated prices kept buying largely need-based across markets.
Indonesian coal prices remain stable amid tight supply
Indonesian thermal coal prices at Indian ports remained stable w-o-w as tight availability and higher replacement costs supported the market, while high prices limited fresh buying. 5,000 GAR stayed at INR 11,900/t at Kandla and INR 11,800/t at Vizag, while 4,200 GAR remained at INR 10,000/t and INR 9,900/t, respectively. 3,400 GAR at Navlakhi held at INR 8,000/t. Power plant stocks declined around 9% w-o-w to 23.4 mnt as of 17 September, covering around seven days of consumption, with nearly 72 plants at critical levels. However, spot activity remained subdued and purchases were largely need-based. Indonesian benchmarks showed mixed movement, with 4,200 GAR FOB prices declining $1-2/t and 3,400 GAR rising $0.5-1/t.
South African coal prices rise sharply
South African thermal coal prices strengthened further as domestic coal availability remained tight and cargo supply stayed limited. Ex-Paradip RB2 (5,500 NAR) rose INR 400/t w-o-w to INR 13,600/t, while RB3 increased INR 50/t to INR 11,600/t. Ex-Vizag, RB2 climbed INR 500/t to INR 13,600/t and RB3 rose INR 50/t to INR 11,600/t as of 18 September. Import enquiries increased amid lower auction frequency and high premiums at recent MCL and ECL auctions. FOB offers stood around $105/t for 5,500 NAR and $93/t for 4,800 NAR. Port stocks fell 3% w-o-w to 13.08 mnt, while limited cargo availability and firm overseas demand supported prices. PDRI ex-Raipur rose INR 350/t w-o-w to INR 29,500/t.
Domestic coal prices rise amid limited availability
Domestic coal prices strengthened during the week amid limited availability and reduced access to auctioned coal. Ex-Bilaspur 4,500 GCV coal increased INR 450/t w-o-w to INR 6,400/t, while 5,000 GCV coal rose INR 50/t to INR 8,100/t as of 18 September. The absence of a fresh SECL auction schedule further constrained raw coal availability, while recent auction prices had remained elevated. Higher domestic coal prices increased replacement costs for consumers and added pressure on downstream coal markets.
Washed coal prices rise on ROM shortage
Washed coal prices increased sharply, with 38-39% FC (5,000 GCV) washed coal FOR Raipur rising INR 450/t w-o-w to INR 8,750/t. Limited ROM availability restricted washery operations, with production remaining low and several sellers reluctant to offer material. Some suppliers explored coal from other regions to meet requirements, but higher sourcing costs kept offers firm. Improved sponge iron prices also provided support to washed coal demand, although buyers remained cautious at elevated prices.
US NAPP coal supply tightens further
US NAPP coal availability tightened sharply, with November-December cargoes offered around $170/t CFR India. Core Natural Resources was reportedly booked through January 2027, while February-onwards cargoes were offered around $120/t FOB Baltimore. Indian retail NAPP/ILB stocks at Kandla and Tuna fell 52% w-o-w to around 24,200 t on 14 September from 50,841 t. Portside offers rose to INR 17,000-18,000/t, with some indications reaching INR 18,200/t, although trading remained limited as buyers resisted higher prices. Earlier cargoes continued to arrive for major cement producers, but these shipments had largely been contracted earlier. Tight retail stocks and higher replacement costs reduced the availability of NAPP as an alternative fuel for cement producers.
Met coke prices rise on tight supply
India’s domestic met coke prices strengthened during the assessment week, supported by limited imported coke availability and firm replacement costs. BF-grade prices in eastern India rose INR 500/t w-o-w to INR 42,000/t ex-Jajpur, while western India prices increased INR 200/t to INR 38,200/t ex-Gandhidham. Foundry-grade coke at Rajkot gained INR 500/t to INR 39,500/t. Limited Indonesian met coke availability, with supplies reportedly committed through November, kept near-term supply constrained. However, softer coking coal costs could gradually reduce coke production and replacement costs. If this trend continued and coke availability improved, domestic met coke prices could face downward pressure in the coming period.
Petcoke prices rise on tighter supply
Global petcoke prices strengthened further in September, with 6.5% sulphur US Gulf Coast petcoke reaching $93/t FOB on 16 September, up $3/t w-o-w. Indian indications rose to $165-175/t CFR by 18 September, with market checks mainly around $170/t. Higher prices led cement producers to become more cautious, with some avoiding fresh purchases and relying on existing inventories or domestic alternatives. Petcoke had earlier encouraged greater NAPP consumption, but the simultaneous rise in NAPP prices reduced fuel-switching options. Physical imports continued, including cargoes for major cement producers, although many arrivals had been contracted earlier and did not reflect current replacement costs.
Petcoke prices rise further
India’s domestic petcoke prices increased further in September, with IOCL raising prices by INR 970/t across refineries, followed by Nayara Energy and MRPL hikes of INR 690/t and INR 680/t, respectively. IOCL prices reached INR 17,210/t at Koyali, INR 18,470/t at Panipat, INR 16,220/t at Paradip and INR 16,340/t at Haldia. Nayara increased its price to INR 18,780/t, while MRPL raised road prices to INR 17,300/t. BPCL kept prices unchanged at INR 18,000/t at Bina and Kochi. Firm international prices, higher freight and marine insurance costs supported replacement costs, while MRPL’s restricted availability also supported the market.
India-bound coal freight remained firm
India-bound coal freight rates remained firm but mixed during the week ended 18 September, with tighter prompt tonnage supporting Panamax rates. Australia-Paradip freight rose $0.9/t w-o-w to $24.4/t, while RBCT-Paradip increased $3.1/t to $25.1/t. Supramax rates softened, with East Kalimantan-Navlakhi falling $0.4/t to $21.5/t and South Kalimantan-Navlakhi declining $1.4/t to $20.4/t. South Africa-India freight gained from stronger Atlantic activity and tighter tonnage, while charterers remained cautious on higher freight ideas. The BDI declined 5.3% w-o-w to 3,336 as of 16 September, while Supramax increased 2.9% to 1,762. Bunker prices remained elevated, although Singapore VLSFO eased to around $895/t on 18 September.
Leave a Reply