- PSIC-related issues disrupt procurement in India, Pakistan
- Firm freights keep Turkish scrap market sentiment bullish
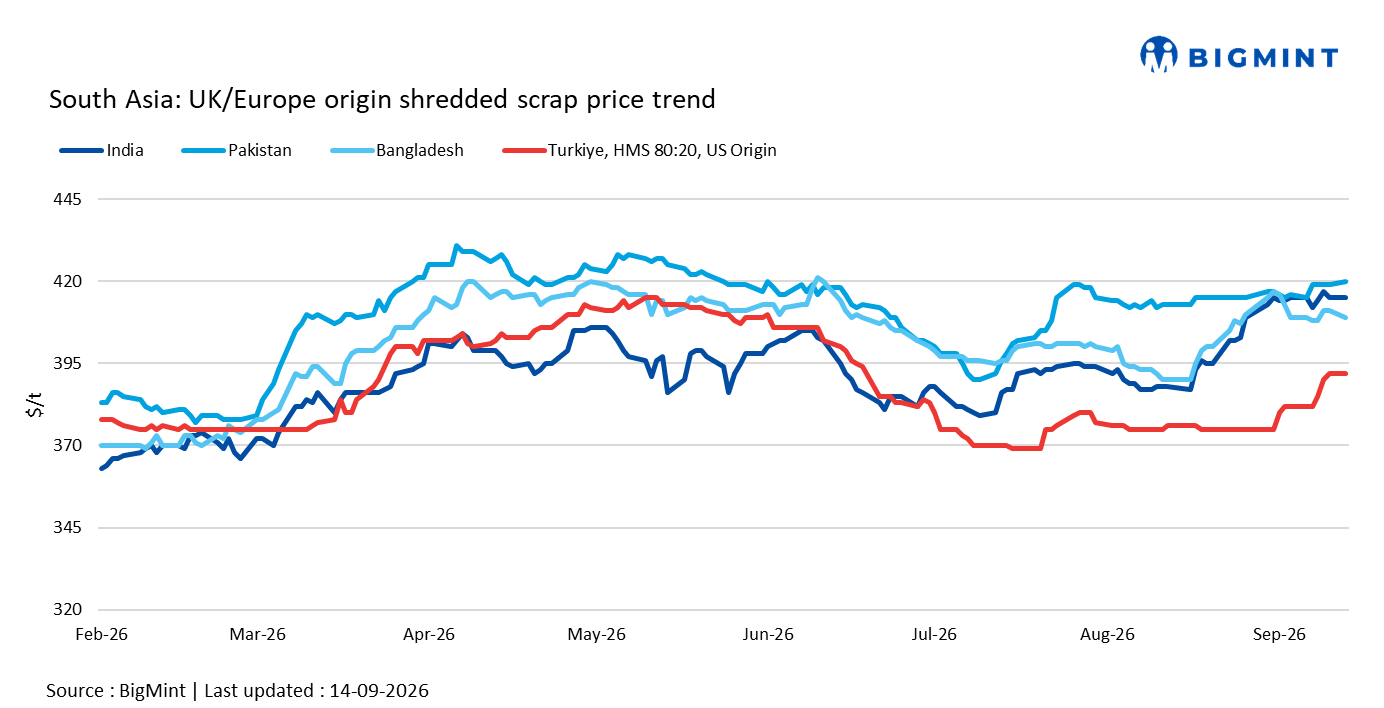
South Asian imported scrap markets remained firm on 14 September, with Indian prices strengthening on limited African HMS availability, Pakistani levels supported by a GI bundle trade, and Bangladeshi prices holding elevated levels. Meanwhile, Turkiye remained stable amid firm freights and cautious mill buying.
India: The imported scrap market strengthened, with an African-origin HMS 80:20 booked at $375/t CFR Mundra, while current offers stood at $375-380/t. Imports of HMS 80:20 from Mozambique and Europe were indicated at $370-375/t, with a 500-t West African hand-loaded HMS cargo at $380/t CFR Mundra.
African supply remained challenging due to Pre-Shipment Inspection Certificate (PSIC)-related issues, but market participants have found solutions to keep material moving. Loadings are continuing largely as usual, although some African ports still face procedural issues, with shipping lines accepting letters of intent (LOIs) from PSIC agencies in certain cases.
Pakistan: The imported scrap market remained firm, with a deal for Philippines-origin GI bundles reportedly closed at $360/t. However, buyers remained cautious as existing orders neared completion and PSIC-related issues disrupted procurement. Higher freight costs also made fresh imports less viable across the Indian subcontinent.
Bangladesh: Imported scrap market remained firm d-o-d, with Brazil-origin shredded scrap reportedly booked at $400/t CFR Chattogram and HMS 90:10 at $380/t. UK/EU shredded scrap offers were around $400/t for 20-ft containers, while HMS was offered at $370-375/t. EU sellers were asking as high as $425/t for shredded, but buyers were unwilling to accept these levels.

Turkiye: The deep-sea imported scrap market remained stable d-o-d, with FSR Baltic reportedly selling HMS 80:20 at $390/t CFR Turkiye. Earlier in the week, an EU-origin HMS 80:20 cargo was booked by an Iskenderun-based mill at $381/t CFR, keeping recent deal levels elevated.
Market sentiment remained mixed, with some US suppliers expecting prices to rise towards $395/t CFR, while others remained cautious. Firm freights were a key driver of higher offers, although improved finished-steel sentiment also helped mills accept elevated scrap prices. Turkish mills remained cautious at higher levels while completing October procurement.

Leave a Reply