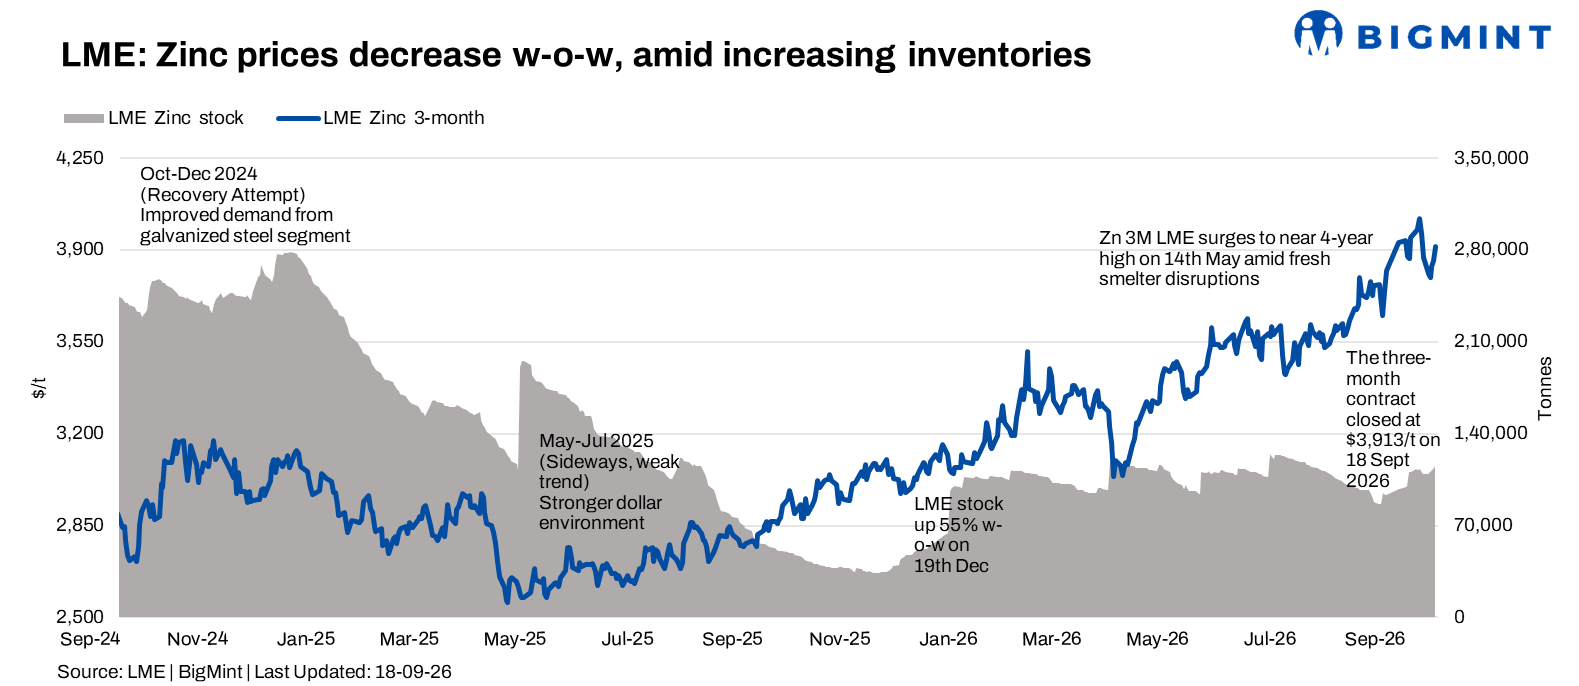
- LME zinc stays near $4,000/t despite a 5.2% weekly rise in inventories
- MCX zinc gains 3.4% as prices rise despite lower open interest
LME zinc prices recovered during the week after falling to $3,922/t, with renewed supply concerns supporting the market. LME cash settlement declined marginally by 0.1% to $4,010/t on 18 September from $4,015/t on 11 September. The three-month contract, however, rose 1.1% to $3,913/t.
LME inventories increased by 5,725 t, or 5.2%, to 115,300 t during the week from 109,575 t. The cash-to-three-month backwardation narrowed to $97/t from $143/t, indicating some easing in nearby physical tightness.
Supply concerns return as Korea Zinc accident raises risks
Zinc prices received fresh support after a fatal accident at Korea Zinc’s Onsan smelter in South Korea on 16 September raised concerns over possible disruption to refined zinc supply. However, the actual impact on production remained uncertain.
The development comes amid tight concentrate availability and sharply lower treatment charges. Lower output at major mines, including Antamina in Peru and Red Dog in Alaska, has also added to supply concerns.
Global refined zinc fundamentals remained mixed. The market moved into a 31,400-t deficit in June from a 22,400-t surplus in May, although H1 remained in a 120,000-t surplus. Glencore’s H1 own-sourced zinc production fell 21% y-o-y to 365,600 t, while Nexa’s Q2 output rose 8% to 79,300 t.
Rising LME inventories provide some counterweight to supply concerns, while higher zinc prices are weighing on downstream buying and could encourage additional Chinese exports.
MCX zinc gains 3.4% as open interest declines
MCX zinc futures strengthened during the week, with the September contract closing at INR 433,050/t on 18 September against INR 418,750/t on 11 September, up INR 14,300/t, or 3.4%.
The contract touched a weekly high of INR 434,700/t and a low of INR 408,200/t. Open interest declined 23% to 2,022 lots from 2,635 lots.
The strongest move came during the final two sessions, with prices rising from INR 420,100/t on 16 September to INR 433,050/t on 18 September.
SHFE zinc also moved to a higher price centre. The most-traded 2611 contract closed at 26,565 yuan/t on 18 September, while open interest increased by 2,418 lots to 130,000 lots. Domestic inventory drawdowns supported prices, although higher levels kept downstream buying cautious.
Domestic zinc market remains firm
India’s domestic zinc market remained firm amid elevated international prices and the higher HZL benchmark.
HZL had raised its SHG zinc benchmark by INR 12,300/t to INR 437,400/t on 10 September, reversing the INR 9,300/t cut announced on 7 September.
BigMint’s SHG zinc assessment was around INR 432,000/t ex-Delhi during the week, keeping spot levels below the HZL benchmark.
Higher international prices and replacement costs continue to support domestic levels, while need-based downstream buying and cautious galvaniser demand could limit further upside.
Outlook
LME zinc is expected to remain volatile as supply concerns are balanced against rising inventories and moderating nearby tightness.
The recovery towards $4,000/t keeps supply risks in focus, particularly following the Korea Zinc incident and continued pressure on treatment charges. However, the 5.2% inventory increase and narrower backwardation indicate some easing in immediate physical tightness.
Support is seen at $3,900-3,920/t, while resistance is expected around $4,010-4,100/t. LME inventories, backwardation, Chinese exports, treatment charges and smelter developments will remain key indicators for zinc prices.
Leave a Reply