- Inventories fall despite firm imported coal prices
- Mundra remains the largest stockholding port
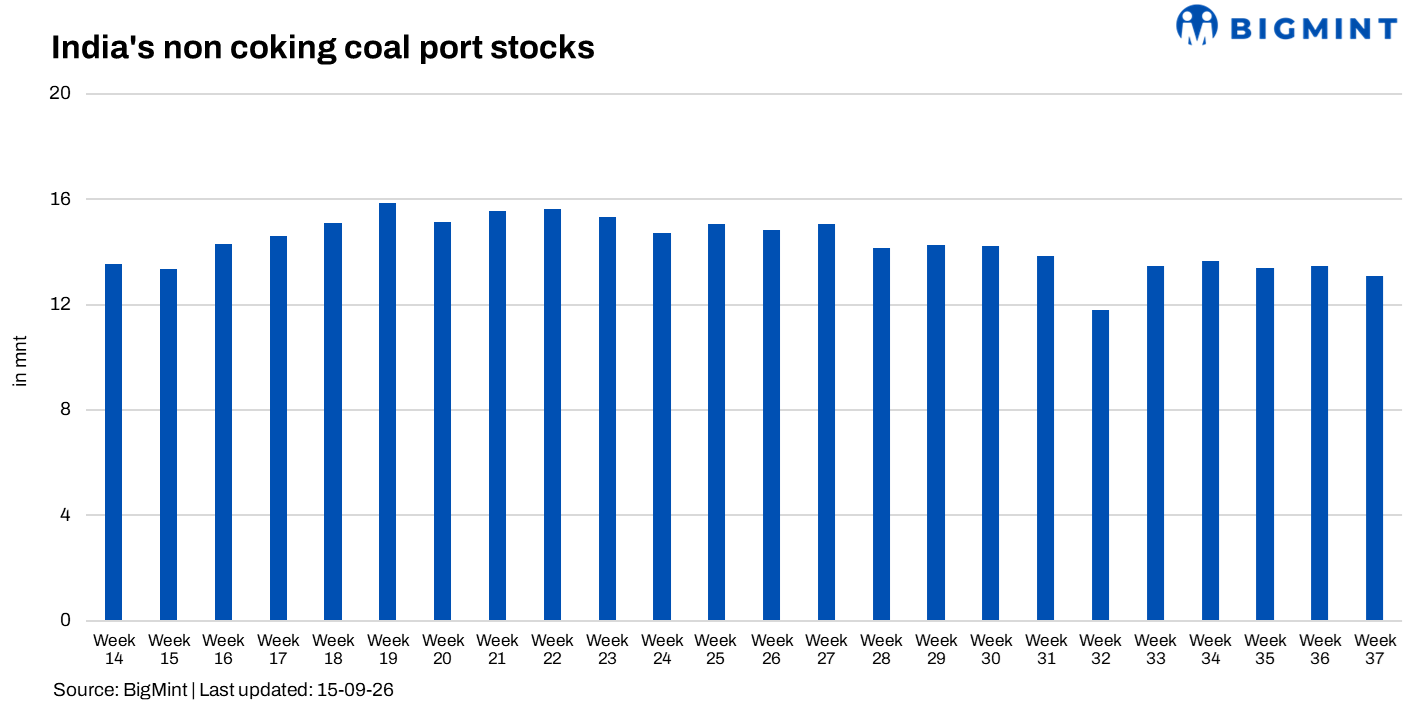
India’s thermal coal inventories at major ports declined 3% w-o-w to 13.08 mnt in week 37, from 13.48 mnt in week 36. The decline reflected continued cargo evacuation at several major ports, particularly Kandla, Magdalla, Krishnapatnam and Dahej. However, higher stocks at Karaikal, Gopalpur and Gangavaram partly offset the drawdown. Market sentiment remained firm as Indonesian and South African thermal coal prices strengthened amid tighter availability and higher replacement costs, although elevated prices continued to keep buying largely need-based.
Major ports see continued stock drawdown
Inventory movements were largely negative across major stockholding ports during the week. Mundra stocks declined 1.4% w-o-w to 1.96 mnt from 1.98 mnt, while Paradip fell 1.8% to 1.26 mnt from 1.28 mnt. Krishnapatnam stocks declined 9.2% to 1.14 mnt from 1.25 mnt, indicating continued evacuation of imported cargo.
Dahej inventories fell 6.3% to 0.97 mnt, while Kandla recorded a sharper 12.1% decline to 0.73 mnt from 0.83 mnt. Magdalla stocks dropped 17.9% to 0.41 mnt, and Tuna declined 23.2% to 0.17 mnt.
In contrast, Karaikal inventories increased 19.1% to 0.26 mnt, while Gopalpur and Gangavaram rose 131.9% and 89.4%, respectively. The increase at these ports partly offset declines elsewhere, but did not prevent the overall inventory drawdown.

The mixed port movements indicated that stock levels continued to be influenced by vessel arrivals and cargo evacuation rather than a broad change in consumption.
Imported coal costs keep buying selective
Imported thermal coal prices remained firm during the week, with Indonesian and South African prices reaching multi-year highs. Indonesian 5,000 GAR increased to INR 11,900/t at Kandla, while 4,200 GAR rose to INR 10,000/t. South African RB2 also strengthened to INR 13,200/t ex-Paradip.
Higher international energy costs, tighter supply and firm demand from other destinations continued to support seller offers. Indonesian non-coking coal exports declined 16.1% y-o-y to 26.95 mnt in August, while South African coal remained supported despite lower Indian imports.
The rise in replacement costs has, however, limited aggressive procurement. Buyers continued to make small, need-based purchases, while using available domestic coal wherever possible. This has supported cargo evacuation without triggering broad-based restocking at ports.
Domestic coal prices also remained firm, with 5,000 GCV coal rising to INR 8,000/t and 4,500 GCV coal to INR 5,900/t. Tight domestic availability and higher auction realisations continued to keep replacement costs elevated.
Major holders maintain selective inventory positions
Stock movements among major coal holders remained mixed. Adani Enterprises held broadly stable inventories at around 4.79 mnt, compared with 4.79 mnt in week 36. Adani Power reduced stocks to 0.71 mnt from 0.79 mnt, while Agarwal Coal declined to 0.53 mnt from 0.57 mnt.
Tata Power stocks also fell to 0.52 mnt from 0.65 mnt. In contrast, ArcelorMittal increased inventories to 1.20 mnt from 1.19 mnt, while Ultratech Cement rose to 0.43 mnt from 0.41 mnt.

The divergence suggests that consumers and traders continued to adjust inventories according to individual requirements and availability rather than following a uniform stocking strategy.
Overall, port inventories are likely to remain under pressure if cargo evacuation continues. However, elevated imported coal prices could limit fresh bookings, keeping inventory replenishment measured. Any improvement in domestic coal availability or easing of international prices could further influence buying decisions in the coming weeks.
Leave a Reply