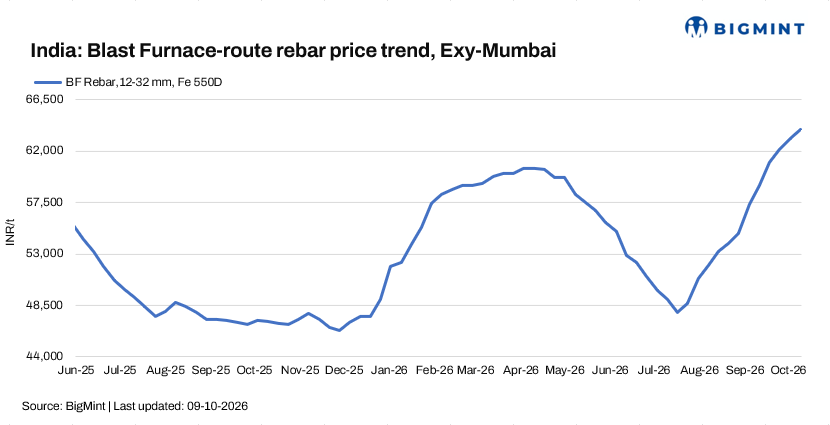
- Blast Furnace -route rebar prices rose INR 800/t to INR 63,900/t.
- Infrastructure orders and mill price hikes supported market sentiment.
Trade-level Blast Furnace-route rebar prices (distributor-to-dealer) increased by INR 800/t ($8/t) week-on-week (w-o-w) to INR 63,900/t ($660/t) ex-Mumbai, according to BigMint’s assessment on 9 October 2026.
The increase came amid improved buying activity, primarily driven by active project requirements. Market sentiment strengthened further as several mills resumed production following scheduled maintenance and worked towards restoring capacity to normal operating levels. However, the pace of supply recovery remained a key factor influencing market sentiment.
Rebar prices for project sales were heard workable at INR 64,000-66,000/t ($662–683/t) landed. Buyers continued procurement at elevated price levels, partly anticipating further increases amid concerns over supply availability. Several mills also raised their list prices by around INR 1,000/t, reflecting a firm pricing stance amid limited availability of prompt material.
Notably, trade-level BF-route rebar prices have reached a multi-year high, supported by supply-side constraints, improving project-led demand and continued mill price hikes.
Factors Driving the Market
1. IF-Route Rebar: Mixed Price Trends Amid Cautious Buying
IF-route rebar prices witnessed mixed movements this week, fluctuating by INR 200-1,300/t across markets. Rising raw material costs, particularly coal, increased production expenses and encouraged mills to maintain higher finished steel offers. However, spot-market trading remained subdued to moderate, with no significant improvement in sales activity.
Mill inventories were estimated at around 8-10 days, while order-book visibility remained limited to 3-5 days, varying by location. Elevated finished steel prices continued to face resistance from buyers, with procurement largely restricted to immediate requirements.
The near-term outlook remains range-bound, as buyers continue to adopt a cautious wait-and-watch approach. Further price movements will depend on raw material cost trends and a sustained improvement in underlying steel demand. Meanwhile, the price spread between BF- and IF-route rebar in Mumbai widened further week-on-week to around INR 10,400/t ($107/t). IF-route rebar continues to dominate the Indian market, accounting for an estimated 65-70% share.
2. Blast Furnace-Route Raw Material Costs: Mixed Trends Provide Cost Support
Major raw materials used in BF-route steelmaking witnessed mixed price movements during the week. BigMint’s Odisha iron ore fines (Fe 62%) index increased by INR 50/t to INR 5,500/t ($52/t) ex-mines as of 3 October.
In contrast, premium hard coking coal (PHCC) prices declined marginally by $1/t week-on-week to $294/t CNF Paradip, offering limited relief on the input cost front.
Overall, raw material prices continued to provide support to finished steel prices, while limited mill margins restricted the scope for aggressive price corrections. The direction of raw material costs, alongside the pace of supply recovery and project-led demand, will remain key factors influencing the near-term BF-route rebar market.
Project Update
India’s infrastructure sector recorded major order wins across power, renewable energy, roads, railways and industrial construction. Key developments included L&T’s INR 10,000-15,000 crore power transmission orders, Bondada Engineering’s INR 1,154 crore solar EPC contract, Dilip Buildcon’s INR 1,800 crore LPG pipeline project and Swastika Infra’s INR 615.76 crore distribution infrastructure contract. These projects are expected to support steel demand, particularly for TMT rebar, structural steel, plates and fabricated products, as execution progresses.
Outlook
BF-route rebar prices may remain firm amid tight prompt supply, ongoing project demand and mill price hikes. However, production recovery and buyer resistance at elevated levels could limit further gains in the near term.
Leave a Reply