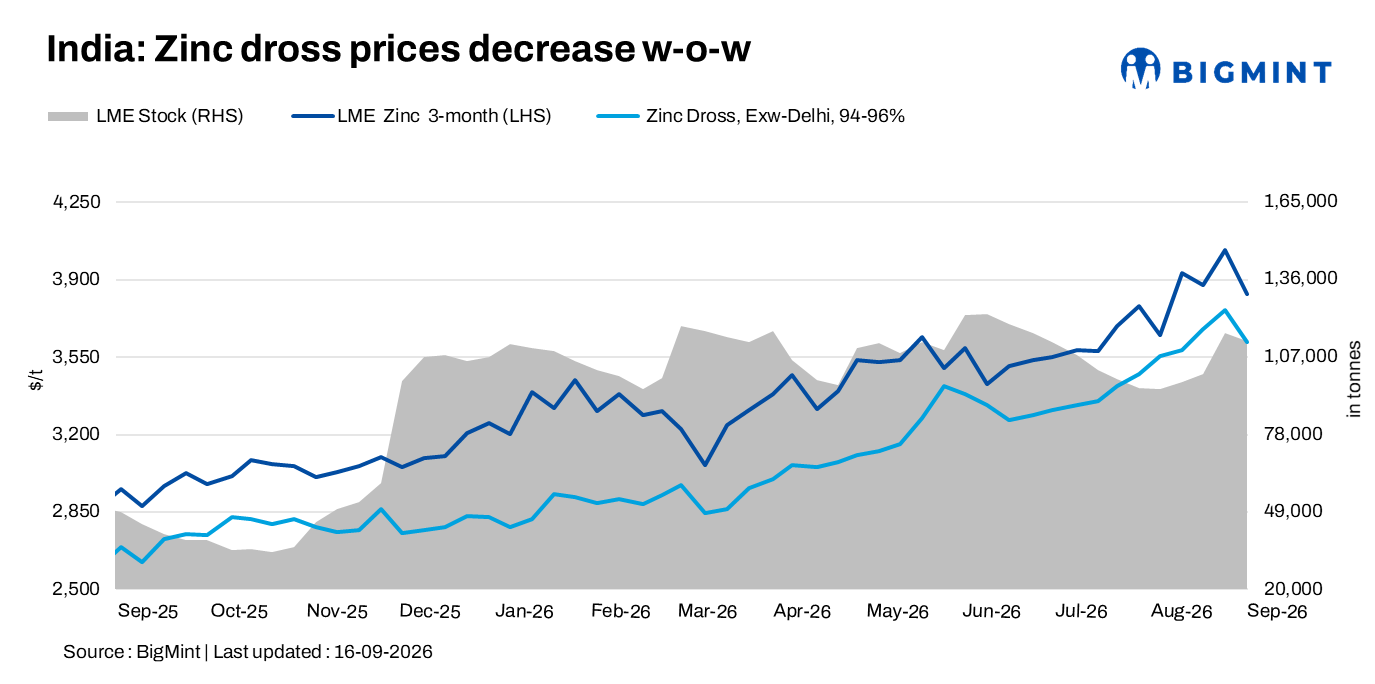
- LME zinc declines by 5% w-o-w; backwardation narrows
- Prices of zinc scrap, domestic SHG ingots remain relatively stable
India’s zinc dross and oxide prices declined w-o-w in the week ended 16 September, tracking weaker international zinc prices and a marginal decline in domestic primary zinc values. Secondary zinc prices eased during the week, while LME zinc corrected from the elevated levels seen earlier in September.
Three-month LME zinc declined by $199/t, or 4.9%, w-o-w to $3,837/t on 16 September from $4,036/t on 9 September. The cash-settlement price fell by $249/t to $3,937/t.
The cash-to-three-month backwardation narrowed to $100/t from $150/t a week earlier, indicating a reduction in the premium for nearby metal. Meanwhile, LME inventories declined by 3,000 t to 112,675 t from 115,675 t a week earlier.
Zinc dross, oxide prices fall
Domestic zinc dross prices declined by INR 10,000/t w-o-w to INR 347,500/t ex-Delhi on 16 September, compared with INR 357,500/t a week earlier. Zinc oxide (99% Zn) prices also decreased by INR 8,800/t w-o-w to INR 332,000/t ex-Delhi from INR 340,800/t. The decline in secondary zinc prices followed the correction in international zinc prices and lower domestic primary zinc values.
Zinc scrap prices remain broadly stable
In the north Indian zinc scrap market, prices of small Tukdi (97-98% Zn) were relatively stable, assessed at around INR 337,000/t ex-Delhi. Mid-sized Tukdi (97-98% Zn) was reported at around INR 350,000/t, while big Tukdi (97-98% Zn) was around INR 353,000/t.
Domestic SHG zinc edges lower
BigMint’s assessment of domestic SHG zinc ingot prices stood at INR 435,000/t ex-Delhi on 16 September, down INR 1,000/t from INR 436,000/t on 9 September.
The marginal decline in domestic primary zinc values followed the correction in LME zinc prices during the week. However, the domestic SHG price remained broadly stable compared with the sharper declines recorded in international zinc and secondary zinc products.
The latest domestic SHG level remains elevated despite the weekly decline, while the narrowing cash-to-three-month backwardation indicates a reduction in near-term price tightness compared with the previous week.
LME zinc prices, exchange inventories and the cash-to-three-month spread will remain important indicators for the secondary market. Although LME stocks declined by 3,000 t during the week, the correction in zinc prices and narrowing backwardation indicate weaker price momentum compared with the previous week.
Outlook
Zinc dross and oxide prices may remain under pressure in the coming week if domestic SHG zinc and international zinc prices remain subdued.
The decline in LME zinc and narrowing cash-to-three-month backwardation could weigh on replacement costs, while the marginal movement in domestic SHG zinc may provide some stability to secondary zinc prices.
Further price movement in dross and oxide is likely to depend on the direction of primary zinc prices and changes in LME inventory levels.
Leave a Reply