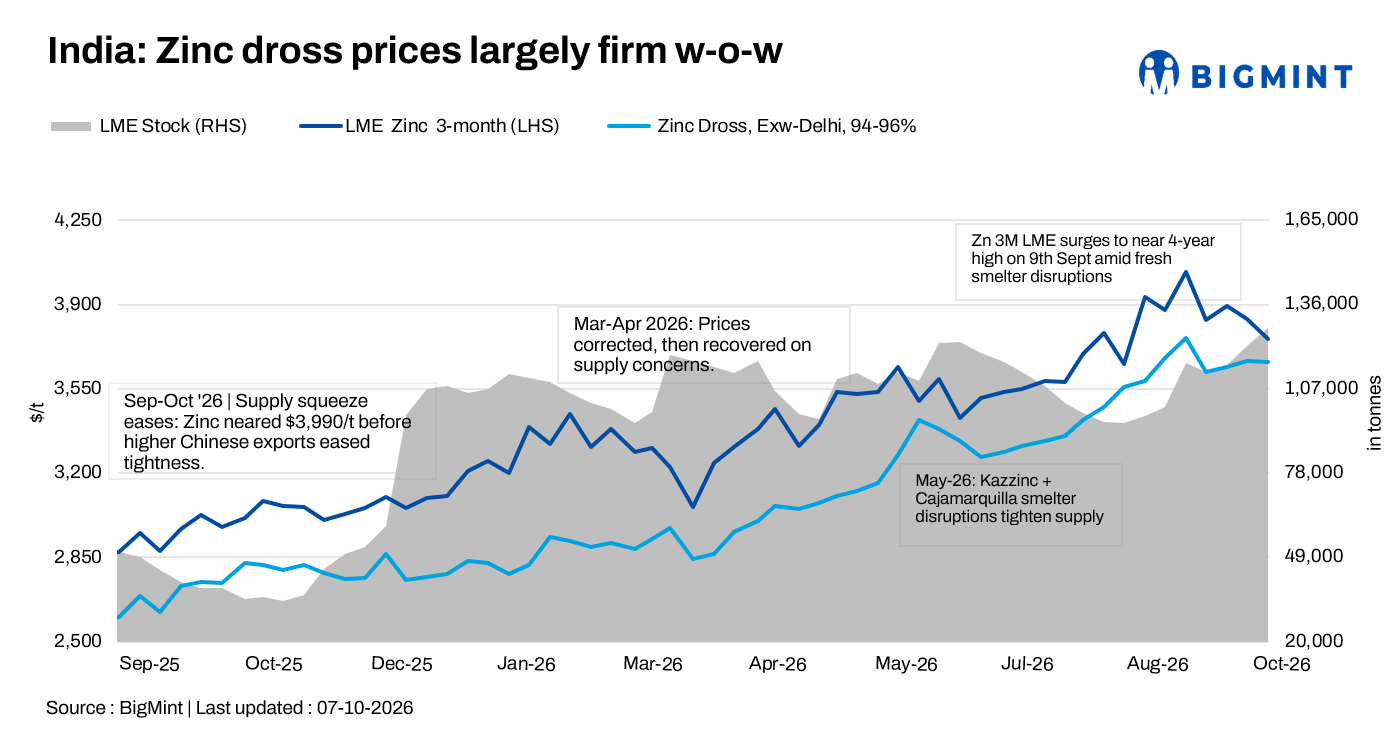
- LME zinc 3-month price declines 2.2% w-o-w; backwardation narrows
- Zinc scrap prices decline marginally
India’s zinc dross and oxide prices moved in different directions in the week ended 8 October, despite a decline in three-month LME zinc prices and domestic SHG zinc. Zinc dross prices declined marginally, while zinc oxide prices increased, reflecting mixed movement in the secondary market.
Three-month LME zinc declined by $86/t, or 2.2%, w-o-w to $3,756/t on 7 October from $3,842/t on 30 September. The cash-settlement price declined by $155/t to $3,799/t.
The cash-to-three-month backwardation narrowed to $43/t from $112/t a week earlier, indicating some easing in nearby tightness. Meanwhile, LME inventories increased by 6,150 t to 127,750 t from 121,600 t a week earlier.
Zinc dross, oxide prices mixed
Domestic zinc dross prices declined marginally by INR 200/t w-o-w to INR 351,700/t ex-Delhi on 8 October, compared with INR 351,900/t a week earlier. Zinc oxide (99% Zn) prices increased by INR 1,700/t to INR 334,700/t ex-Delhi from INR 333,000/t.
The mixed movement in secondary zinc prices came despite weaker three-month LME zinc and lower domestic SHG zinc. Market participants reported limited movement in zinc scrap, while secondary zinc prices remained supported by domestic replacement costs.
Zinc scrap prices decline marginally
In the north Indian zinc scrap market, big Tukdi (97-98% Zn) was assessed at around INR 352,000/t ex-Delhi, while mid-sized Tukdi (97-98% Zn) was around INR 347,000/t. Small Tukdi was assessed at around INR 337,000/t.
Scrap prices declined marginally during the week, with big Tukdi down INR 2,000/t, mid-sized Tukdi down INR 1,000/t and small Tukdi down INR 2,000/t.
Domestic SHG zinc edges lower
BigMint’s assessment of domestic SHG zinc ingot prices stood at INR 437,000/t ex-Delhi on 8 October, down INR 1,000/t from INR 438,000/t on 30 September.
Hindustan Zinc Ltd (HZL) reduced its benchmark Special High-Grade (SHG) zinc ingot price by INR 1,500/t in its latest revision to INR 408,200/t. The company increased its lead benchmark by INR 1,100/t to INR 212,600/t.
The decline in domestic primary zinc values was broadly in line with weaker LME zinc prices. Meanwhile, the narrowing cash-to-three-month backwardation and rising LME inventories indicated easing nearby tightness compared with the previous week.
China’s domestic zinc market remained closed from 1-7 October for the National Day holiday, with trading suspended. Overseas zinc prices declined during the holiday amid pressure from a stronger US dollar and higher Treasury yields.
Outlook
Zinc dross and oxide prices may remain broadly stable in the coming week, with weaker LME zinc and rising exchange inventories limiting upside, while domestic replacement costs could provide some support.
The narrower LME cash-to-three-month backwardation and higher inventories suggest easing nearby market tightness. However, the post-holiday return of Chinese market participants and developments in domestic demand will remain important for price direction.
Further movement in dross and oxide is likely to depend on the direction of primary zinc prices, LME inventory levels, nearby spreads and domestic demand.
Leave a Reply