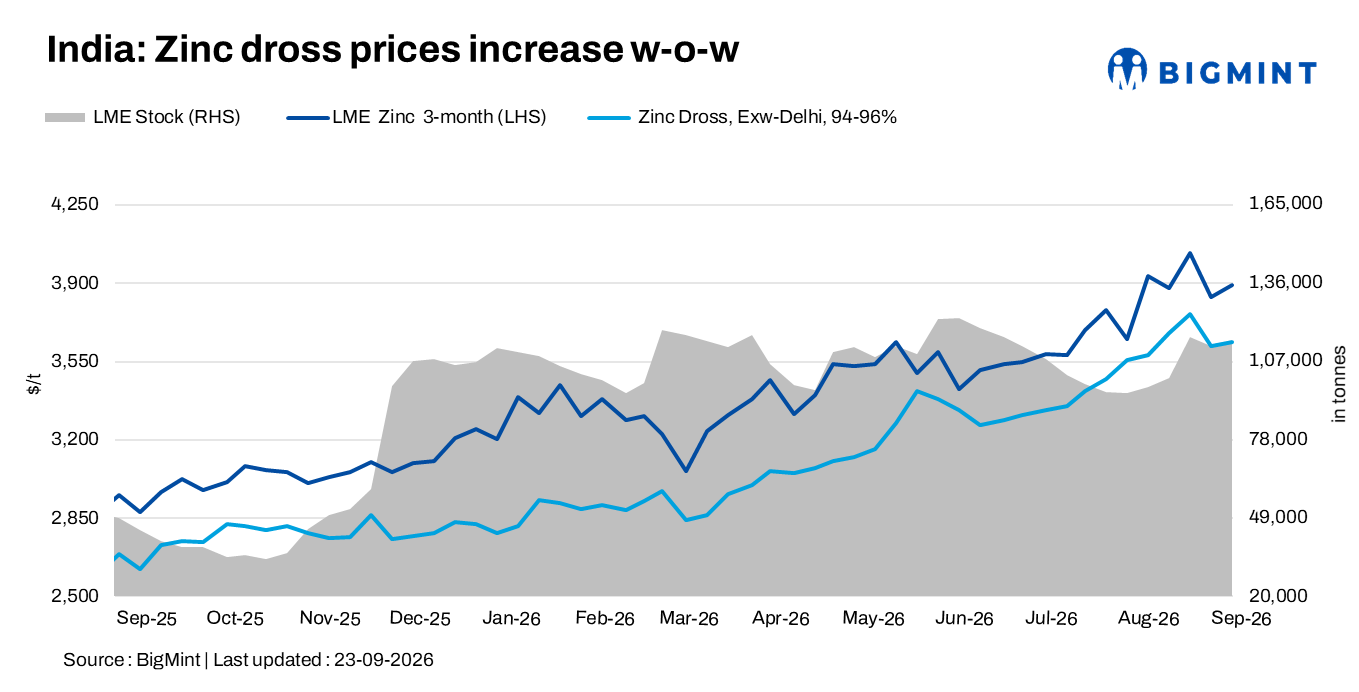
- LME zinc 3-month price rises 1.5% w-o-w; backwardation narrows
- Zinc dross edges higher, while oxide prices remain broadly stable
India’s zinc dross and oxide prices were mixed w-o-w in the week ended 23 September, as international zinc prices recovered modestly while domestic primary zinc values moved higher. Zinc dross prices increased marginally, whereas zinc oxide prices remained broadly stable.
Three-month LME zinc increased by $56/t, or 1.5%, w-o-w to $3,893/t on 23 September from $3,837/t on 16 September. The cash-settlement price increased by $12/t to $3,949/t.
The cash-to-three-month backwardation narrowed to $56/t from $100/t a week earlier, indicating reduced tightness in nearby metal. Meanwhile, LME inventories increased by 2,200 t to 114,875 t from 112,675 t a week earlier.
Zinc dross, oxide prices mixed
Domestic zinc dross prices increased by INR 1,900/t w-o-w to INR 349,400/t ex-Delhi on 23 September, compared with INR 347,500/t a week earlier. Zinc oxide (99% Zn) prices declined marginally by INR 300/t to INR 331,700/t ex-Delhi from INR 332,000/t.
The mixed movement in secondary zinc prices came amid a modest recovery in international zinc prices and firmer domestic primary zinc values.
Zinc scrap prices remain broadly stable
In the north Indian zinc scrap market, mid-sized Tukdi (97-98% Zn) was assessed at around INR 349,000/t ex-Delhi, while big Tukdi (97-98% Zn) was around INR 354,000/t.
The market remained relatively stable, with limited movement reported in zinc scrap prices during the week.
Domestic SHG zinc moves higher
BigMint’s assessment of domestic SHG zinc ingot prices stood at INR 438,700/t ex-Delhi on 23 September, up INR 3,700/t from INR 435,000/t on 16 September.
The increase in domestic primary zinc values followed the recovery in international zinc prices during the week. The rise in SHG zinc also provided support to domestic secondary zinc prices, particularly zinc dross.
The latest domestic SHG level remains elevated, while the narrowing cash-to-three-month backwardation indicates reduced near-term tightness compared with the previous week.
LME zinc prices, exchange inventories and the cash-to-three-month spread will remain important indicators for the secondary market. Although LME stocks increased during the week, the recovery in zinc prices and higher domestic SHG values provided some support to secondary zinc prices.
Outlook
Zinc dross and oxide prices may remain broadly stable in the coming week if domestic SHG zinc and international zinc prices hold at current levels.
The recovery in LME zinc and higher domestic SHG prices could support replacement costs, while rising LME inventories and narrowing backwardation may limit further upside.
Further price movement in dross and oxide is likely to depend on the direction of primary zinc prices, LME inventory levels and domestic demand.
Leave a Reply