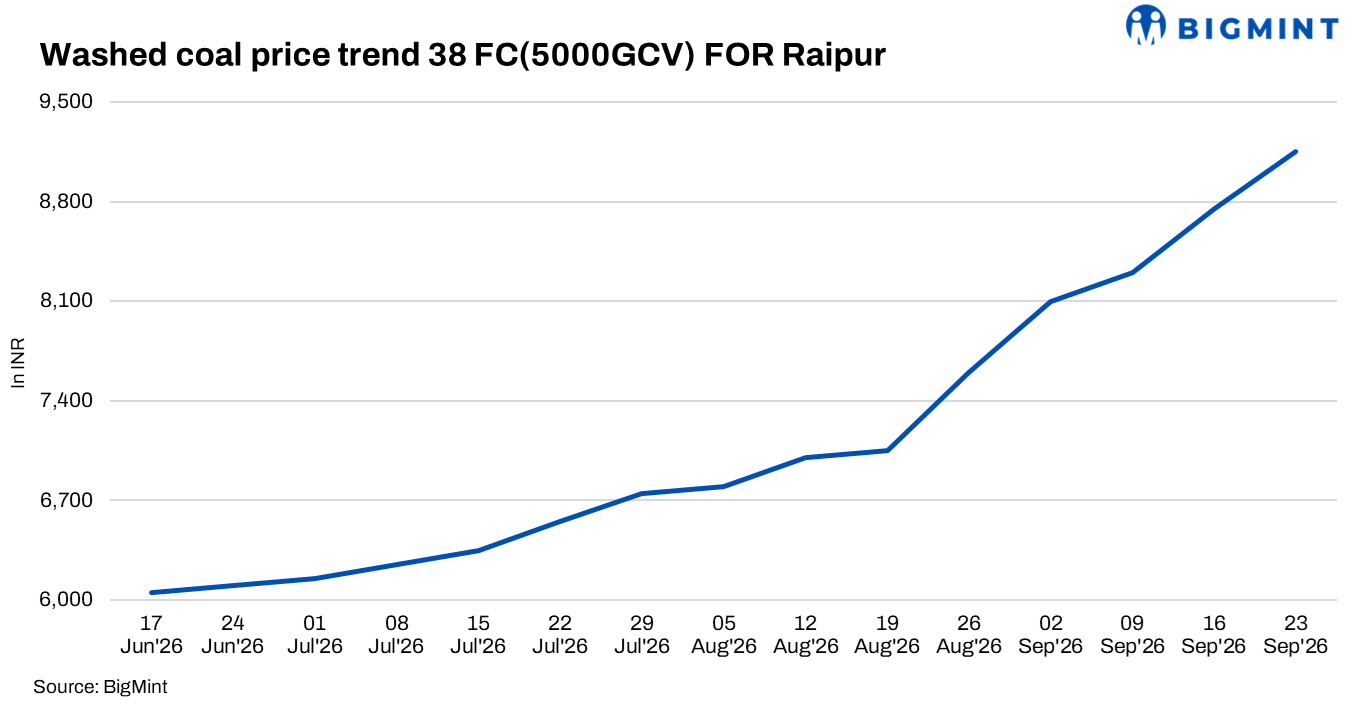
- Washed coal offers remained tight amid ROM shortage
- Sponge iron prices declined sharply on weak demand
Indian washed coal prices strengthened further in the assessment week, with 38-39% FC (5,000 GCV) washed coal FOR Raipur rising INR 400/t w-o-w to INR 9,150/t as of 23 September 2026. The increase was mainly driven by continued ROM coal shortages and limited offers. A deal was reported at INR 9,100/t FOR Raipur. Domestic coal prices also moved higher, increasing replacement costs for washeries.
ROM shortage keeps washed coal prices firm
ROM coal availability remained the key constraint for washeries in the region. Limited availability continued to restrict production and kept several sellers away from the market. Available offers remained elevated as suppliers faced difficulty in securing raw material.
Domestic coal prices also strengthened during the week. Ex-Bilaspur 4,500 GCV coal rose INR 100/t w-o-w to INR 6,500/t as of 22 September, while 5,000 GCV coal increased INR 50/t w-o-w to INR 8,100/t. Higher raw coal costs, alongside limited physical availability, kept washed coal sellers firm.
A deal was reported at INR 9,100/t FOR Raipur, indicating that buyers continued to transact only at levels below prevailing offers. However, the limited availability of washed coal prevented sellers from making significant downward adjustments.
Sponge iron prices fall on weak demand
Sponge iron prices declined sharply during the week as buying activity weakened and finished steel demand remained subdued. PDRI ex-Raipur fell INR 1,650/t w-o-w to INR 27,750/t as of 23 September.
Market sentiment turned bearish, with poor buyer participation across regions and the eastern market recording the steepest decline. Finished steel prices also fell by INR 200-700/t, adding further pressure on sponge iron prices.
Deals were largely concluded below offered levels as buyers remained reluctant to build stocks. BigMint recorded around 5,000 t of sponge iron trades, down around 1,000 t from the previous session.
Despite weaker sponge iron prices and slower downstream demand, washed coal prices remained supported by the shortage of ROM coal. Physical availability therefore continued to outweigh demand-side weakness in determining washed coal prices during the week.
Leave a Reply