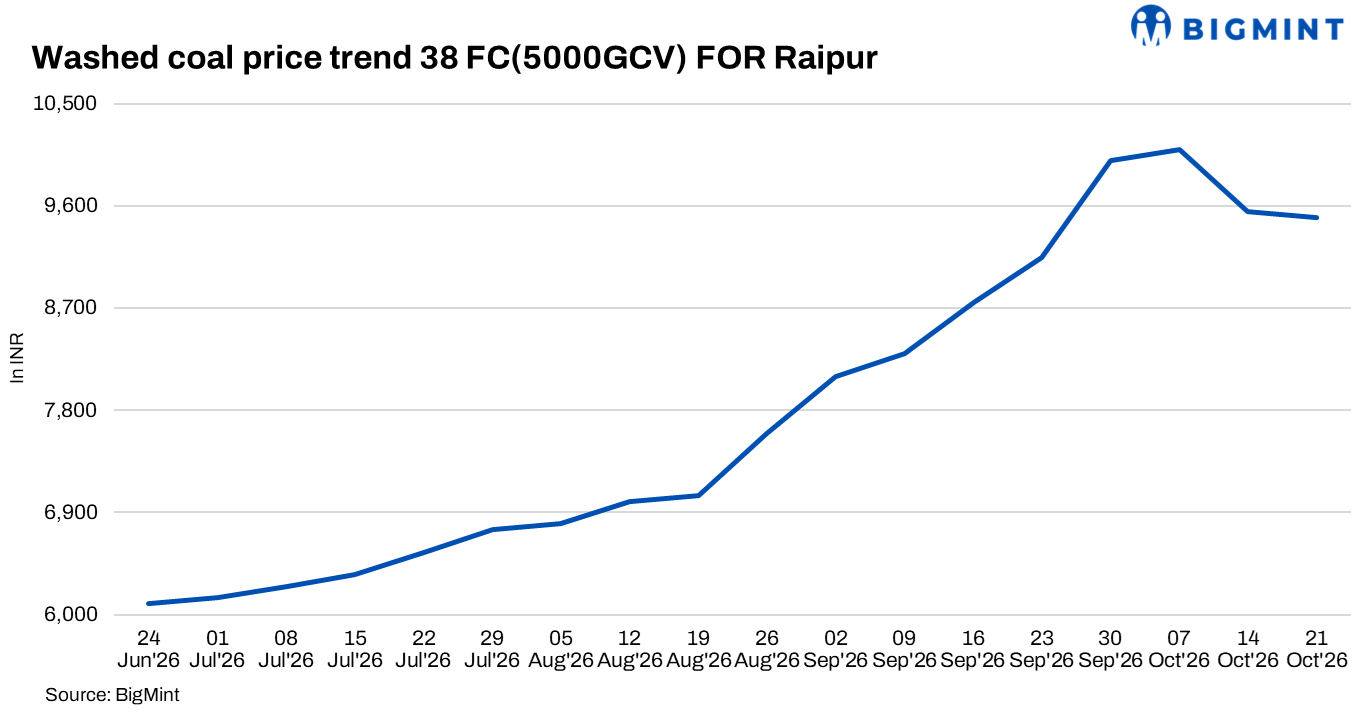
- Washed coal slips even as domestic prices stabilise
- Sponge iron prices recover but buyers stay on sidelines
Indian washed coal prices edged lower as of 21 October 2026, while domestic coal prices remained unchanged. Sponge iron prices recovered across several regions, supported by firmer market sentiment and healthy enquiries, but higher offers limited deal conversions. Trading activity remained moderate, with buyers largely restricting purchases to immediate requirements. Meanwhile, participants continued to assess the competitiveness of coal booked in earlier SECL auctions amid changing spot-market conditions.
Washed coal prices soften marginally in Raipur
BigMint assessed 38-39% FC (5,000 GCV) washed coal FOR Raipur at INR 9,500/t as of 21 October, down INR 50/t w-o-w. The marginal decline indicated that buying interest remained measured despite improving sentiment in the downstream sponge iron market.
Buyers continued to exercise caution at prevailing price levels, with limited bulk purchases reported. Sellers faced the challenge of securing larger orders as enquiries did not consistently translate into confirmed transactions.
Domestic coal prices remain stable
Ex-Bilaspur 4,500 GCV coal prices remained unchanged w-o-w at INR 6,200/t as of 21 October, while 5,000 GCV coal held at INR 8,700/t.
The stability followed the sharp declines recorded in the previous week, when prices fell by INR 800/t for 4,500 GCV coal and INR 300/t for 5,000 GCV coal. Market participants continued to weigh current spot prices against the cost of coal secured in earlier e-auctions.
The gap between auction purchase costs and prevailing market rates remained a consideration for buyers deciding whether to lift booked quantities, although the latest price stability suggested that domestic coal rates had paused their recent decline.
SECL auction activity
South Eastern Coalfields Ltd. (SECL) allocated 547,650 t of non-coking coal in its 10 October 2026 e-auction, with premiums varying considerably across mine-grade combinations. Kusmunda OC G11 recorded the highest premium at 322.7%, followed by Dhelwadih UG G8 at 270.1% and Amlai OC Annexure B G8 at 253.6%. The auction results highlighted strong bidding for selected sources despite subsequent weakness in domestic coal and washed coal prices. This divergence kept buyers cautious about lifting previously booked quantities as they assessed the competitiveness of auction purchase prices against prevailing spot-market rates.
Sponge iron prices recover across regions
Domestic sponge iron prices rose by INR 50-500/t across regions, led by eastern India, as positive sentiment and healthy enquiries supported seller offers. BigMint’s Raipur PDRI assessment, however, declined INR 150/t w-o-w to INR 28,000/t as of 21 October.
Although enquiries improved, buyers remained selective at higher price levels. Previous-session bookings and firmer sentiment encouraged sellers to raise offers, but many buyers limited procurement to immediate needs.
BigMint recorded sponge iron trade volumes of around 14,000 t on 21 October, down 2,000 t from the previous day, reflecting softer buying momentum at elevated prices. Festive holidays also kept market participation thin, with limited bulk purchasing and moderate overall trading activity.
Leave a Reply