- Buyers remain cautious amid nickel volatility
- Export activity faces freight and quota constraints
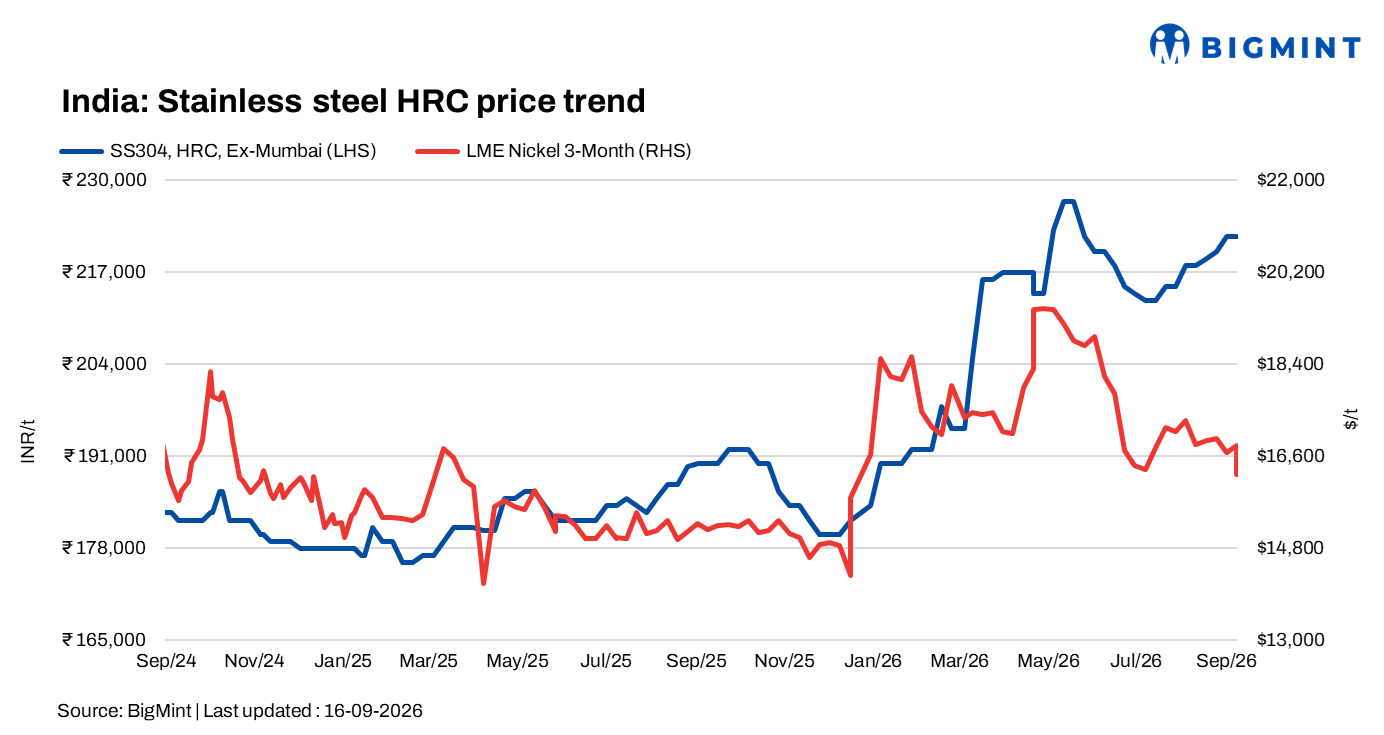
India’s stainless steel finished market remained firm during the week ended September 15, supported by tight raw material availability and elevated alloy costs. However, moderate downstream demand and volatile nickel prices kept buyers cautious, limiting broader price gains.
Finished flat
Demand for stainless steel flat products remained moderate compared with the previous week. Limited scrap availability supported 316-grade products, while 304-grade prices softened slightly.
Ferro molybdenum costs also remained firm, adding to cost pressure on 316-grade products. A leading Indian stainless steel producer raised 316L HR and CR prices by INR 3,000/t from September 12, its second price revision this month. J4 prices increased by INR 1,500/t, while 204Cu and 202-AU prices rose by INR 2,000/t.
BigMint’s benchmark assessment for 304 HR coils remained unchanged w-o-w at INR 222,000/t exw-Mumbai. 316 HR coils increased by INR 5,000/t to INR 438,000/t.
304 CRC declined by INR 1,000/t to INR 225,000/t, while 316 CRC increased by INR 10,000/t to INR 450,000/t.
Market participants reported reduced material allocation and continued raw material constraints. However, some buyers expect demand to remain subdued through the festival period.
Finished long
Finished long prices increased further amid tight scrap availability, despite relatively weak demand. Export sales also remained slow, although activity is expected to improve as European buyers return from the summer holiday period.
However, higher freight costs, EU quotas and CBAM-related costs could limit the pace of export recovery.
304 black bar prices remained unchanged w-o-w at INR 204,000/t exw-Mumbai, while 316 black bars increased by INR 4,000/t to INR 370,000/t.
304 bright bars rose by INR 3,000/t to INR 230,000/t, while 316 bright bars increased by INR 7,000/t to INR 398,000/t. 304 wire rod prices remained unchanged at INR 202,000/t, while 316 wire rod increased by INR 2,000/t to INR 365,000/t.
Export offers also strengthened slightly. On September 15, 304 bright bars were assessed at $2,380/t FOB Nhava Sheva and 316 bright bars at $4,330/t FOB Nhava Sheva, both up $10/t w-o-w.

Global market trends
Asian stainless steel prices declined for a third consecutive week as weak downstream demand outweighed production adjustments. Expectations of lower nickel and nickel pig iron costs also kept buyers cautious.
In India, stainless steel scrap imports declined 6% y-o-y to 0.67 mnt in H1 2026, while elevated landed costs continued to favour domestic procurement.
Malaysia initiated an anti-dumping investigation on September 9 covering stainless steel cold-rolled products imported from Indonesia. The preliminary determination is scheduled for January 7, 2027, with the final determination expected on May 7, 2027.
Outlook
India’s stainless steel market is expected to remain firm but demand-sensitive through September and into the upcoming festival period. Mills are evaluating alternative raw material sources, including semi-finished products and nickel pig iron, to manage elevated scrap costs.
Volatile nickel prices could encourage buyers to adopt a wait-and-watch approach, while subdued domestic demand and cautious export buying may limit further price increases unless raw material costs remain elevated.
Leave a Reply