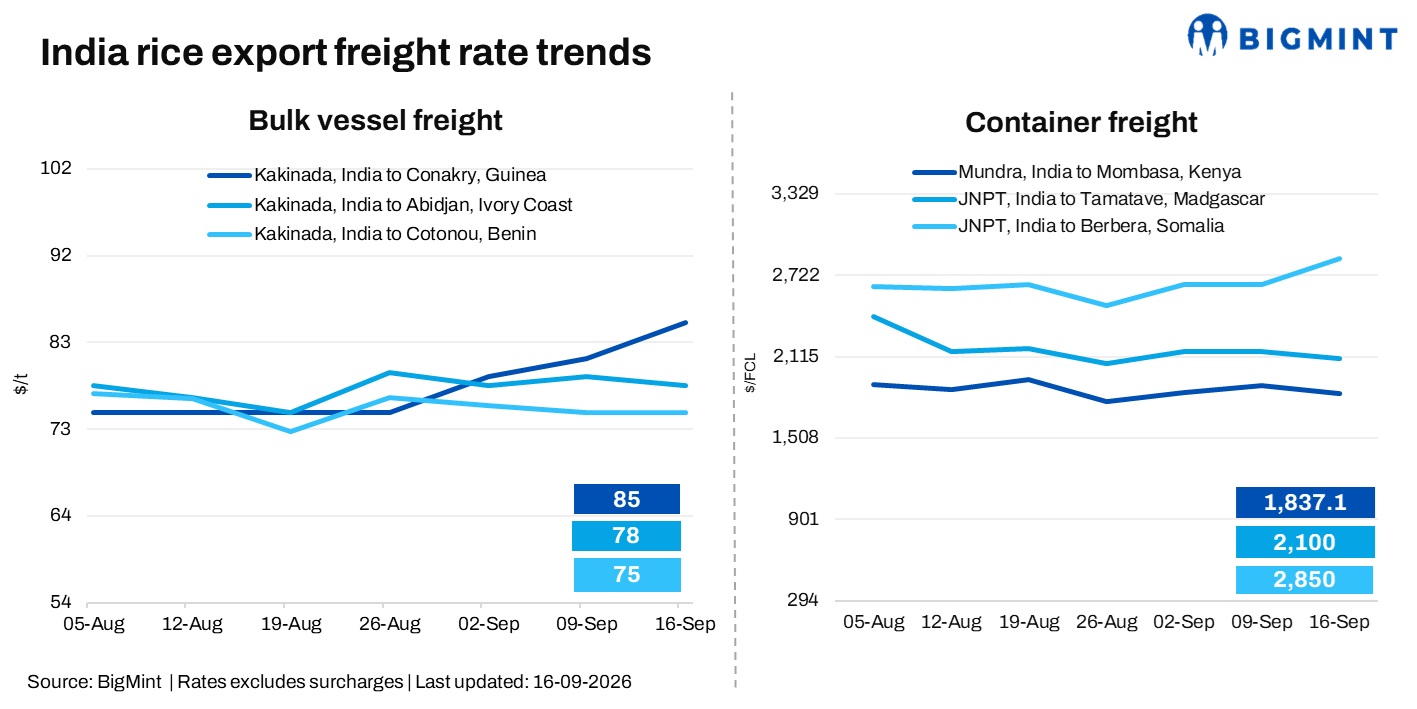
- West African bulk trade supported by congestion and tight tonnage
- Container market turns selective amid softer booking activity
India’s rice freight market remained mixed in the week ended 16 September 2026, with West African bulk trades finding support from port congestion and vessel availability, while container activity remained relatively subdued. Cautious chartering and selective spot fixing kept overall market sentiment measured.
A shipbroker told BigMint, “Bulk rice freight rates softened as fresh cargo enquiries remained limited across key routes, while containerised rice freight remained comparatively firm on steady booking activity and tighter equipment availability.”

West African bulk market remains supported
West Africa continued to be the key focus for bulk rice shipments, with congestion and vessel availability shaping freight sentiment. Conakry remained supported by persistent port congestion and tight prompt tonnage, while Abidjan saw active enquiries and fixing activity despite some easing in vessel tightness.
A shipbroker said, “Kakinada-West Africa bulk rates faced pressure amid cautious chartering activity and limited spot fixing, while higher bunker costs continued to influence owners’ freight indications despite subdued cargo demand.”
At Cotonou, forward fixing interest is building toward month-end, with firm owners’ indications keeping sentiment supported. This could provide some momentum as buyers prepare for upcoming requirements.
Container market remains selective
Container activity was comparatively subdued across key India-Africa routes. Improved container availability at Mundra helped ease some origin-side pressure, while Mombasa-side congestion and equipment constraints continued to influence market conditions.
A shipbroker said, “Monsoon-related logistics disruptions in parts of India affected cargo movement and loading schedules, while some container lines maintained rate discipline on select India-Africa routes amid relatively balanced vessel utilisation.”
Berbera remained firmer than other container destinations, supported by active fixing interest and limited carrier options.
Rice prices soften amid cautious buying
BigMint’s assessment for non-basmati parboiled rice (IR-64 5% PB), FOB Kakinada, eased to $374/tonne (t) on 16 September 2026, from $376/t in the previous week. Softer buying interest and cautious trade sentiment continued to weigh on market indications.
Outlook
The rice freight market is expected to remain selective in the near term, with West African bulk routes supported by congestion and vessel availability, while container activity remains dependent on booking flows and equipment conditions. The market remains slow amid the ongoing holiday and festive period, though fixing activity could pick up toward month-end as African buyers step up rice shipments ahead of the Christmas sales season, which may provide some support to overall market activity.
Leave a Reply