- IOCL raises prices by up to INR 2,500/t across refineries
- Nayara, MRPL implement sharp m-o-m hikes of around INR 2,000/t
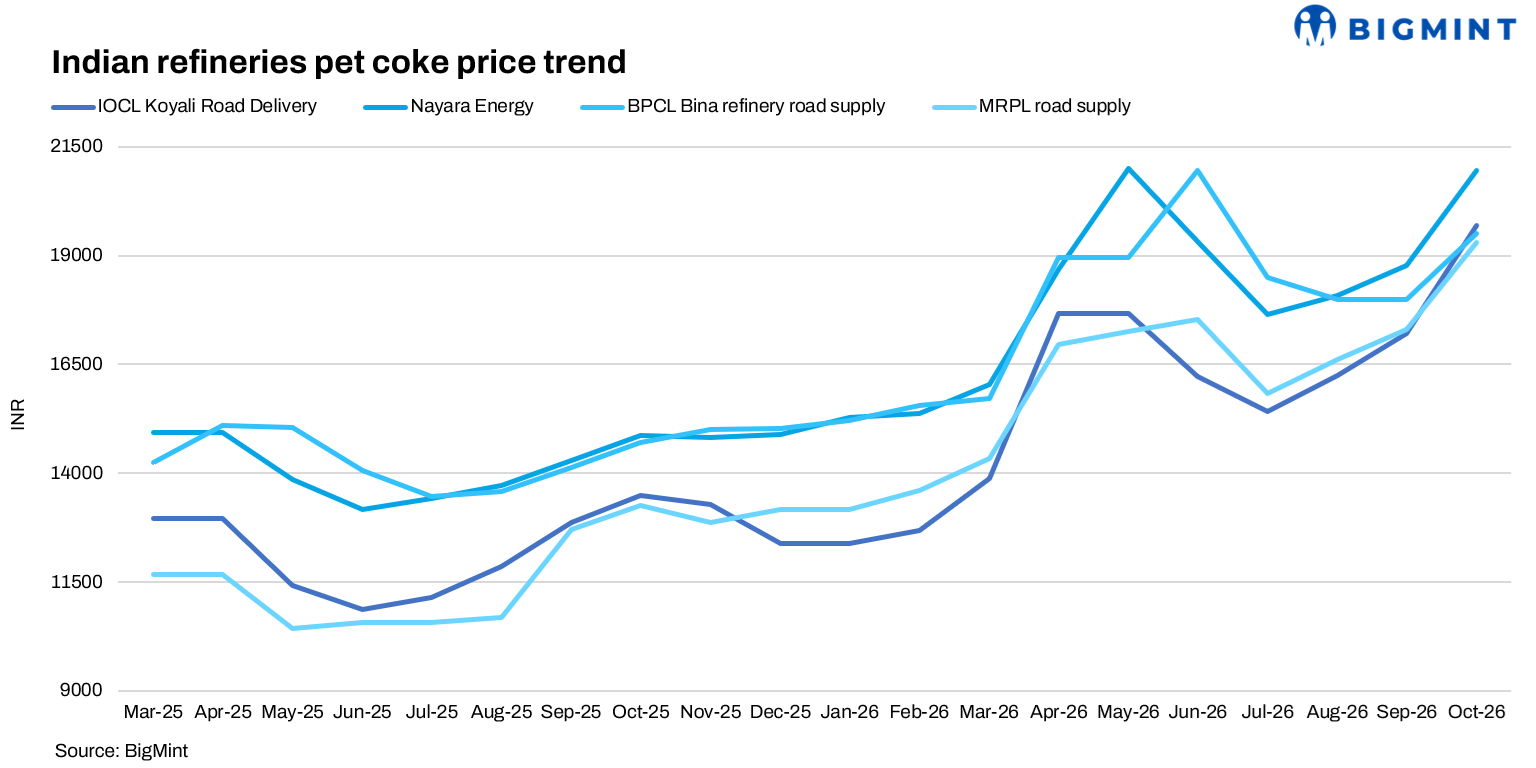
India’s domestic petcoke market witnessed a sharp price increase in October, with IOCL, Nayara Energy, MRPL and BPCL revising prices upwards. IOCL raised prices by INR 2,490-2,500/t across its refineries, while Nayara Energy increased prices by INR 2,180/t. MRPL also raised road and rake prices by INR 2,000/t, and BPCL increased prices by INR 1,500/t at Bina and Kochi.
The consecutive monthly increases reflected firmer international replacement costs amid geopolitical uncertainty, elevated freight, and marine insurance expenses. Domestic prices also remained significantly above year-ago levels, while refinery-specific supply conditions continued to influence regional price differentials.
IOCL records steepest monthly increase
Indian Oil Corporation (IOCL), the second-largest petcoke producer and a leading domestic seller, revised its prices effective 7 October, raising road prices by INR 2,490-2,500/t across its four refineries.
Road prices increased to INR 19,700/t at Koyali, INR 20,970/t at Panipat, INR 18,720/t at Paradip and INR 18,840/t at Haldia. The increases represent approximately 11.9-13.4% m-o-m.
Rake prices were INR 200/t below road prices at Koyali, Paradip and Haldia, while Panipat has no rake-loading facility. At Panipat, prices applicable to northern states and general customers remained aligned.
The October revision followed an INR 970/t increase in September, marking two consecutive months of rising prices after reductions in earlier months. The latest increase was also higher than Nayara Energy’s INR 2,180/t revision.
Firm international replacement costs, elevated freights, and marine insurance expenses amid continuing geopolitical uncertainty supported the domestic price increase.
IOCL-Nayara price differential narrows further
IOCL’s prices remained below Nayara Energy’s at Koyali, Paradip and Haldia, while Panipat moved marginally above Nayara in October.
At Koyali, IOCL’s price was INR 1,260/t below Nayara’s, compared with INR 1,570/t in September. At Panipat, IOCL’s price stood INR 10/t higher than Nayara’s, reversing the INR 310/t discount recorded in September.
The differential at Paradip narrowed to INR 2,240/t from INR 2,560/t in September, while Haldia’s gap reduced to INR 2,120/t from INR 2,440/t in September.
Paradip continued to record the widest discount among the comparable IOCL locations. Its current differential remained below the maximum INR 4,070/t discount recorded in June 2026. Regional supply-demand conditions and marketing dynamics continued to influence these differences.
MRPL prices rise following refinery restart
MRPL increased its petcoke prices by INR 2,000/t for both rake and road supplies effective 1 October. The rake price rose to INR 17,370/t, including INR 70/t in tarpaulin charges, while the road price increased to INR 19,300/t.
The revision represents a 13.0% m-o-m increase. Compared with October 2025, the road price is 46.7% higher than the year-ago level of INR 11,840/t.
The increase followed a INR 680/t revision in September, broadly matching Nayara Energy’s earlier INR 690/t increase. MRPL’s refinery, which had undergone a maintenance shutdown from mid-August, resumed operations in mid-September.
The differential between road and rake supplies remained INR 2,000/t, excluding tarpaulin charges, compared with INR 1,500/t until March 2026. Most MRPL petcoke supplies continued to move by rail.
MRPL’s rake price was INR 3,590/t below Nayara’s October price of INR 20,960/t, compared with an INR 3,410/t gap in September. Its road price remained INR 1,660/t lower, equivalent to an 8.0% discount.
Nayara Energy raises prices for third consecutive month
Nayara Energy increased its petcoke price by INR 2,180/t to INR 20,960/t effective 1 October, representing an 11.6% m-o-m increase.
The revision followed increases of INR 440/t in August and INR 690/t in September. The October price is 41.0% above the corresponding year-ago level of INR 14,870/t, returning close to the INR 21,000/t level recorded in April 2026.
Petcoke prices had declined sharply in June and July before recovering over the following three months. The latest increase reflected renewed uncertainty in international markets, with freight and marine insurance costs remaining elevated amid concerns over vessel movements through the Strait of Hormuz.
Nayara continued to command a premium in its regional market. Reliance Industries (RIL) no longer releases petcoke into the merchant market, as its production is consumed in its gasification unit. The reduced local availability supports Nayara’s position as a key price reference.
BPCL raises prices at Bina and Kochi
BPCL increased petcoke prices by INR 1,500/t at both its producing refineries effective 1 October.
At Bina, road and rake prices rose to INR 19,500/t, while Kochi’s rail price also increased to INR 19,500/t. Kochi has no road supply. The revision represents an 8.3% m-o-m increase at both refineries.
Compared with October 2025, Bina’s price was 32% higher, while Kochi’s price had increased by 55.4%. Both refineries recorded the same price for the third consecutive month.
Bina’s available petcoke volume is estimated at around 20,000-25,000 t/month, with a significant share consumed by its captive power plant. Kochi’s availability is higher at approximately 75,000-80,000 t/month.
Both BPCL prices remained INR 1,460/t below Nayara’s October price, widening the difference from INR 780/t in September. The equal pricing at Bina and Kochi also continued to differ from their earlier pattern, when Bina and Kochi prices often varied due to refinery-specific marketing and supply conditions.
Overall, October witnessed broad-based increases across India’s major domestic petcoke suppliers. IOCL recorded the sharpest absolute monthly revision, followed by Nayara and MRPL, while BPCL implemented a comparatively smaller increase. International replacement costs, freight and insurance expenses remained key influences on domestic pricing, alongside differences in refinery availability and regional market conditions.
Leave a Reply