- Indonesian coal prices firm on tight availability
- Stock drawdown supports imported coal demand
Portside prices of Indonesian thermal coal in India remained stable w-o-w for the week ended 18 September 2026, as tight availability and higher replacement costs provided underlying support, while elevated prices continued to limit fresh buying and spot-market activity.
High prices levels keep buyers on the sidelines
Indonesian 5,000 GAR prices remained unchanged at around INR 11,900/t at Kandla and INR 11,800/t at Vizag. Similarly, 4,200 GAR prices held steady at around INR 10,000/t at Kandla and INR 9,900/t at Vizag, while 3,400 GAR prices at Navlakhi remained stable at around INR 8,000/t.
Market participants described spot activity as largely flat, with no significant fresh deals reported and purchases restricted mainly to immediate requirements. Although the recent price rally has paused, elevated price levels continue to discourage aggressive procurement. Lower daily material lifting also indicates cautious inventory management and subdued spot demand, preventing further price increases despite firm supply-side fundamentals.
Port inventories decline on continued cargo evacuation
India’s thermal coal inventories at major ports declined 3% w-o-w to 13.08 mnt in week 37, from 13.48 mnt in week 36. The drawdown was primarily driven by continued cargo evacuation at Kandla, Magdalla, Krishnapatnam and Dahej. Higher inventories at Karaikal, Gopalpur and Gangavaram partly offset the overall decline.
Despite lower port stocks, buying interest remained measured as Indonesian and South African coal prices strengthened amid tighter availability and higher replacement costs. Consequently, buyers continued to prioritise essential requirements rather than build substantial inventories at prevailing price levels.
Power plant stock drawdown supports prices
Fundamentals remained supportive on the domestic power-generation side, with thermal coal stocks at power plants declining around 9% w-o-w to 23.4 mnt as of 17 September, equivalent to only around seven days of consumption. Nearly 72 power plants were reporting critical inventory levels.
The continued drawdown in power-sector inventories provides a supportive floor for imported thermal coal demand, particularly if domestic coal replenishment remains insufficient. However, the absence of aggressive restocking suggests that low inventories have not yet translated into a broad-based surge in spot procurement.
Indonesian benchmarks show mixed movement
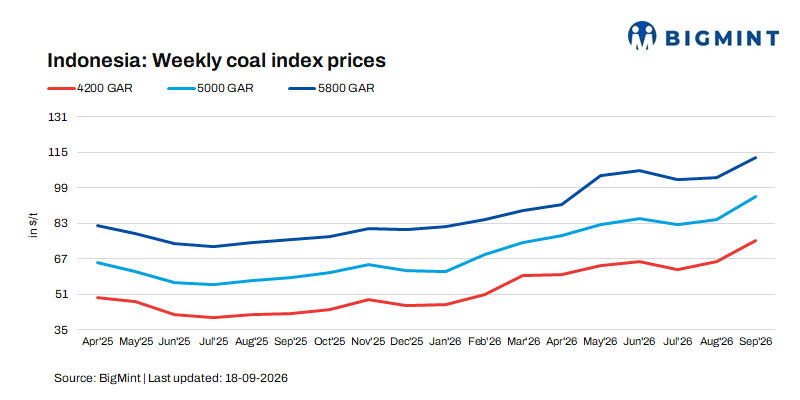
The Indonesian export market remained mixed during the week. 4,200 GAR FOB prices declined by around $1-2/t, while 3,400 GAR prices increased by around $0.5-1/t. Meanwhile, 5,800 GAR prices remained broadly stable. The divergent movement across grades indicates that while supply constraints continue to support selected products, subdued spot demand is limiting a broad-based price rally.
Outlook
The near-term outlook for Indian portside Indonesian thermal coal prices is stable-to-firm, with tight availability, declining power plant inventories and elevated replacement costs expected to provide continued support. However, need-based buying, low spot-market activity and reduced daily lifting are likely to restrict significant upside in the immediate term.
Leave a Reply