- Tight availability, strong international demand keep prices firm
- Domestic coal demand improves as imports remain expensive
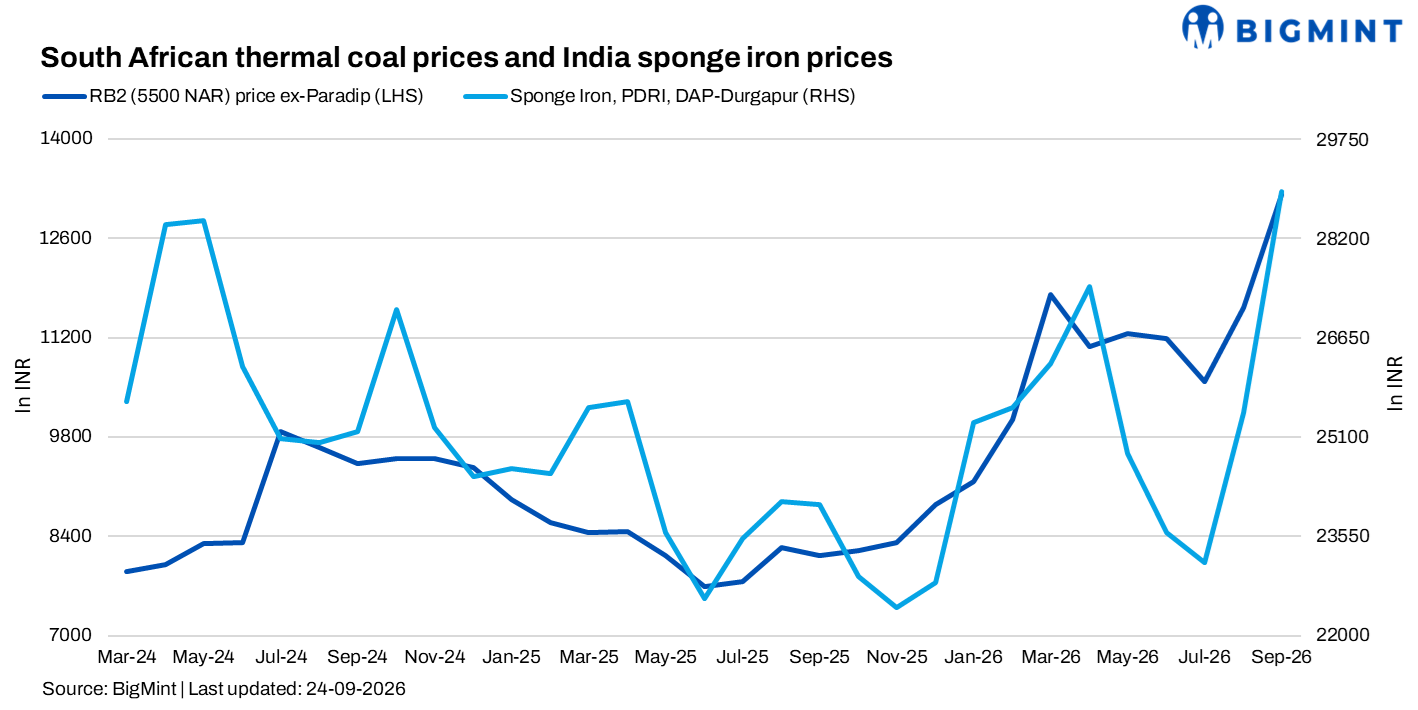
South African non-coking coal prices at Indian ports remained firm during the week ended 24 September 2026 despite slower market activity and lower bids. Ex-Paradip RB2 (5,500 NAR) increased by INR 200/t w-o-w to INR 13,500/t, although it declined INR 100/t d-o-d. RB3 fell INR 100/t w-o-w to INR 11,500/t. Ex-Vizag, RB2 rose INR 150/t w-o-w to INR 13,400/t, while RB3 declined INR 50/t to INR 11,500/t. High imported coal offers and weaker sponge iron demand reduced fresh buying interest, though limited cargo availability and steady overseas demand supported prices.
High import offers slow fresh buying
South African cargo offers remained elevated, with 5,500 NAR offered at $106-110/t FOB Richards Bay Coal Terminal (RBCT) for October shipment against bids of $102-104/t. CFR India offers were around $129-130/t, while buyers targeted around $126/t. Traders reportedly faced difficulty placing some October cargoes booked earlier as buyers resisted current replacement costs.
Demand from Bangladesh remained active for lower-CV South African coal. A Bangladeshi importer was seeking 4,800 NAR for October delivery at around $119/t CFR, against counteroffers of $124-125/t. Several November 4,800 NAR cargoes were also sold at $91-93/t FOB RBCT, showing that overseas demand continued to provide support even as Indian buying slowed.
In India, a deal for around 15,000 t of RB2 was reported at INR 13,550/t CNF east coast India. Offers for similar material were heard around $131/t.
Domestic coal gains interest amid supply concerns
Domestic coal enquiries from sponge iron and cement producers had improved as imported coal offers became less attractive. Domestic coal prices also remained firm, with Ex-Bilaspur 4,500 GCV coal rising INR 100/t w-o-w to INR 6,500/t and 5,000 GCV coal increasing INR 50/t to INR 8,100/t as of 22 September.
Recent domestic coal auctions also attracted record-high premiums for selected grades, increasing procurement costs and encouraging consumers to assess domestic material more actively.
Sponge iron prices fall on weak downstream demand
Sponge iron PDRI ex-Durgapur dropped INR 2,050/t w-o-w to INR 27,550/t. Market sentiment turned bearish as finished steel demand remained weak and buyer participation stayed limited. Sellers reduced offers, but buyers remained reluctant to accept even revised levels. Deals were mainly concluded at discounted levels, with purchases emerging only at lower prices. Trade activity also remained subdued, indicating cautious sentiment and limited restocking interest. Further weakness was likely to depend on any recovery in finished steel demand.
Port stocks decline, weather disrupts east coast movement
Coal inventories at major Indian ports declined 2.05% w-o-w to 18.72 mnt during 13-19 September from 19.11 mnt in Week 37. Non-coking coal stocks fell 3.05% to 12.68 mnt. On the east coast, cyclone-related continuous rainfall affected normal coal handling activity. Loading continued at some locations, but weather conditions disrupted loading and unloading schedules and created uncertainty around vessel and cargo movement.
Despite lower port stocks, buying interest for South African coal remained selective as imported offers stayed high. Buyers increasingly compared imported replacement costs with domestic coal availability before committing to fresh cargoes.
Market sentiment turns more cautious
Market activity slowed towards the end of the assessment week, with bids for South African coal weakening as buyers resisted high offers. Suppliers also began reducing offers in response to softer finished steel and sponge iron markets.
South African coal prices remained supported by limited cargo availability and steady overseas demand, particularly from Bangladesh and other markets. However, weaker Indian downstream demand, high replacement costs and cautious buying could limit further upside in the near term.
Leave a Reply