- Port stocks rise 0.38 mnt to 19.06 mnt
- Mundra and Mangalore drive thermal replenishment
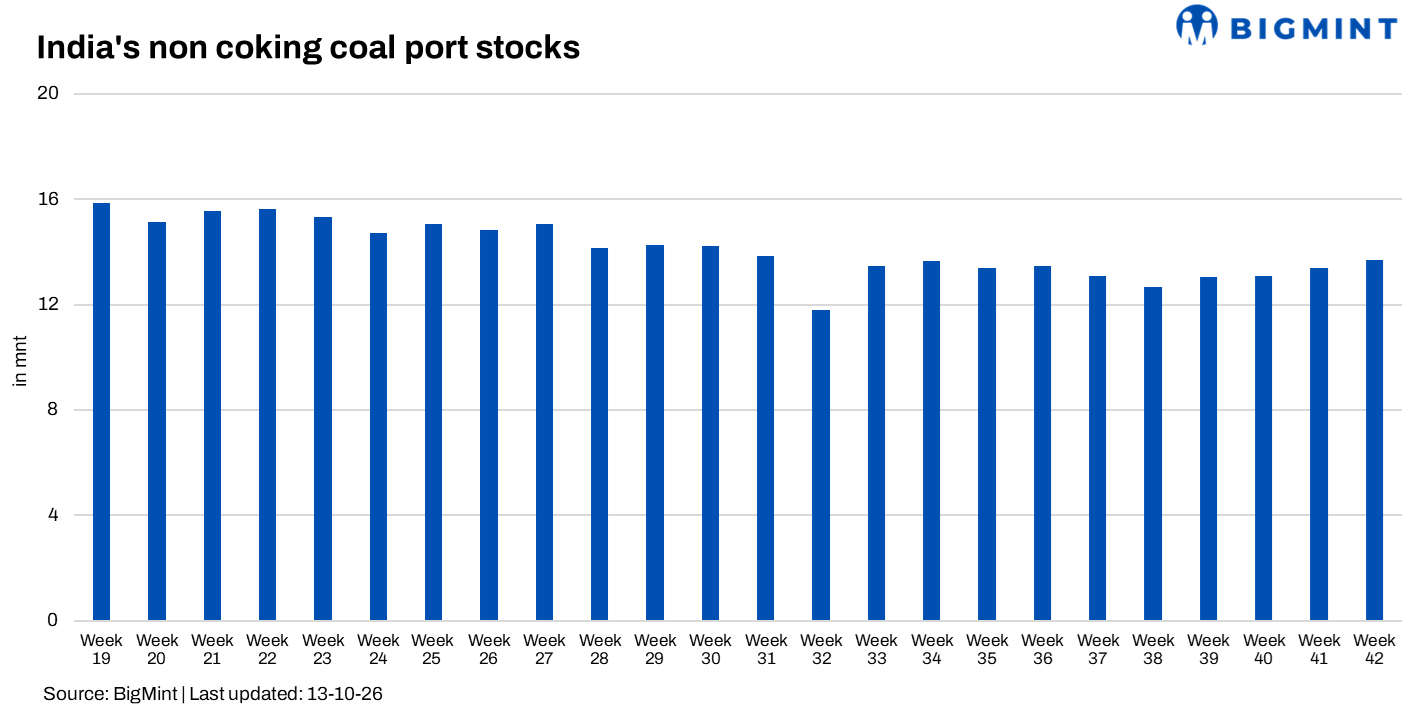
Coal inventories at Indian ports covered by BigMint’s Week 42 assessment increased by 0.38 mnt, or 2%, to 19.06 mnt during 11–17 October 2026.
Non-coking stocks rose 2.2% to 13.69 mnt, while coking coal inventories recovered 1.6% to 5.37 mnt.
However, the headline increase masks an uneven supply position. Mundra and Mangalore accounted for much of the thermal replenishment, while Kandla, Navlakhi, Tuna and Krishnapatnam continued drawing down stocks.
For industrial buyers, therefore, higher national inventories do not automatically translate into greater availability at their usual supply ports.
Stock growth remains concentrated

Quantity in mnt. Selected ports shown; category totals include all covered locations. Changes calculated from unrounded figures. Data are provisional and exclude some Indian ports.
Mundra reverses previous week’s drawdown
Mundra’s total inventories increased 8.7% to 2.51 mnt, reversing the previous week’s decline.
Non-coking stocks rose by approximately 0.19 mnt to 2.39 mnt. CGPL/Tata holdings increased by 0.12 mnt to 0.85 mnt, while Adani Power added approximately 0.06 mnt to reach 0.61 mnt. Adani Enterprises stocks increased modestly to 0.93 mnt.
The two power-company holdings accounted for most of Mundra’s thermal build. This improves their identified coastal fuel buffer, but should not be interpreted as equivalent additional supply available to independent buyers.
Mundra and Mangalore together added approximately 0.35 mnt of non-coking stocks, more than the national category’s net increase of 0.30 mnt. Excluding these two ports, combined thermal inventories declined slightly.
Replenishment was therefore less broadly distributed than the headline increase suggests.
Mangalore strengthens as western industrial hubs tighten
Mangalore’s stocks increased 21.4% to 0.93 mnt. JSW Steel holdings rose by approximately 0.12 mnt to 0.44 mnt, accounting for around 70% of the port’s increase.
Elsewhere on the western coast, the picture was less comfortable.
Kandla stocks fell 12.9% to 0.59 mnt, following the previous week’s 12.3% decline. Inventories have consequently fallen approximately 24% from their 3 October level.
UltraTech Cement’s Kandla holdings declined by around 43,000 t to 244,151 t. Balaji and Agarwal Coal also recorded substantial reductions, partly offset by a new reported holding of 53,864 t at GRM Resource.
Navlakhi stocks fell 9.4% to 0.65 mnt. Aditya Birla increased its holdings, but reductions across several other receivers outweighed that build.
Tuna recorded a sharper 23.1% decline to 0.12 mnt. Wonder Cement stocks fell to approximately 46,000 t, while Welspun and other holders also drew down inventories.
These reductions matter for cement and other industrial consumers assessing nearby supply. However, stock movements alone cannot establish whether stronger consumption, fewer arrivals or reporting changes caused the decline.
Hazira and Dahej add stocks; Magdalla remains mixed
Hazira inventories increased 2.2% to 2.27 mnt, with ArcelorMittal and Adani Enterprises each holding approximately 1.14 mnt.
Dahej rose 3.1% to 1.02 mnt. Hindalco’s holdings increased to approximately 60,000 t, while Adani Enterprises remained the dominant stockholder.
Magdalla declined marginally to 0.81 mnt. Increases at some receivers offset much of the reduction elsewhere, illustrating why a broadly stable port total can conceal significant changes in individual availability.
Dhamra drives recovery in coking stocks
National coking inventories recovered by approximately 83,000 t, reversing the previous week’s decline.
Dhamra was the principal driver, adding approximately 0.16 mnt to reach 1.05 mnt. Tata Steel holdings increased by around 90,000 t, while SAIL and Shyam Group also replenished.
Without Dhamra’s increase, combined coking stocks at the other covered ports would have declined by approximately 80,000 t.
Paradip’s coking inventories fell 10.7% to 1.21 mnt, with reductions across SAIL, Visa Minmetal, Rawmet Resources and Jindal Steel & Power. A 51,000-t increase in non-coking stocks only partly offset the decline.
Vizag’s coking total remained virtually unchanged at 1.09 mnt, although lower SAIL holdings were offset elsewhere. Haldia replenished, while Gangavaram declined.
Southern ports show divergent fuel movements
Krishnapatnam’s total inventories fell 10.4% to 0.99 mnt. Non-coking stocks declined approximately 0.14 mnt, outweighing a smaller recovery in coking holdings.
Tuticorin stocks fell 11.1% to 0.57 mnt, largely reflecting Moxie Power Generation’s reduction from 113,500 t to 32,050 t. NTPL holdings remained unchanged at 370,000 t.
Conversely, Karaikal stocks increased to 0.26 mnt, including a rise in TANGEDCO holdings.
BigMint assessment
Week 42 brings a larger coastal stock buffer, but replenishment remains concentrated by port, fuel and receiver.
Power-company holdings at Mundra and steel-linked stocks at Mangalore strengthen identified consumers’ positions. They offer less reassurance to buyers dependent on Kandla, Navlakhi or Tuna, where inventories declined.
The expanding import pipeline could replenish these locations, but the latest vessel records end before the stock-assessment closing date. A precise weekly evacuation calculation would therefore require aligned receipt data.
For buyers facing elevated replacement costs, suitable coal at the relevant port remains more important than the national inventory total.
Source: BigMint Week 42 port-stock assessment and receiver-level data, based on InterOcean information.
Leave a Reply