- Met coke prices rise 16% m-o-m
- Tight supply supports higher producer offers
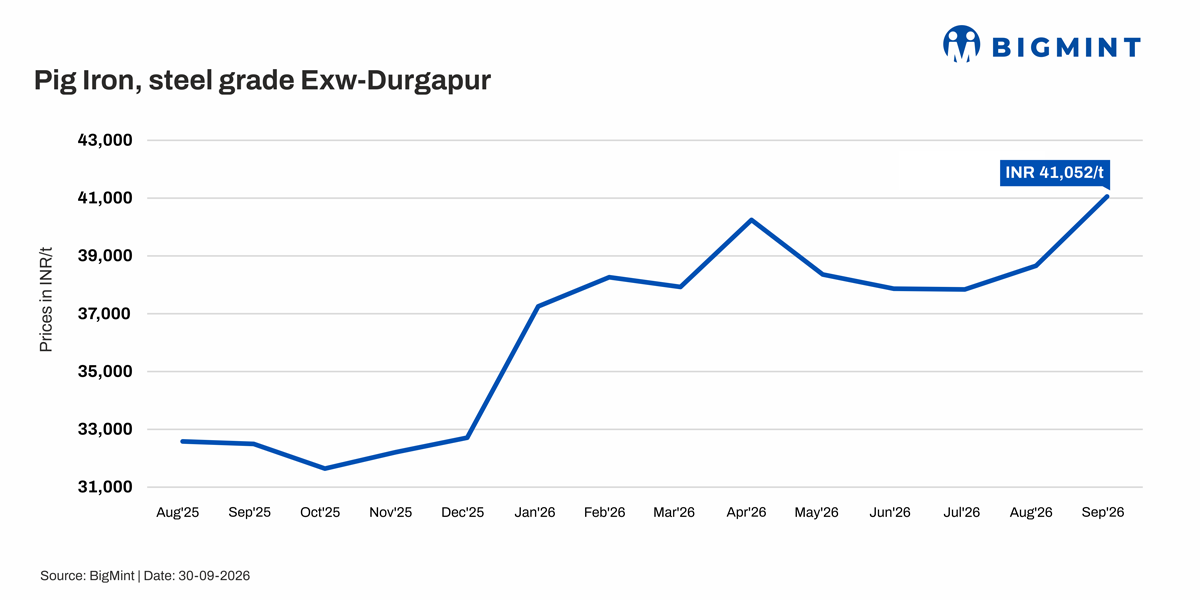
India’s pig iron market strengthened in September 2026 as record export volumes, tighter domestic availability and higher input costs supported prices. Durgapur steel-grade pig iron averaged INR 41,052/t, up INR 2,392/t m-o-m. Prices increased from INR 39,850/t on 1 September to INR 42,100/t by 30 September.
Exports tighten domestic availability
India’s pig iron exports reached around 1.73 mnt during January-September 2026, with September exports rising to around 420,000 t from 310,000 t in August. Strong export realisations, particularly in the US market, encouraged producers to prioritise overseas shipments. Export sales offered an estimated INR 1,000/t premium over domestic realisations, increasing the opportunity cost of domestic sales.
Eastern India’s pig iron production is estimated at around 12,000-15,000 t/day under normal conditions. Maintenance shutdowns and lower domestic offerings reduced available supply by around 3,000-4,000 t/day, further tightening the spot market.
Higher input costs support prices
Met coke prices increased by around 16%, or INR 5,650/t m-o-m, to an average INR 41,500/t in September. The latest assessment reached INR 42,000/t on 30 September. Higher met coke and coking coal costs raised production costs and supported firmer producer offers.

Alternative metallics also strengthened, with HMS 80:20 scrap at Mandi Gobindgarh averaging INR 38,842/t in September, up around INR 2,400/t m-o-m, while Durgapur sponge iron prices increased around 13% to INR 28,869/t. Durgapur billet prices rose around INR 4,000/t to INR 44,000/t. Lower ferrous scrap imports further constrained alternative metallic availability, supporting pig iron demand.
Auction activity strengthens
Pig iron auction activity strengthened during September as higher finished-steel prices, rising input costs and tighter availability supported bidding levels. NMDC conducted three auctions, offering 27,000 t and selling 13,900 t, while SAIL-RSP sold its entire 2,000 t offering.

Auction bids increased from around INR 38,500/t in early September to INR 41,900/t by mid-month, reaching a nearly three-year high. However, higher prices limited absorption in some NMDC auctions, indicating continued buyer caution at elevated levels.
Regional market sentiment
Eastern India: Pig iron prices increased by around INR 2,392/t m-o-m, supported by higher raw material costs, strong export bookings and maintenance-related supply constraints. Delivery and dispatch issues further restricted availability. Buying remained moderate as several buyers had already secured material, while sellers maintained firm offers on steady export demand.

Raipur: Pig iron prices increased by around INR 2,750/t m-o-m to INR 42,750/t DAP Raipur. Higher coal scarcity, tighter government allocations and rising met coke and coking coal costs lifted production costs. However, buying remained cautious as scrap and sponge iron were cheaper by around INR 2,500–8,000/t. Improving export enquiries reduced sellers’ need to discount domestic offers.
Northern India: Ludhiana steel-grade pig iron prices increased to INR 42,864/t for below 1% silica from INR 41,073/t and to INR 43,863/t for above 1% silica from INR 42,442/t. Foundry grade eased marginally to INR 47,050/t from INR 47,250/t. Buying remained need-based and improved during stronger finished-steel demand, but slowed towards month-end as downstream demand softened. Eastern India remained a key supply source, with dispatches largely smooth.
Outlook
Pig iron prices are expected to remain firm in October, supported by export demand, tight domestic availability and elevated met coke and coking coal costs. Higher scrap and sponge iron prices could provide additional support. However, increased scrap imports, slower export bookings or weaker finished-steel demand could ease supply pressure and increase buyer resistance at elevated price levels.
Leave a Reply