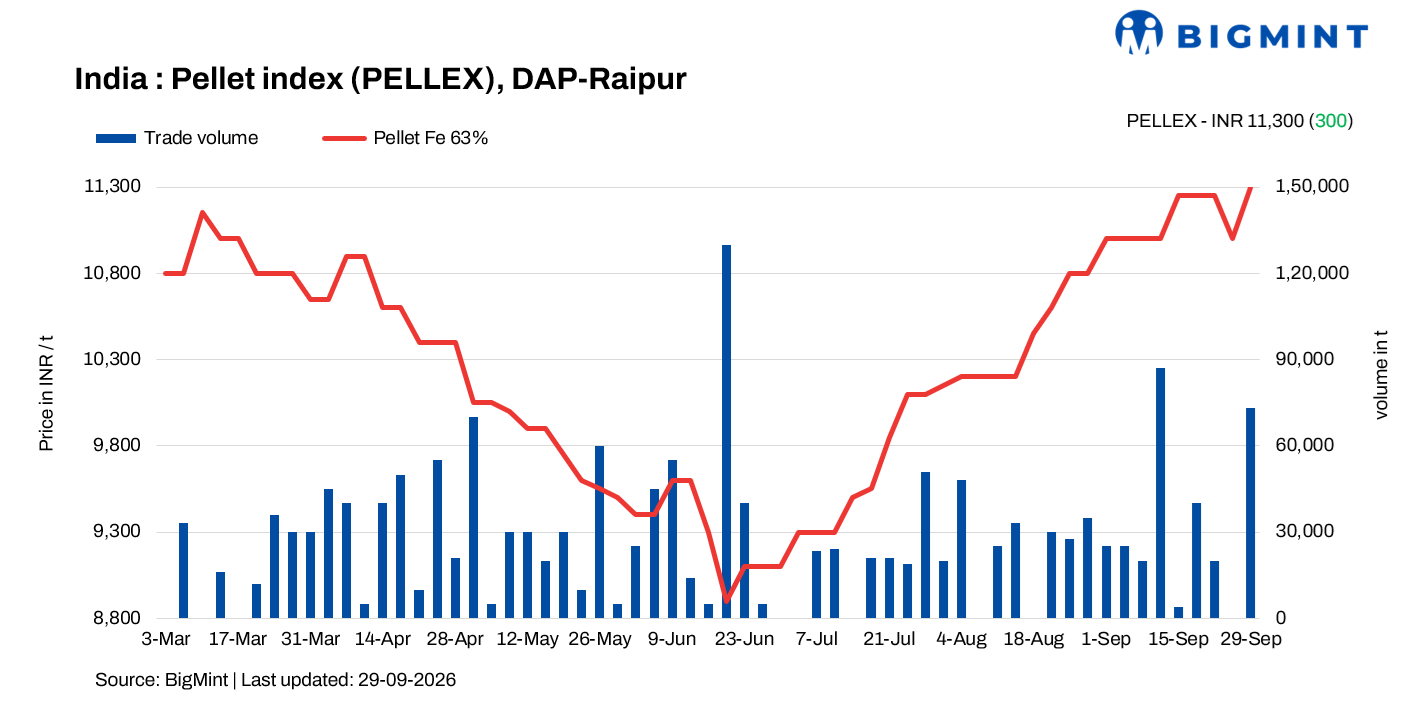
- Raipur pellet prices rebound INR 300/t amid improved bookings
- Tight spot availability supports firm seller offers
PELLEX, BigMint’s bi-weekly domestic pellet (Fe 63% +/- 0.5%) index for Raipur registered an uptick of INR 300/tonne (t) ($3/t) to INR 11,300/t ($118/t) DAP Raipur on 29 September 2026 against 25 September, hitting over four-year high. This level was last seen on April 2022.
Raipur pellet prices rebounded following improved buying interest after the recent correction, with market participants reporting bookings of around 70,000-80,000 t during the lower-price window. Tight spot availability due to maintenance-related production disruptions and limited seller availability further supported the recovery, while firm iron ore lump costs continued to underpin pellet prices.
Rationale
- PELLEX has been derived using data points, i.e., trades, offers, and bids. To download the detailed methodology, click here.
- Five (5) deals were recorded in this publishing window of which none were taken for calculation. Thus, the T1 trade category was accorded a weightage of 0%.
- Fifteen (15) firm offers, bids, and indicative prices were heard, of which nine (9) were taken for price calculation and given the balance 100% weightage.
Price movements and offers
Active pellet manufacturers in Chhattisgarh revised their offers for Fe 62.5/63% (+/-0.5%) grade pellets on an incremental tone by around INR 300/t ($3/t) to INR 11,100-11,200/t ($116-117/t) exw Raipur amid relatively tight availability in the market. Sellers maintained firm offers after receiving improved bookings at the lower price levels.
Around five major pellet deals for Fe 63% (+/-0.5%) grade were reported during the assessment period, involving approximately 73,000 t of pellets. Most of the material was booked at the prevailing lower levels following the recent correction. With order books subsequently strengthened, sellers raised their offers and became less willing to negotiate on fresh volumes.
Several pellet plants in and around Raipur continued to operate below normal production levels due to maintenance-related shutdowns. In addition, some Raipur-based sellers had kept their sales closed in recent weeks, further restricting spot availability. This provided sellers with greater pricing flexibility as buyers returned to the market.
Market scenario
Market participants said buying interest improved following the recent correction in pellet prices, which provided some relief to buyers that had largely adopted a need-based procurement approach amid elevated prices.
A Raipur-based buyer told BigMint that the correction encouraged buyers to replenish material, particularly as concerns over limited availability persisted. Around 70,000-80,000 t of pellets were reportedly booked during the lower-price window, indicating improved procurement interest at lower levels.
At the same time, spot availability remained relatively tight. Maintenance shutdowns at several pellet plants reduced production, while some sellers had limited or closed sales. The combination of improved buying interest and restricted availability allowed sellers to regain pricing power.
Raw material costs also continued to support pellet prices. Iron ore lumps remained expensive, keeping production economics firm and limiting the scope for sustained downward movement in offers. Sellers were therefore reluctant to reduce prices significantly despite buyers remaining price-sensitive.
Several Raipur-based sellers said their order books had improved following the recent bookings. Some had largely filled their immediate requirements, while others had closed sales for the early part of the week, reducing fresh availability and encouraging higher offers.
The improvement was also visible across neighbouring markets, where pellet prices increased by around INR 50-300/t in recent days. A mild recovery in billet and sponge iron prices provided additional support to the broader steelmaking raw-material complex.

Key market drivers
- Sponge iron prices increase w-o-w: Sponge PDRI prices stood at INR 29,300/t ($ 306/t) exw Raipur, gaining by INR 1,200/t ($13/t) w-o-w on 29 September against 22 September. The increase was mainly driven by higher raw material costs, especially coal, while tight coal availability kept prices on the higher side. Although sponge iron demand remained slow, rising input costs and improved momentum in finished steel pushed prices up. However, buyers largely stayed on the sidelines and resisted higher offers, leading to need-based purchases only.
- Billet prices inch higher w-o-w: BigMint’s billet index in Raipur fell by INR 1,250/t ($13/t) w-o-w to INR 45,250/t ($460/t) exw on 29 September 2026 against 22 September. Market participants adopted a wait-and-watch approach amid weak sentiment and limited fresh enquiries. Market activity remained subdued across key regions, with lower buyer participation and fewer enquiries. Weak downstream demand weighed on market momentum, while cautious buying kept spot activity limited despite the marginal increase in billet prices.
Outlook
Raipur pellet prices are expected to remain firm in the near term, supported by tight spot availability, improved bookings and elevated iron ore lump costs. Sellers are likely to hold offers firm after replenishing order books at lower levels. However, with prices at a more than four-year high, buyer resistance could limit further gains. The market will closely track downstream steel prices and the pace of supply normalisation.
Leave a Reply