- OMC iron ore auction records strong participation
- Maintenance shutdowns, high input costs limit price correction
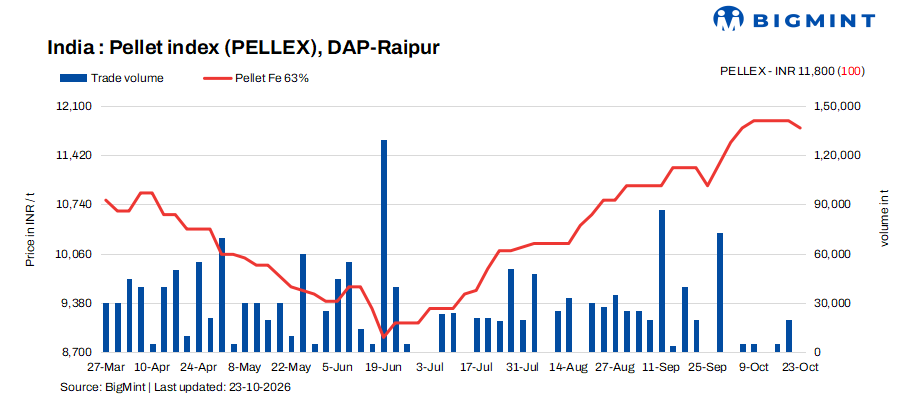
PELLEX, BigMint’s bi-weekly domestic pellet (Fe 63% ± 0.5%) index for Raipur, declined by INR 100/t ($1/t) to INR 11,800/t ($124/t) DAP Raipur on 23 October 2026, compared with the previous assessment on 21 October. The marginal correction came amid slow sponge iron and steel market sentiment, with no significant buying interest reported over the past few days.
Market participants reported that buyers remained reluctant to procure pellets at prevailing offer levels, citing weak downstream steel demand and limited scope for sponge iron producers to absorb higher input costs. While pellet producers largely maintained their offers, deals were reportedly concluded at INR 300-400/t below prevailing levels (not confirmed from buyer or seller), indicating a widening gap between buyers’ expectations and sellers’ price bid. Buyers were seeking a further correction of around INR 200-300/t, considering the challenging market conditions and pressure on conversion margins.
Rationale
- PELLEX has been derived using data points, i.e., trades, offers, and bids. To download the detailed methodology, click here.
- Zero (0) deals were recorded in this publishing window and was not taken for calculation. Thus, the T1 trade category was accorded a weightage of 0%.
- Seventeen (17) firm offers, bids, and indicative prices were heard, of which twelve (12) were taken for price calculation and given the balance 100% weightage.
Price movements and offers
Major pellet manufacturers in Chhattisgarh maintained their offers for Fe 62.5-63% (± 0.5%) grade pellets, supported by limited spot availability, maintenance-related supply constraints and elevated raw material costs. The gradual resumption of procurement following the Durga Puja and Dussehra holidays had earlier provided some support to market sentiment. However, this has yet to translate into sustained buying interest.
Market participants indicated that sellers continued to hold offers in anticipation of improved demand, while buyers remained unwilling to accept prevailing prices amid weak downstream steel market conditions. The gap between offers and executable deals widened, with transactions reportedly not getting concluded at the prevailing levels.
Buyers were seeking a further reduction of around INR 200-300/t, citing unviable procurement economics under current market conditions. Nevertheless, maintenance shutdowns and limited availability of readily deliverable material continued to restrict the scope for aggressive price cuts by producers.
Market scenario
Despite the marginal decline, pellet producers remained largely firm on offers, supported by limited spot availability and elevated raw material costs. Maintenance shutdowns at major plants have constrained material availability, while several manufacturers remain occupied with pending dispatches against previously committed orders. These factors have limited selling pressure and prevented a sharper price correction despite weak demand.
However, market sentiment remained cautious as buyers resisted higher offers and preferred to delay fresh procurement amid expectations of further price softening. Although some lower-priced material from outside the region was available, market participants indicated that these supplies could not fully meet local requirements, providing some support to domestic offers.
The combination of weak downstream demand, buyer resistance and lower-priced transactions prompted the marginal decline in the PELLEX assessment, despite supply side constraints and elevated production costs.
The Odisha Mining Corporation (OMC) received bids for around 1.41 mnt of iron ore fines against 1.44 mnt offered in its auction held on 22 October, representing a response of approximately 98%. Only a few low-grade fines lots remained unsold.
Bids increased by INR 50-350/t m-o-m despite base prices cut by the miner. The stronger participation indicated improved acceptance of auction material amid limited high-grade availability.
OMC reduced base prices for fines by around INR 150/t from the previous month’s levels, while calibrated lump ore base prices were lowered by INR 50-450/t, depending on grade and source. Despite these reductions, bids for fines were reportedly INR 200-450/t above the revised base prices, reflecting competition for available material.

Key market drivers
- Sponge iron prices rise by INR 300/t ($2/t) w-o-w: BigMint’s price assessment for P-DRI in Raipur rose by INR 300/t ($3/t) to INR 28,100/t ($296/t) ex-works on 23 October compared with 16 October. The increase was primarily driven by limited availability of good-quality material, prompting buyers to secure supplies and replenish stocks ahead of the coming week. However, the price rise did not translate into stronger pellet buying, as downstream demand remained subdued and conversion margins continued to face pressure.
- Billet prices down by INR 50/t ($0.5/t) w-o-w: BigMint’s billet index in Raipur declined by INR 50/t ($0.5/t) to INR 43,850/t ($462/t) ex-works on 23 October compared with 16 October. Lower offers encouraged some short-term procurement in the semi-finished steel segment, while sponge iron bookings provided limited support to raw material demand. However, continued weakness in finished steel demand and fragile market confidence restricted the scope for a sustained recovery in billet prices, weighing on the broader steel value chain.
Outlook
BigMint expects Raipur pellet prices to remain under pressure in the near term, with weak downstream steel demand, limited fresh buying and resistance to prevailing offers likely to cap price recovery. Although maintenance shutdowns and elevated raw material costs may limit the scope for sharper corrections, prices could soften further if buyers continue to defer procurement and the gap between offers and executable deals persists.
Leave a Reply