- Tight pellet availability supports prices despite weak steel demand
- Muted trading activity as higher offers face resistance
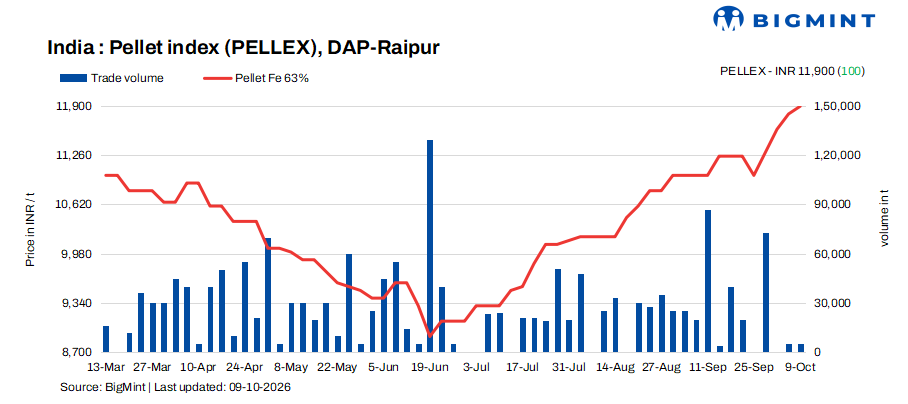
PELLEX, BigMint’s bi-weekly domestic pellet (Fe 63% ± 0.5%) index for Raipur, increased by INR 100/t ($1/t) to INR 11,900/t ($123/t) DAP Raipur on 9 October 2026, compared with the previous assessment on 6 October. Limited pellet availability and dispatch constraints affecting iron ore fines supplies continued to support prices, despite weakening sponge iron and finished steel prices. However, trading activity remained subdued as prevailing pellet prices were considered unviable at current downstream steel prices.
Rationale
- PELLEX has been derived using data points, i.e., trades, offers, and bids. To download the detailed methodology, click here.
- Zero (0) deals were recorded in this publishing window of which none were taken for calculation. Thus, the T1 trade category was accorded a weightage of 0%.
- Sixteen (16) firm offers, bids, and indicative prices were heard, of which fourteen (14) were taken for price calculation and given the balance 100% weightage.
Price movements and offers
Pellet availability remained tight in the Raipur market, with limited spot supplies supporting prevailing price levels. NMDC dispatch constraints have restricted availability, affecting and replenish market supplies.
Pellet offers largely remained at similar levels, with most manufacturers maintaining their prevailing prices amid limited availability. However, higher offers failed to attract significant buying interest as downstream steel prices weakened, reducing the viability of procurement at current levels.
Market scenario
Market participants reported that pellet prices remained firm despite limited buying interest. Sellers were reluctant to reduce offers amid tight availability of pellets and iron ore fines, while consumers remained cautious due to weak downstream market conditions. Few sellers are maintenace shut down or not offering in the market.
A seller said that prices were unlikely to decline in the near term because of the scarcity of pellets and fines in the region, although market activity remained subdued.
A consumer indicated that sufficient stocks had been procured at earlier price levels, limiting the need for fresh purchases at current offers.
A market participant expected prices to correct if buying activity remained subdued.

Key market drivers
- Sponge iron prices decrease w-o-w: Sponge PDRI prices stood at INR 28,850/t ($298/t) exw Raipur on 9 October, down by INR 450/t ($5/t) w-o-w from 9 October. Weak demand and limited buying enquiries pressured offers, although lower prices attracted some buying interest in eastern India. Elevated input costs limited the scope for further price reductions, while subdued finished steel demand and price declines of around INR 100-600/t d-o-d weighed on overall market sentiment.
- Billet prices fall w-o-w: BigMint’s billet index in Raipur decreased by INR 650/t ($7/t) w-o-w to INR 45,100/t ($466/t) exw on 9 October 2026 against 1 October. Weak demand across semi-finished and finished steel markets, coupled with cautious procurement and expectations of further price corrections, weighed on spot prices. A few deals were concluded at lower levels towards the end of the trading session, while overall market participation remained limited.
Outlook
Raipur pellet prices are expected to remain firm in the near term, supported by limited spot availability and constraints in iron ore fines supplies. However, continued weakness in sponge iron and billet prices, alongside subdued downstream demand, could intensify resistance to higher pellet offers. An improvement in NMDC dispatches and availability may ease supply constraints and exert downward pressure on prices.
Leave a Reply