- Although rains ease, dispatches expected to normalise only in Nov
- SAIL auctions see active buying interest despite muted direct trades
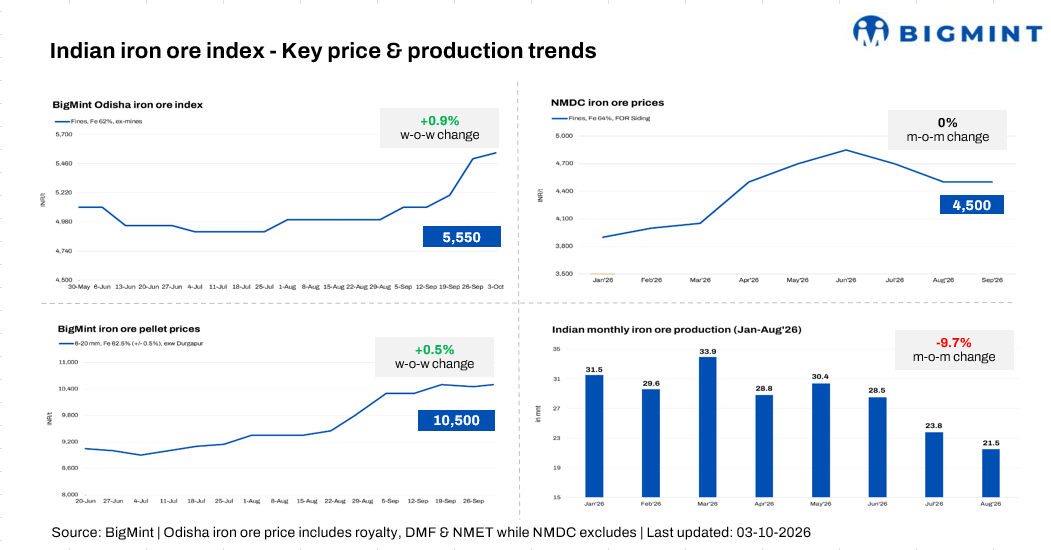
BigMint’s Odisha Fe 62% iron ore fines assessment increased by INR 50/tonne (t) ($0.5/t) w-o-w to around INR 5,550/t ($57.6/t) ex-mines in the week ending 3 October 2026. The rise was driven by restricted availability and firm offers, although buyers remained reluctant to procure at elevated levels. Consequently, spot-market activity was subdued, with no significant deals reported during the week.
Although rainfall has eased, mining and dispatches have yet to return to normal, keeping supplies tight. An Odisha-based trader said, “Odisha iron ore market is still tight; rains have stopped, but normalcy in dispatches will come in November.” The anticipated delay in supply normalisation is helping sellers hold their offers despite limited spot buying.
On the demand side, steel mills continued to adopt a wait-and-watch approach, largely limiting purchases to immediate requirements. Another trader said, “Buying remains cautious, with steel mills closely monitoring finished steel demand before committing to fresh ore volumes.” High prevailing prices and uncertain downstream demand have kept buyers from actively replenishing inventories.
Meanwhile, the market showed stronger sentiment for lumps compared with fines. A major pellet maker told BigMint, “Prices are stronger for lumps, while fines remain stable to firm and buyers continue to purchase selectively.” This suggests that while supply constraints are lending support to the overall market, cautious procurement is preventing a broader acceleration in fines demand.
The current market is therefore characterised by a divergence between tight supply and subdued buying. While sellers continue to draw support from limited availability, buyers are reluctant to chase prices higher amid concerns over downstream steel demand and elevated raw-material costs. The absence of significant trades this week further indicates that the recent price increase has not yet translated into stronger spot-market participation.
Rationale
- T1: One (1) deal for Fe 62% fines was recorded during the publishing window but was not considered and assigned 0% weightage in the index calculation.
- T2: BigMint received seveteen (17) offers and indicative prices under the T2 category (offers, indicative, and bids) in this publishing window. Ten (10) were taken into consideration and given 100% weightage. To check BigMint’s iron ore assessment, pricing methodology, and document,click here.
Odisha auctions continued to attract active buyer participation when compared to direct sales. SAIL’s Odisha iron ore auctions held during 26-29 September saw strong buyer participation, with around 144,000 t booked across the auctions. In the 26 September auction, 72,000 t was booked against 76,000 t offered, including 16,000 t of Bolani dump fines (Fe 60.22%) at INR 5,230/t ($54.3/t) ex-mines and 56,000 t of CLO (Fe 62%) at INR 6,465/t ($67.1/t) FOR loaded-into-rake. The CLO bid was INR 510/t ($5.3/t) lower than the previous 18 September auction, indicating some moderation in bids.
In the subsequent 28-29 September auction, the entire 72,000 t offered were booked, comprising 60,000 t of fresh Bolani fines (Fe 61%) at INR 5,830/t ($60.5/t) FOR loaded-into-rake and 12,000 t of CLO (Fe 62.40%) at INR 6,800/t ($70.5/t) ex-mines. While full booking reflected healthy auction interest and renewed participation, the fresh fines bid was INR 45/t ($0.5/t) lower than the 18 September auction, suggesting that buyers remained price-conscious despite tight availability.
Eastern India steel markets strengthen on firmer raw material sentiment
- Pellet prices rise across Barbil, Durgapur: Odisha’s Barbil (Fe 62.5%) pellet prices rose INR 100/t ($1/t) to INR 9,600/t ($99.9/t) LTW on 1 October, supported by firm raw material prices and limited spot availability. Durgapur pellet prices also increased marginally by INR 50/t ($0.5/t) w-o-w to INR 10,500/t ($109.2/t) ex-works. Sentiment remained stable to firm, with higher iron ore prices and steady sponge iron demand supporting prices, while cautious buying and elevated offers limited further upside.
- Rourkela C-DRI prices rebound on firmer steel and raw material sentiment: Rourkela C-DRI prices recovered by INR 1,500/t ($15.6/t) w-o-w to INR 31,000/t ($321.8/t) on 3 October 2026, from INR 29,500/t ($306/t) a week earlier. The sharp increase was supported by higher sponge iron and iron ore prices, along with firmer finished steel and billet markets. Improved steel realisations encouraged producers to raise offers, while tighter availability of DRI in the spot market also provided support. However, buyers remained cautious at higher levels, with fresh procurement largely limited to immediate requirements.
- Rourkela rebar prices surge w-o-w amid firmer steel sentiment: Rourkela IF-route rebar (12-25 mm) prices rose sharply by INR 2,500/t ($26/t) w-o-w to INR 56,500/t ($586.6/t) on 3 October 2026, from INR 54,000/t ($560.6/t) on 26 September. The increase was supported by firmer billet and sponge iron prices, higher input costs and improved regional steel market sentiment. However, buying remained selective at elevated levels, with market participants closely monitoring downstream demand and the sustainability of the recent price rise.

Outlook
Odisha Fe 62% fines prices are expected to remain firm in the near term. Tight availability and the delayed normalisation of dispatches are likely to provide a floor to prices through October. However, high prevailing price levels, selective buying and subdued spot transactions could restrict further upside.
With normalisation in Odisha dispatches expected around November, prices are likely to remain supported until then, although sustained gains may be difficult without a corresponding improvement in downstream buying.
Leave a Reply