- High prices and cautious buying continue to limit met coke demand
- Chinese buying and coking coal price movements will determine the next price direction
India’s metallurgical coke (met coke) market remained broadly stable to slightly weak in the assessment week ended September 30, with prices holding at elevated levels despite a gradual softening in coking coal costs.
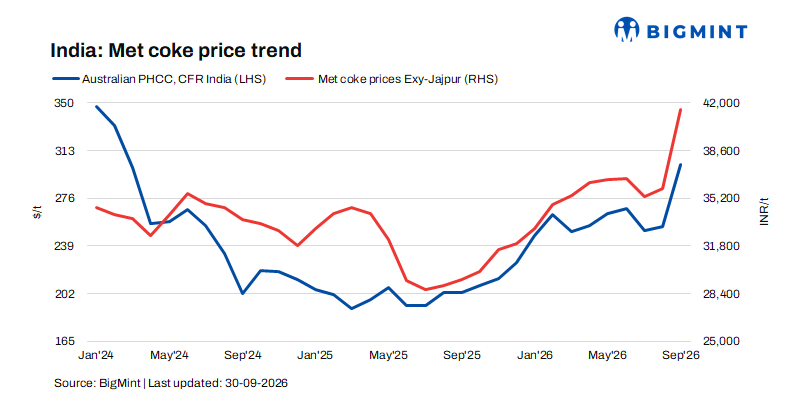
BF-grade met coke prices in eastern India remained unchanged week on week at INR 42,000/t ex-Jajpur, while western India prices declined marginally by INR 200/t to INR 37,800/t ex-Gandhidham. Foundry-grade met coke prices in Rajkot also eased by INR 100/t to INR 39,400/t ex-Rajkot.
Price indications in eastern India are also likely to drop to INR 39,000-41,000/t exw levels due to subdued buying, market participants said.
High prices keep buyers on the sidelines
Market activity remained subdued, with no major deals reported during the week as buyers adopted a wait-and-watch approach. Market participants indicated that current met coke prices remain elevated and are becoming increasingly difficult for steel and other consuming industries to absorb, limiting fresh buying interest. With downstream consumers anticipating further price corrections, most buyers are currently restricting purchases to immediate requirements.
China holiday to set the tone for Global coke market
China’s Golden Week holiday from October 1-7 is expected to temporarily limit market activity. Market participants expect buying interest to regain momentum after the holiday, which could provide direction to international met coke prices. A subsequent recovery in Chinese coking coal prices could increase coke production costs and provide upward support to met coke prices, while continued weakness in raw material prices would reinforce expectations of lower coke prices.
Chinese coke market remains under pressure
China’s coking coal market remained stable to slightly weak on September 29 as mine restarts accelerated, although supply remained relatively tight. Weak downstream demand and limited restocking kept buying largely need-based. Chinese coke prices also remained stable. Rising coke plant operating rates, coupled with subdued pig iron output and weaker-than-expected demand, have increased downside pressure, with market participants anticipating a possible first-round coke price reduction.
Australian coking coal adds to cost-side pressure
International coking coal prices also weakened during the week, with Australian premium hard coking coal (PHCC) FOB prices declining by around $3/t week on week to $272/t as of September 30. Softer Australian and Chinese coking coal prices are lowering the international cost benchmark for coke production. If the correction continues, Indian coke producers could face lower replacement costs, potentially prompting buyers to seek downward revisions in met coke prices.
Pig iron prices offer limited support
Pig iron prices provided some counter-support, with Durgapur steel-grade pig iron prices rising by INR 1,100/t week on week to INR 42,100/t ex-works. Market sources attributed the increase to supply disruptions from a seller, suggesting that the price rise was driven more by temporary supply constraints than by a broad improvement in demand.
Outlook
The Indian met coke market is expected to remain stable to slightly weak in the near term, as elevated coke prices, cautious downstream buying and softer international coking coal prices continue to weigh on sentiment. However, the direction after China’s Golden Week will remain important. A recovery in Chinese buying and a rebound in coking coal prices could strengthen global coke replacement costs and limit further downside, while continued weakness in raw materials and subdued steel-sector demand could encourage further price corrections in India.
Leave a Reply