- Cautious buying keeps met coke prices under pressure
- Indonesian supply disruptions may limit further drops
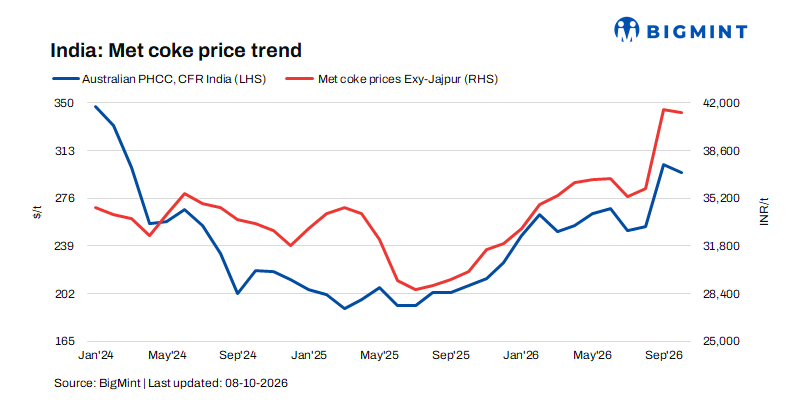
India’s metallurgical coke (met coke) prices declined w-o-w in the assessment week ended October 8, as subdued steel-market economics and cautious buying weighed on prices.
BF-grade met coke prices in eastern India fell sharply by INR 700/t w-o-w to INR 41,300/t ex-Jajpur, while western India prices declined by INR 400/t to INR 37,400/t ex-Gandhidham. Foundry-grade met coke prices in Rajkot also eased by INR 200/t to INR 39,200/t ex-Rajkot.
Market activity remained selective, with a 5,000-t transaction reported at INR 44,000/t exw in eastern India, while another trader reportedly purchased 2,000 t of BF-grade coke at INR 41,500/t exw eastern India. The transactions indicate that buyers remain price-sensitive, particularly amid pressure on steel margins.
Steel margin pressure keeps buyers cautious
Market participants indicated that prevailing met coke prices remain challenging for steel producers, with some buyers anticipating a further INR 2,000-3,000/t correction. However, the extent of any further decline remains uncertain, as current prices are also being supported by supply-side constraints.
At the same time, market participants noted that domestic coke ovens will be directed to operate at maximum utilisation of their available capacity. Higher operating rates could improve domestic availability and limit the scope for a sharp near-term price recovery.
Supply constraints provide a floor to prices
Despite weak buying sentiment, supply-side factors are providing some downside protection. Market participants highlighted supply disruptions from Indonesia, reportedly linked to water shortages, which could affect raw-material availability and keep replacement costs relatively firm. Tightness in parts of the market is therefore preventing prices from falling in line with the weaker steel-sector sentiment.
Australian coking coal prices ease marginally
International coking coal prices also softened during the week. Australian premium hard coking coal (PHCC) FOB prices declined by around $1/t w-o-w to $271/t, though the slight decline is likely to have provided only limited immediate cost relief, and the impact on production costs would likely be gradual.
Pig iron market offers mixed support
Pig iron prices provided limited support to the met coke market, with Durgapur steel-grade pig iron prices declining by INR 200/t w-o-w to INR 41,850/t ex-works. However, stronger export activity continues to influence domestic availability. India’s pig iron exports reached around 1.73 mnt during January-September 2026, with September exports rising to approximately 420,000 t from 310,000 t in August.
Strong export realisations, particularly in the US market, have encouraged producers to prioritise overseas shipments, with export sales reportedly offering an estimated INR 1,000/t premium over domestic realisations.
Outlook
Domestic met coke prices are expected to remain under pressure in the near term, but a sharp correction may be limited by supply constraints and improving coke oven utilisation. Weak steel margins, cautious procurement and expectations of further price reductions could keep buyers away from aggressive spot purchases.
However, Indonesian supply disruptions, tighter availability in some markets and relatively stable raw-material costs could provide a floor to prices. Overall, met coke prices are likely to remain stable to moderately weaker in the near term, with the direction largely dependent on steel margins, domestic coke availability and the sustainability of export-led pig iron demand.
Leave a Reply