- Weak steel margins, muted steel demand lead to need-based buying
- Imported coke prices remain stable, coking coal prices fall by $4/t
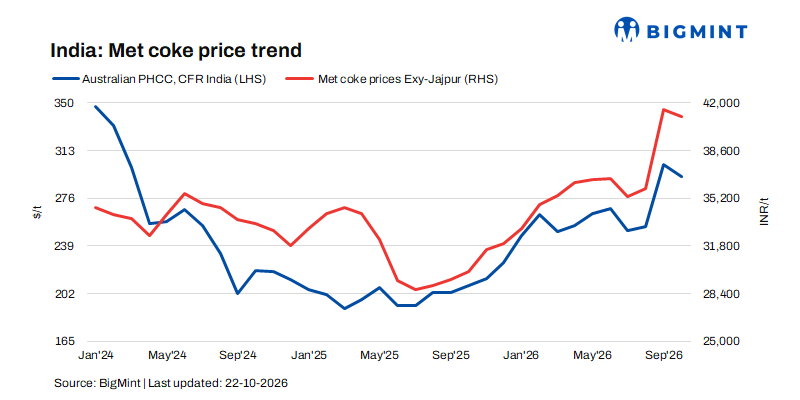
India’s metallurgical coke market weakened in the assessment week ended 22 October 2026, as selective procurement, subdued steel-market conditions, and pressure on steel-mill margins continued to restrict buying activity.
BF-grade met coke prices in eastern India declined sharply by INR 800/t w-o-w to INR 40,500/t ex-Jajpur, while western India prices fell by INR 400/t to INR 37,000/t ex-Gandhidham. Foundry-grade met coke in Rajkot also eased by INR 100/t to INR 39,100/t ex-Rajkot.
Market participants reported limited trading activity, with buyers largely purchasing only against immediate requirements and remaining reluctant to build inventories at prevailing high price levels. Although demand exists, elevated coke and coking coal costs, combined with weak downstream steel economics, are preventing buyers from accepting further price increases.
Imported coke price indications remain stable
On the import front, Indonesian met coke prices remained stable at around $368/t CFR India, while Australian premium hard coking coal (PHCC) prices declined by approximately $4/t w-o-w to $265/t FOB, offering marginal relief to coke producers.
As per market sources, a 30,000-t cargo of 65 CSR Indonesian coke was reportedly traded at around $339/t FOB Indonesia, indicating competitive availability in the seaborne market. However, the modest correction in coking coal prices has not been sufficient to significantly improve producer margins, as overall raw-material costs remain relatively elevated.
Chinese coke makers initiate 1st round of hikes, mills cautious amid margin pressure
China’s coking coal market remained broadly stable, supported by a gradual recovery in mine production as more mines resumed operations; however, safety inspections continued to restrict a stronger supply recovery.
In the coke market, major producers initiated the first round of RMB 50-55/t ($7.5-8) price increases, but steel mills have remained cautious amid weak profitability and limited purchasing requirements. The resulting steel-coke pricing standoff is likely to keep Chinese coke prices broadly stable with a weak undertone, while developments in China remain an important factor for the regional seaborne market.
Pig iron prices rise on export bookings, regional supply constraints
Meanwhile, Durgapur steel-grade pig iron prices increased by INR 500/t w-o-w to INR 41,800/t ex-works, supported by fresh export bookings and supply-side constraints affecting availability and dispatches. Strong bookings in eastern India improved seller confidence and tightened regional supply, prompting producers to raise offers. However, buying interest remained limited at higher levels, with buyers targeting prices of INR 41,000-41,500/t. The upward trend will depend on sustained demand and buyers’ willingness to accept higher offers.
Outlook
Indian met coke prices are likely to remain range-bound to mildly bearish, as cautious steel-mill buying and weak margins limit demand. Softer coking coal prices may offer some cost relief, while improved steel demand and restocking will be crucial for a sustained price recovery.
Leave a Reply