- Sellers waiting for fresh inquiries to emerge
- Indian festive season limits shipment activity
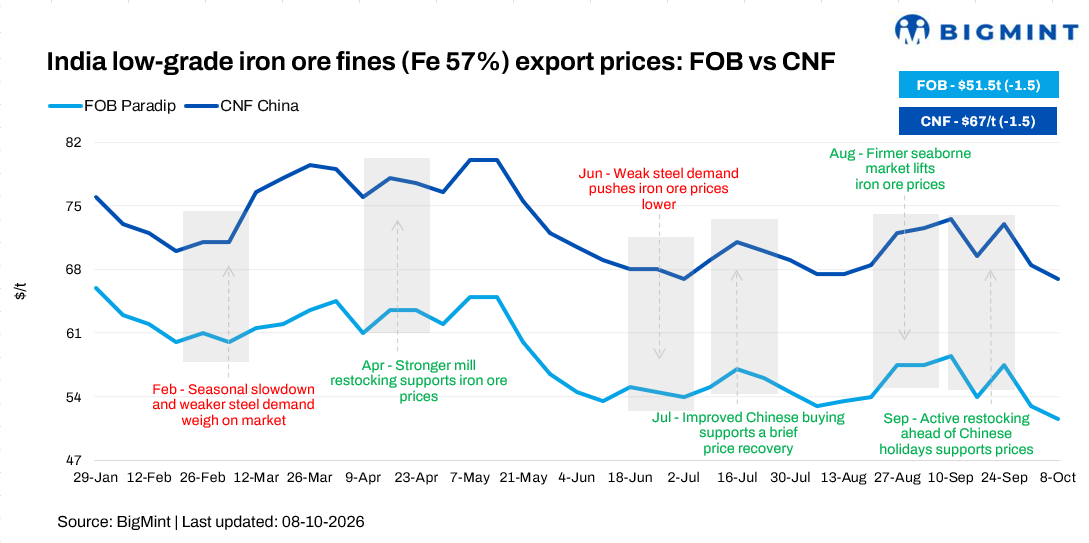
India’s low-grade iron ore fines (Fe 57%) export prices declined by around $1.5/tonne (t) w-o-w to $51.5/t FOB east coast in the week ended 8 October 2026, from $53/t a week earlier. The price was equivalent to around $67/t CFR China.
Market activity remained subdued as the Chinese market reopened following the holiday period, with buyers and sellers yet to establish clear price direction. Exporters indicated that fresh enquiries are needed before market sentiment can be assessed more clearly.
A market participant said, “China has just opened; there is no clarity in the market now. It will take time till next week.” Another exporter highlighted, “The current level could be considered but is not commercially feasible for sales,” adding that market participants may wait for fresh Chinese enquiries before committing cargoes.
Festive season limits shipment activity
Indian exporters also remained cautious amid the domestic festive season, which has reduced market activity and weakened the viability of shipments at prevailing export levels.
“Due to the festive season, market activity remains dull and current rates are not viable, so we are postponing shipments for now,” a source told BigMint.
Meanwhile, exporters reported that west coast cargoes were attracting a discount of around 14-15%, with a 6-7% markup currently applicable. Market participants expect activity to remain slow initially following China’s reopening, although enquiries could improve once buyers return to the market.
Rationale
- No deals were reported during the current publishing window; consequently, T1 trades received 0% weightage in the index calculation.
- BigMint received fourteen (14) indicative price inputs, of which eleven (11) qualified as T2 inputs and accounted for the 100% weightage.
Domestic-export spread narrows as low-grade prices weaken
The spread between domestic and export realisations narrowed to around INR 1,040/t ($10.7/t) this week, as prices in both markets moved lower. Export realisations declined to around INR 2,464/t ($25.5/t), while domestic low-grade iron ore prices fell by INR 250/t ($2.6/t) w-o-w to INR 3,600/t ($37.2/t) ex-mines.
The decline in domestic prices reflects weak buying interest and subdued market activity, with buyers remaining cautious amid limited visibility on near-term steel demand. In the export market, softer Chinese iron ore sentiment and limited fresh enquiries have kept exporters under pressure, reducing realisations.
Despite the narrowing spread, domestic realisations remain significantly higher than export netbacks, limiting the commercial attractiveness of exports. Market participants are likely to monitor Chinese buying activity and domestic steel demand for clearer direction in the coming weeks.
Weak steel demand sentiment pressures China iron ore market
Global benchmark iron ore (Fe 61%) prices declined by $2/t w-o-w to $91/t CFR China on 7 October 2026, from $93/t on 30 September. The decline reflects cautious buying sentiment in China, with market participants awaiting clearer signals on steel demand and procurement activity. Market sentiment remains subdued as buyers continue to assess the strength of downstream steel demand before committing to fresh cargoes. The softer benchmark is also adding pressure to seaborne iron ore suppliers, with exporters likely to remain cautious on offers at lower price levels.
January 2027 iron ore futures on the Dalian Commodity Exchange (DCE) decreased by RMB 20/t ($3/t) w-o-w to RMB 682.5/t ($101.8/t) on 1 October, from RMB 702.5/t ($104.8/t) a week earlier. The ongoing Golden Week holiday (1-7 October) also kept market activity and spot buying muted, limiting near-term support for iron ore prices.
Outlook
Indian low-grade iron ore fines export prices are likely to remain under pressure through the coming week unless fresh Chinese enquiries provide clearer buying support. Exporters are expected to remain cautious on shipments at current levels, while the pace of Chinese procurement after the holiday period will be the key indicator for price direction.
Leave a Reply