- Port congestion and tighter vessel availability lend support
- Chinese buyers remain reluctant to accept current levels
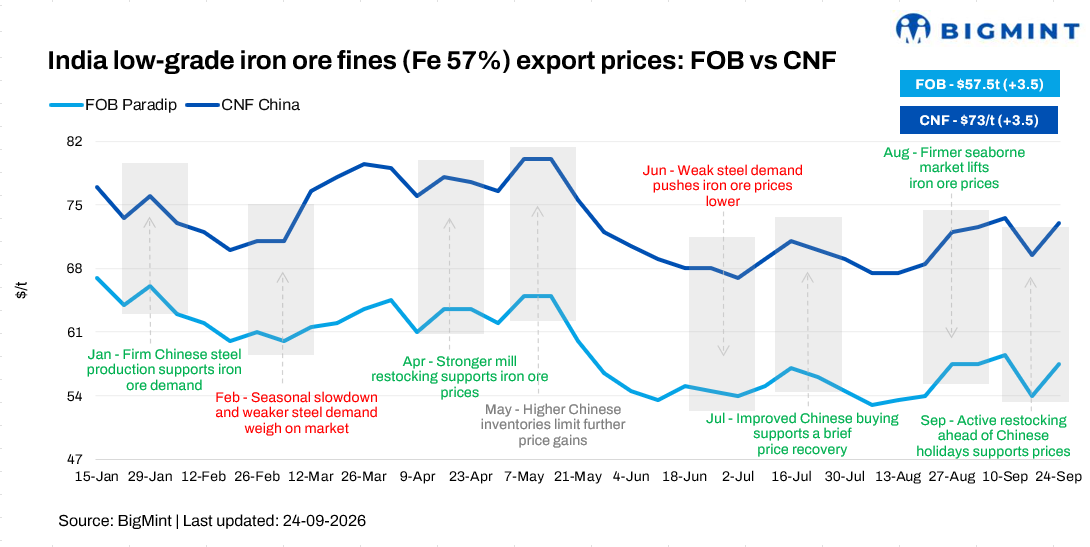
India’s low-grade iron ore fines (Fe 57%) export prices recovered by around $3.5/tonne (t) w-o-w to $57.5/t FOB east coast in the week ended 24 September 2026, after touching a one-month low in the previous week. The price is equivalent to around $72.5/t CFR China, with higher freight costs continuing to influence export parity.
The recovery was supported by tighter vessel availability and port-related constraints, with some market participants reporting that prompt vessels were difficult to secure. However, buying interest remained subdued, with exporters facing limited enquiries and Chinese buyers showing resistance to current price levels. Several market participants indicated that quoted prices were not translating into workable deals.
A trader said, “The market is weak, and deals are unlikely to conclude at these levels.”
“Chinese players are still not accepting Indian offers, while a seller said enquiries were limited despite this period typically seeing stronger activity in September-October”, another source mentioned to BigMint.
Higher freight also continued to weigh on export economics. Market participants indicated freight levels of around $15-16/t, while one source suggested that Indian cargoes were facing competition from alternative origins and domestic availability.
Rationale:
- No deals were reported during the current publishing window; consequently, T1 trades received 0% weightage in the index calculation.
- BigMint received thirteen (13) indicative price inputs, of which ten (10) qualified as T2 inputs and accounted for the 100% weightage.
A Krishnapatnam-China shipment on was heard reportedly fixed at $15.90/dmt, although the export price level was not known at the time of publication.
Global market hold steady amid cautious Chinese buying
Global benchmark iron ore (Fe 61%) prices remained stable w-o-w at $95/t CFR China on 24 September. Meanwhile, January 2027 iron ore futures on the Dalian Commodity Exchange (DCE) rose marginally by RMB 0.5/t ($0.01/t) w-o-w to RMB 713.5/t ($106.3/t) on 24 September, from RMB 713/t ($106.2/t) a week earlier.
The market remained stable-to-cautious, with prices supported by firm raw material costs and limited availability of high-grade cargoes, while subdued steel margins and cautious Chinese buying ahead of the October holidays capped upward movement.
Domestic-export price gap narrows as export realisations improve
The spread between domestic and export realisations narrowed to around INR 612/t ($6/t) this week, as export realisations improved while domestic prices also moved higher. Export realisations rose to INR 2,993/t ($31/t), while domestic ex-mines offers increased by INR 200/t ($2/t) to INR 3,700/t ($39/t).
The narrowing spread indicates a modest improvement in export economics, although domestic realisations continue to remain higher. Export competitiveness could improve further if international prices strengthen or freight costs ease.
Outlook
Near-term, Indian low-grade iron ore export prices are likely to remain stable-to-cautious, with limited upside as Chinese buyers remain reluctant to accept current levels and fresh enquiries are subdued. Elevated freight costs will continue to weigh on export parity. Pre-holiday restocking ahead of China’s 1-7 October Golden Week could provide some near-term buying support, but activity may slow as the holiday approaches.
Tight vessel availability and port-related constraints could provide some support to FOB prices. However, the upcoming Golden Week holiday and the possibility of reduced Chinese spot activity could limit deal-making in early October. A pickup in buying after the holiday or a decline in freight rates could improve export parity and support modest upside.
Leave a Reply