- India operations sales rise 14% y-o-y
- Higher volumes support quarterly profitability
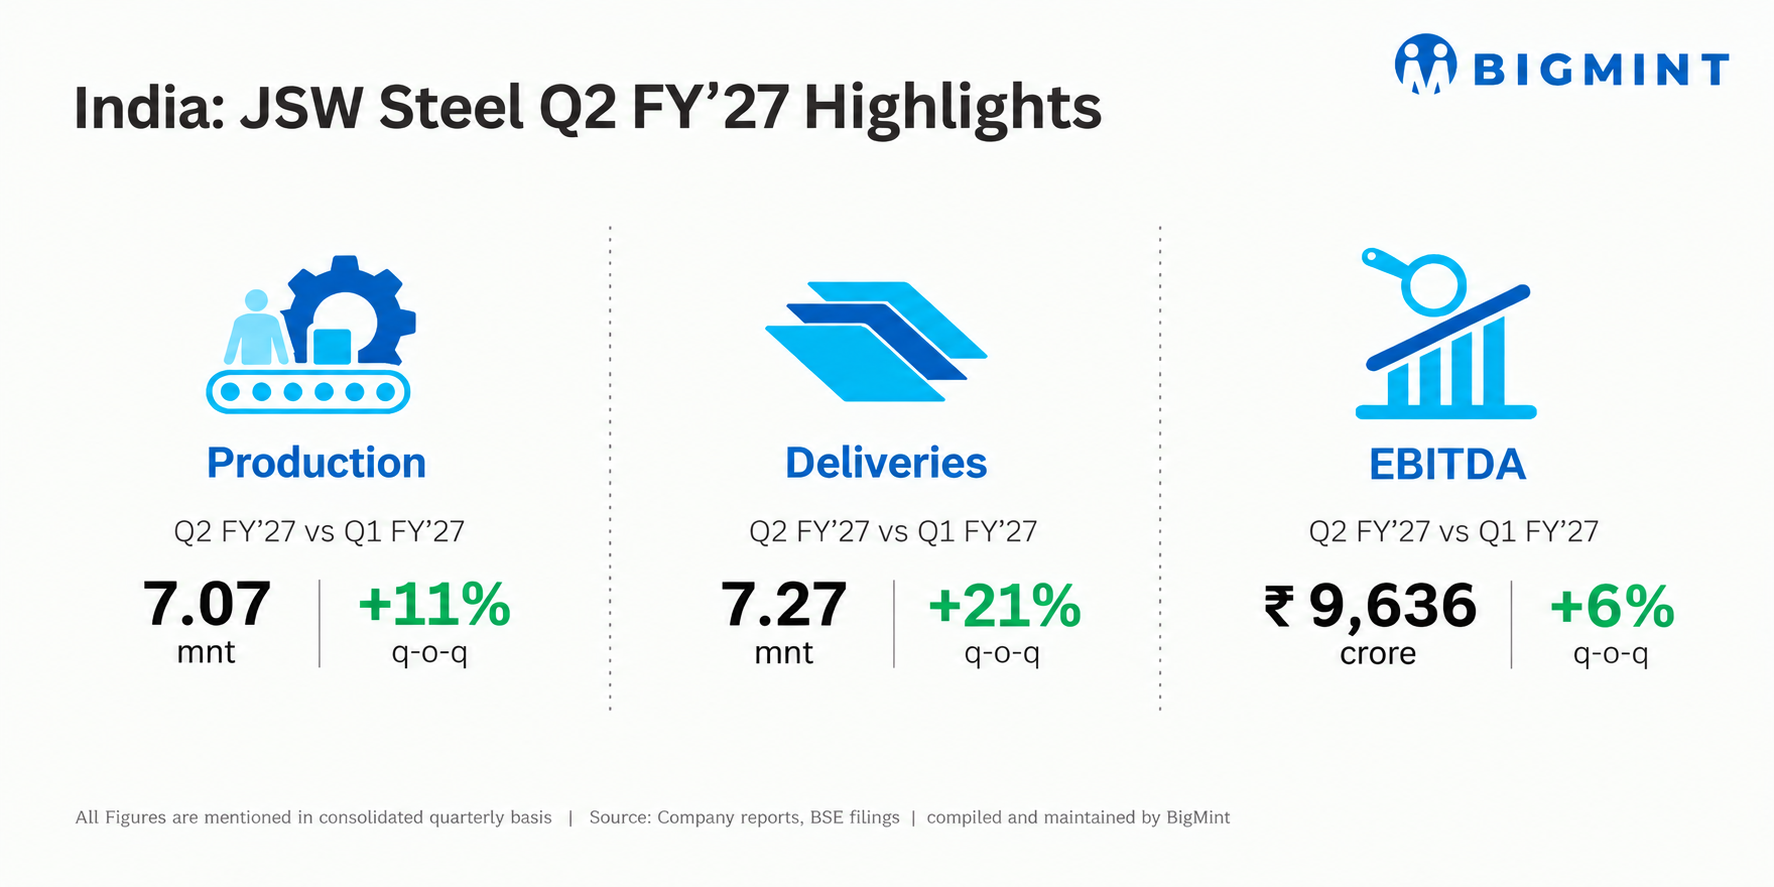
JSW Steel reported a strong performance from its India operations in Q2 FY’27, supported by higher steel sales, improved revenue and stronger profitability. Adjusted operating EBITDA increased 27% year-on-year (y-o-y) to INR 9,636 crore from INR 7,614 crore in Q2 FY’26 on a proforma (PF) basis, while rising 6% quarter-on-quarter (q-o-q) from INR 9,096 crore in Q1 FY’27.
Crude steel production from India operations increased 5% y-o-y to 7.07 million tonnes (mnt) from 6.71 mnt in Q2 FY’26 (PF), while rising 11% q-o-q from 6.35 mnt in Q1 FY’27. Steel sales rose 14% y-o-y to 7.27 mnt from 6.35 mnt and increased 21% q-o-q from 6.02 mnt, reflecting improved operational performance and higher dispatches.
Revenue from operations increased 30% y-o-y to INR 50,188 crore from INR 38,466 crore in Q2 FY’26 (PF), while rising 17% q-o-q from INR 42,894 crore in Q1 FY’27. Profit after tax (PAT) increased to INR 5,099 crore from INR 1,795 crore in Q2 FY’26 (PF), while improving from INR 4,927 crore in the previous quarter.
Project updates
BF-3 upgradation at Vijayanagar: The upgraded Blast Furnace-3, expanded from 3 mtpa to 4.5 mtpa, continued ramping up after its commissioning in June 2026, reaching approximately 90% utilisation during Q2 FY’27.
Vijayanagar Phase-II expansion: Equipment ordering is in progress for the 5 mtpa capacity expansion, with commissioning targeted by FY’30.
Dolvi Phase-III expansion: Civil work and equipment erection are underway for the expansion from 10 mtpa to 15 mtpa, with commissioning targeted by September 2027.
JSW Utkal greenfield project: Construction continues at the Paradip facility. The two 8 mtpa pellet plants are scheduled for commissioning by FY’28, while the 5 mtpa blast furnace, 6 mtpa steel melting shop (SMS) and 6 mtpa hot strip mill (HSM-2) are targeted for commissioning by Q3 FY’30.
Downstream expansion: A 0.55 mtpa cold-rolled non-oriented (CRNO) steel plant at Vijayanagar is scheduled for commissioning by March 2028. At Khopoli, construction is underway for the 0.96 mtpa continuous galvanising line (CGL) complex, with CGL-2 targeted for commissioning by Q1 FY’28 and CGL-3 by Q1 FY’29. New galvanising and tinplate facilities at Vijayanagar and Rajpura are also progressing.
New growth projects: JSW Steel announced Phase-II of the 5 mtpa JSW Utkal project, a 1.8 mtpa cold rolling mill (CRM) complex at Vasind, and a 5 mtpa expansion at JSW JFE Steel Ltd. (JJSL), strengthening its long-term capacity expansion plans.
Other highlights
Production and sales increase: India operations crude steel production rose 5% y-o-y to 7.07 mnt, while steel sales increased 14% y-o-y to 7.27 mnt. Domestic sales accounted for 87% of dispatches, with exports contributing 13%.
Value-added product portfolio: Sales of value-added and special products (VASP) increased 11% y-o-y to 4.11 mnt in Q2 FY’27 from 3.72 mnt in Q2 FY’26 (PF), although their share of total sales declined to 56% from 59%.
Profitability improves: Adjusted operating EBITDA increased 27% y-o-y and 6% q-o-q to INR 9,636 crore, supported by higher sales volumes and improved operating performance.
Capital expenditure remains on track: JSW Steel maintained its FY’27 capital expenditure guidance of INR 22,000-24,000 crore, with investments directed towards steelmaking capacity expansion, downstream facilities, mining and cost-saving projects.
FY’27 volume guidance maintained: JSW Steel reiterated its consolidated FY’27 guidance of 29.75 mnt for crude steel production and 28.60 mnt for steel sales.
Outlook
JSW Steel’s India operations recorded higher production, sales and profitability in Q2 FY’27, supported by improved volumes and operational performance. Ongoing capacity expansion at Vijayanagar, Dolvi and Utkal, alongside investments in downstream facilities, is expected to strengthen the company’s production capabilities and value-added product portfolio.
The company’s near-term performance will depend on demand conditions across key end-use sectors, steel realisations and raw material costs. Continued execution of expansion projects and improved operational efficiency are expected to support its long-term growth strategy, while the company maintains its FY’27 production and sales guidance.
Leave a Reply