- Monsoon disruptions continue to constrain regional supply
- OMC auction premiums strengthen iron ore replacement costs
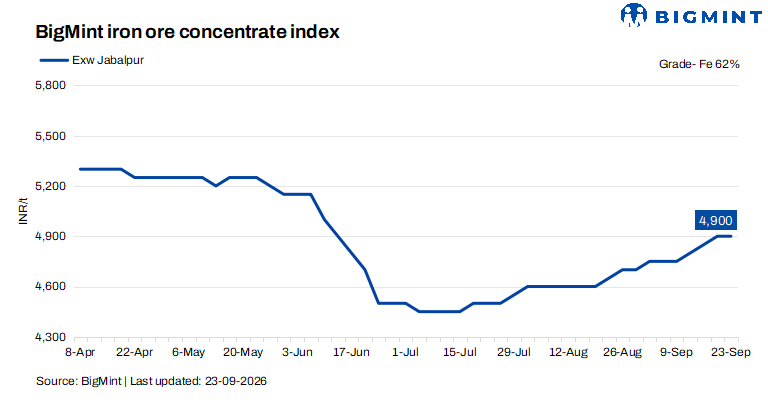
Indian iron ore concentrate prices remained firm during the assessment week ended 23 September 2026, supported by positive sentiment across the pellet and Odisha iron ore markets, alongside a strong response to Odisha Mining Corporation’s (OMC) latest iron ore auction. While trading activity remained moderate, sellers largely maintained their offers as tight availability, elevated replacement costs and ongoing monsoon-related disruptions provided a supportive backdrop to the market.
BigMint’s bi-weekly assessment for Fe 62% concentrate remained unchanged at INR 4,900/t ($51/t) ex-works, while offers for Fe 63% concentrate were heard at around INR 5,350/t ($56/t). Some sellers were also heard offering Fe 62% material at around INR 5,000-5,100/t ($52-53/t) ex-works, indicating that replacement costs are gradually moving above prevailing assessed levels.
The market’s stability was largely attributed to a limited availability of fresh material rather than weak fundamentals. Several sellers are currently prioritising the dispatch of material committed under earlier orders at previously agreed prices. As these volumes are cleared, sellers are expected to reassess their offers based on prevailing replacement costs and market conditions. This has kept fresh spot availability relatively restricted and prevented significant downward pressure on prices.
A Jabalpur-based seller told BigMint, “Although the market is up, we are continuing with our old orders at old prices. Once these orders are completed, only then will we consider revising our offers further.”
Trading activity remained moderate during the assessment window, with some transactions under discussion. However, buyers remained cautious about committing to large volumes at current price levels, particularly as higher concentrate prices could put pressure on downstream margins. This cautious buying has limited immediate price acceleration, while sellers’ reluctance to release fresh material at existing levels has provided a floor to the market.
Monsoon disruptions tighten availability
Supply-side constraints continue to play an important role in supporting concentrate prices. Continuous rainfall and monsoon-related disruptions have affected mining, production and transportation activity across the region. Water accumulation in mining areas has restricted production and movement of material, resulting in tighter availability.
The impact is particularly relevant for concentrate producers, as prolonged disruptions can delay both fresh production and transportation, limiting the amount of material available for immediate spot sales. With sellers already working through previously committed orders, the reduced flow of fresh material has further tightened the spot market.
Rationale
- One (1) trades were recorded in this publishing window, which were not taken into consideration. Therefore, this category received a 0% weightage.
- Ten (10) offers and indicative prices were heard, of which nine (9) were taken into consideration as T2 trades, receiving 50% weightage.
Factors shaping market dynamics
- PELLEX remains stable w-o-w: PELLEX, BigMint’s bi-weekly domestic pellet (Fe 63% +/- 0.5%) index for Raipur, remained unchanged w-o-w at INR 11,250/t DAP Raipur on 22 September 2026. Prices remained supported by elevated iron ore costs following OMC’s 19 September auction, where around 50-53% of fines offered were booked, while lump sales were at around 80%. Firm premiums on sold material kept iron ore realisations elevated, supporting pellet replacement costs.
- Odisha iron ore prices rise w-o-w: BigMint’s Odisha Fe 62% iron ore fines assessment increased by INR 100/t ($1/t) w-o-w to around INR 5,200/t ($54/t) ex-mines in the week ending 19 September 2026. The upward movement was supported by firm buying interest for higher-grade material, along with elevated replacement costs following OMC’s latest auction. Despite mixed sentiment across grades, availability of competitive high-grade ore remained relatively tight, encouraging buyers to maintain procurement and supporting price levels. Meanwhile, demand for lower-grade fines remained comparatively cautious, keeping the overall market sentiment mixed.
- OMC auction sees higher bids m-o-m: Odisha Mining Corporation (OMC) auctioned 1.817 million tonnes (mnt) of iron ore on 19 September 2026, comprising 1.21 mnt of fines and 0.61 mnt of lumps. Average fines bids increased by INR 750/t m-o-m, with 53% of the offered quantity booked, while lumps bids rose by INR 1,250/t, with around 80% of the material sold.
Outlook
Iron ore concentrate prices are expected to remain largely stable with an upside bias in the near term. The market is likely to remain supported by tight fresh availability, ongoing monsoon-related production, and logistics disruptions, firm Odisha iron ore prices and elevated pellet replacement costs.
Leave a Reply