- Q2 mined metal production reaches 271,000 t, up 5% y-o-y
- H1 refined metal production rises 6% y-o-y to a record 524,000 t
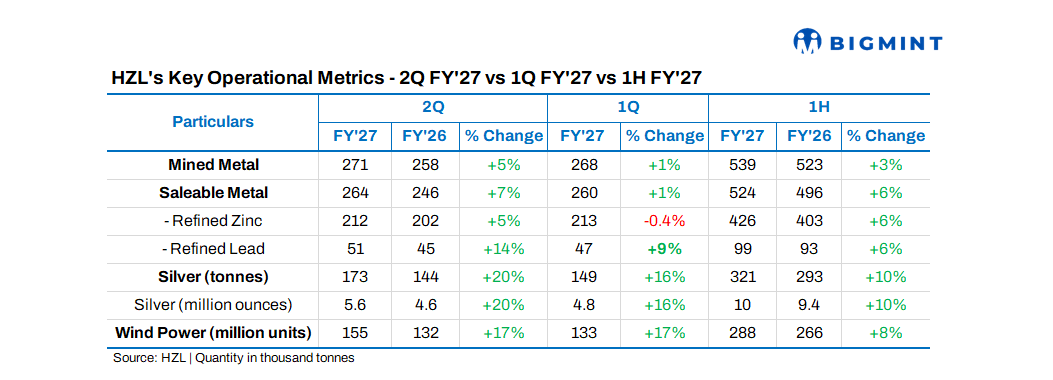
Hindustan Zinc Limited (HZL) reported record second-quarter mined metal production of 271,000 t for the quarter ended 30 September 2026, up 5% y-o-y, driven by higher ore production. The company also recorded its highest-ever first-half mined metal production for the sixth consecutive year at 539,000 t, up 3% y-o-y.
Refined metal production stood at 264,000 t in Q2FY27, increasing 7% y-o-y. The growth was supported by additional capacity unlocked through debottlenecking projects at the Chanderiya and Dariba smelters, along with the 160,000 t/year roaster at Debari. Production was also in line with plant availability during the quarter.
For the first half of FY27, refined metal production reached a record 524,000 t, up 6% y-o-y. The continued increase in refined output indicates improved utilisation of the company’s smelting capacity and supports stable availability of refined zinc for downstream consumers.
Saleable silver production stood at 173 t in Q2FY27, up 20% y-o-y and in line with the company’s production plan. H1 silver production reached 321 t, representing a 10% y-o-y increase, reflecting continued strength in HZL’s integrated polymetallic operations.
Meanwhile, wind power generation increased 17% y-o-y to 155 million units (MU) in Q2, in line with wind velocity and weather patterns. H1 wind power generation stood at 288 MU, up 8% y-o-y.
From a market perspective, HZL’s record mined and refined metal production strengthens the domestic zinc supply outlook for the first half of FY27. Higher refined output, supported by debottlenecking initiatives and additional roaster capacity, could provide greater production flexibility across downstream segments such as galvanising, infrastructure, automotive and alloys.
The sustained increase in production will remain an important factor for India’s zinc market, although the broader fundamental outlook will continue to depend on downstream demand, domestic buying patterns, treatment charges, inventory movements and international zinc prices in the coming months.
Leave a Reply