- Scrap prices remain supported by tight supply, limited import bookings
- Monsoon, approaching festivals, competitive sponge iron weigh on scrap demand
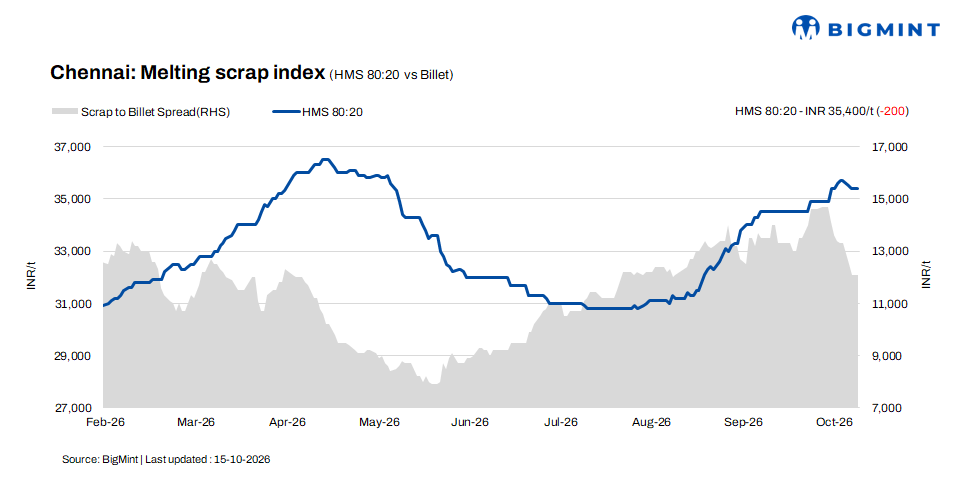
HMS (80:20) scrap prices in Chennai declined by INR 200/t w-o-w to INR 35,400/t on 15 October 2026 while remaining stable d-o-d, according to BigMint’s latest assessment. In the semi-finished steel segment, billet prices fell by INR 1,500/t w-o-w to INR 47,500/t, with no d-o-d change. Rebar prices also decreased by INR 500/t w-o-w to INR 52,500/t, remaining unchanged d-o-d.
Market sentiment remained cautious, with trade activity at moderate levels. Subdued steel demand, coupled with the onset of the monsoon and upcoming festivals, continued to weigh on market activity and procurement sentiment.
Imported, domestic market trends
Market participants reported that Australia-origin shredded scrap was offered at $385-390/t CFR Chennai, while HMS (80:20) was quoted at $370-375/t CFR. Buyers remained cautious, with bids trailing prevailing offers by around $10-15/t, resulting in a significant bid-offer gap. Despite the shortage of imported bookings, domestic scrap remained the more economical procurement option, limiting buying interest for imported material and keeping import trade activity muted in the Chennai market.

HMS (80:20) prices in the domestic market continued to trade within the INR 35,000-36,000/t range. Buyers offering payment with immediate terms were quoted INR 35,000-35,500/t, whereas prices increased to INR 35,500-36,000/t for extended payment terms. Supplier offers remained largely unchanged, and most transactions took place within the prevailing range. Market participants continued to factor in liquidity constraints and payment schedules when negotiating deals, reflecting a cautious procurement environment with payment conditions playing a significant role in price determination.
Buyer-supplier sentiments
A mill representative shared with BigMint that the Chennai scrap market is facing cautious buying interest as the monsoon season has already begun, while the approaching Ayudha Pooja and Dussehra festivals are expected to disrupt trading activity further next week. These seasonal factors are discouraging bulk bookings and keeping buyers focused on immediate requirements.
In addition, sponge iron prices have declined by around INR 1,500-1,800/t across the region, reducing the competitiveness of higher-priced metallic inputs. The representative expects this correction, alongside weak procurement interest, to exert pressure on ferrous scrap prices. Suppliers may need to revise offers downward in the coming days if market demand does not improve.
A leading scrap supplier shared with BigMint that HMS (80:20) scrap is trading at INR 35,000-36,000/t, with prices influenced by payment terms. Scrap prices remain broadly stable, supported by relatively tight availability. However, subdued billet and rebar demand is putting pressure on mills’ conversion economics and limiting buying interest.
With the monsoon season underway, finished-steel trading activity is likely to weaken further, potentially reducing scrap procurement in the coming days. Market participants expect finished-steel price movements to remain a key determinant of scrap pricing. If steel prices soften further, scrap prices could follow suit despite limited availability, as mills seek to manage costs amid subdued demand.
Outlook
Chennai’s ferrous scrap market is expected to remain largely stable with a slightly weak bias in the near term amid subdued steel demand and cautious buying. The onset of the monsoon season and upcoming festivals may further limit trading activity and bulk procurement. Recent declines in billet and rebar prices could exert additional pressure on scrap prices, while a recovery in downstream demand will be crucial for market improvement.
Leave a Reply