- Festive demand may support local scrap buying activity
- Elevated LME levels may limit aggressive import buying
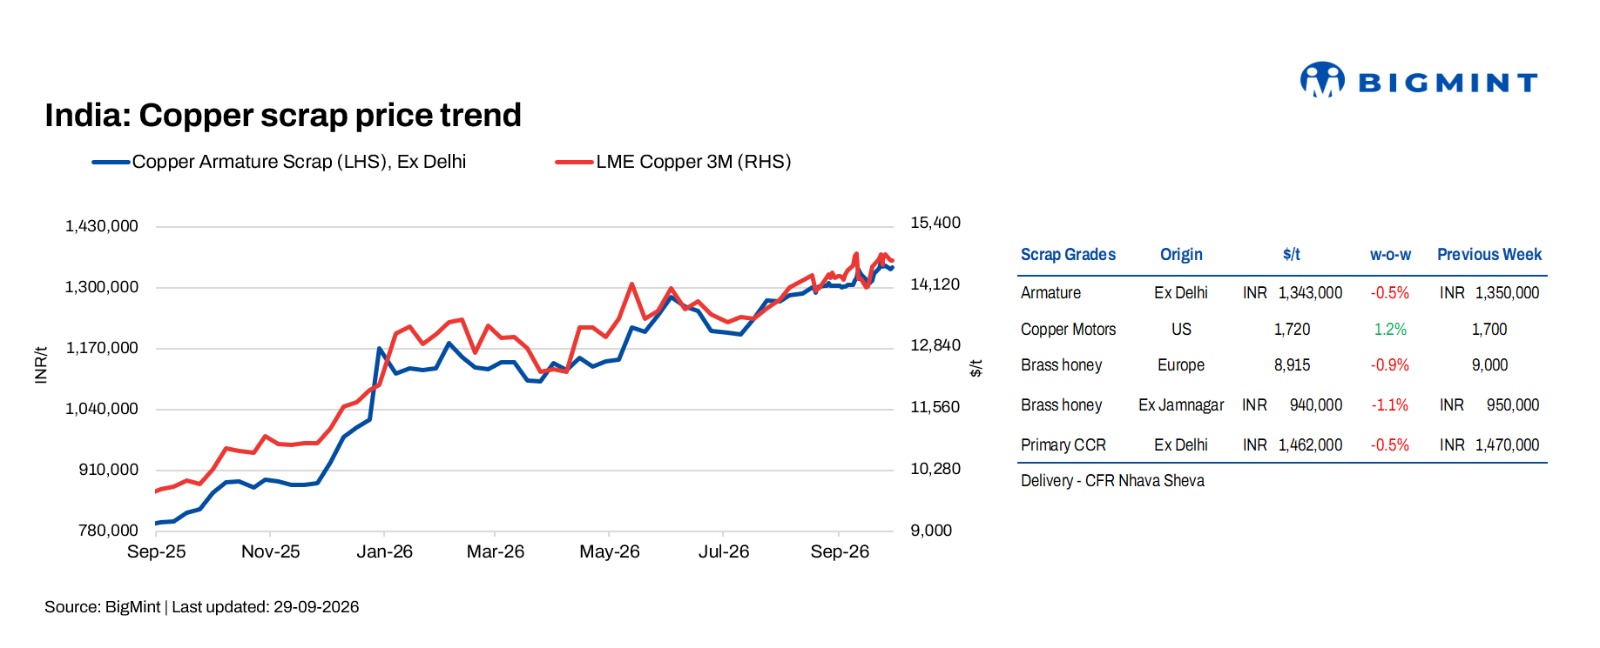
India’s imported copper scrap market remained firm during the assessment on 29 September 2026, supported by elevated London Metal Exchange (LME) copper prices, reduced spot availability from major exporting regions and improved domestic procurement ahead of the festive season.
LME copper was assessed at $14,470/t, remaining near record-high levels but declining from $14,700/t a week earlier.
As per BigMint’s assessment, copper armature scrap prices were heard at INR 1,343,000/t ex-Delhi, down from INR 1,350,000/t in the previous assessment.
Buyers become price-sensitive
The w-o-w decline was primarily driven by lower price acceptance among buyers. After copper prices traded close to record levels earlier this month, consumers have become increasingly reluctant to raise purchase bids with every move higher in the benchmark.
This trend is particularly evident in imported scrap, where elevated outright prices have increased working-capital requirements for Indian recyclers and secondary manufacturers. With margins under pressure, buyers are assessing shipment economics more closely and showing limited willingness to match aggressive seller offers.
Domestic buying improves ahead of festive season
Domestic markets, meanwhile, have shown firmer buying interest amid tighter availability. Copper armature scrap prices were reported at around INR 1,340,000-1,346,000/t, with transactions concluded within this range.
Buying activity has improved ahead of the festive season, with recyclers and secondary manufacturers increasing purchases for immediate requirements amid concerns over tighter imported availability and sustained strength in international copper prices.
Indian recyclers have become more active in securing immediately deliverable material, particularly armature and other high-copper-recovery grades, as replacement cargoes from overseas are taking longer to secure.
However, buyers remain cautious at LME levels above $14,000/t and are avoiding aggressive inventory building. For imported scrap, purchasing has therefore shifted towards smaller, requirement-based lots rather than large-volume stocking, particularly when suppliers are quoting China-linked premiums.
US-origin motors remain more competitive in Pakistan
In the copper motors scrap segment, mixed motors were heard traded at around $1,700-1,730/t CFR Nhava Sheva. In comparison, Pakistani buyers were reportedly securing similar material from the US at around $1,800-1,850/t CFR.
The resulting $100-150/t price differential is making India less competitive for US-origin motors and encouraging suppliers to divert cargoes towards Pakistan.
Indian buyers are resisting further price increases at current copper levels, while higher bids from Pakistan are allowing US suppliers to achieve better realisations. This is further tightening the availability of US-origin motors for Indian buyers.
Chinese demand limits availability of premium scrap
Physical availability of higher-recovery copper scrap has tightened as Chinese consumers continue to remain active in the international market. Stronger Chinese buying is absorbing material that could otherwise be offered to India and other Asian destinations.
Market participants indicated that exporters are increasingly prioritising China-bound sales where stronger demand and premiums are supporting better realisations, particularly ahead of the week-long holiday period in China.
Indian buyers are consequently finding it more difficult to secure premium imported grades such as Millberry and high-recovery wire scrap at workable levels. Some buyers have therefore reduced purchases to immediate processing requirements rather than building large inventories.
China remains a major driver of international copper scrap flows. The country imported 1.24 million tonnes of copper scrap in H1 CY26, up 8.3% y-o-y, as tighter domestic availability encouraged secondary producers to increase overseas sourcing. Scrap accounted for 25.2% of China’s refined copper feedstock during the period, compared with 22.5% a year earlier.
European market remains mixed
The European market remained uneven, with buying interest varying across regions and consumer segments. Improved local availability in some markets has given buyers greater negotiating leverage and weighed on premiums.
However, stronger Chinese procurement has limited the downside pressure by absorbing internationally available scrap units and reducing the volume of material competing for buyers in Europe and other destinations.
Offers
Millberry (US/EU origin): 101% of LME, CIF China
Millberry (US/EU origin): 99.25-99.5% of LME, CIF India
US/EU Candy Berry: 98.25% of LME, CIF China
US Candy Berry: 96.5% of LME, CIF India
US Birch Cliff: 93% of LME, CIF China
US Birch Cliff: 92% of LME, CIF India
UK Brass Honey: 61.25% of LME
Meatballs: $2,800-2825/t CFR India
Outlook
Indian copper scrap prices are expected to remain rangebound in the near term. Festive-season buying is likely to support domestic demand as recyclers and secondary manufacturers replenish inventories, particularly for high-recovery grades.
However, elevated LME prices are expected to keep buyers cautious towards imported material. Strong Chinese demand, higher competing bids from Pakistan and firm buying interest across the Far East could continue to restrict availability of exportable scrap.
At the same time, improved domestic procurement may encourage Indian consumers to favour locally available high-recovery material, providing support to domestic scrap prices and limiting the scope for further declines.
Leave a Reply