- Mill offers signal further increases ahead
- Demand remains steady across key markets
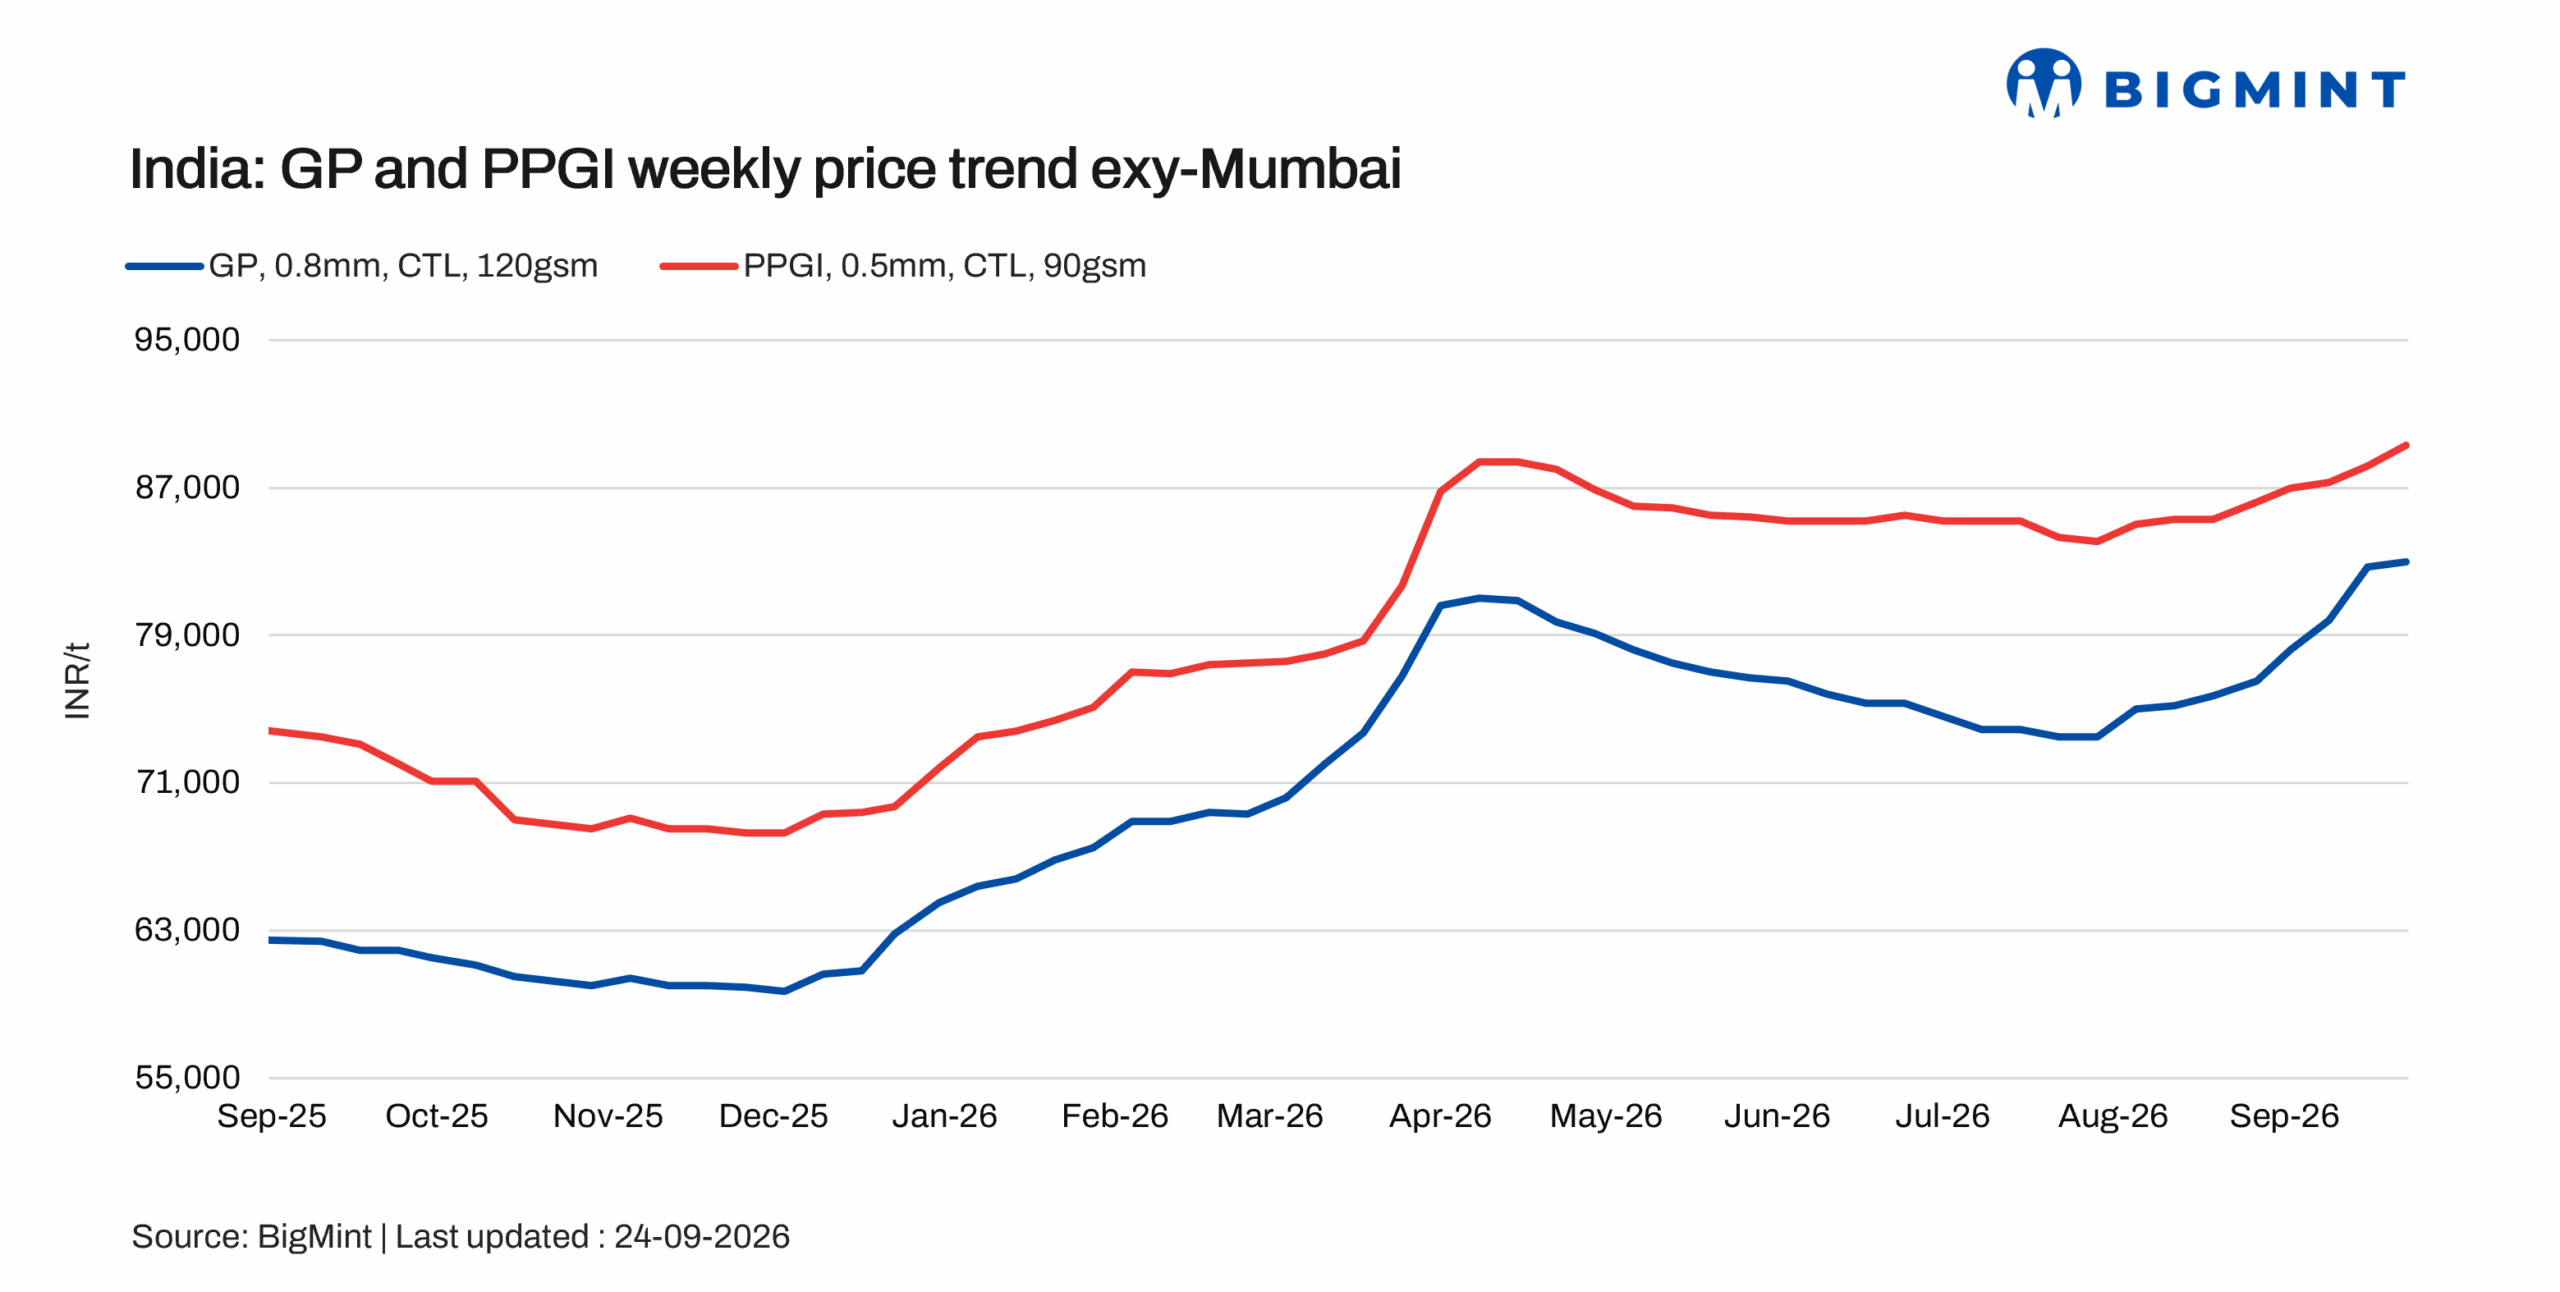
India’s coated flat steel trade-level prices increased by around INR 300-1,100/t w-o-w across products, following recent price hikes in HRC-CRC announced by major domestic steel mills. While trading activity remained relatively slow, the mill-led increases have influenced market prices, with buyers adjusting to the higher offer levels.
The rise in raw-material prices has also added cost pressure across the downstream segment, supporting the recent increase in coated steel prices. However, buying activity remains measured, with market participants largely purchasing according to immediate requirements.
Overall, the coated flat steel market has seen a modest uptick in prices w-o-w, supported mainly by higher mill offers and increased raw-material costs.
Price Update:

BigMint’s benchmark assessment for Mumbai Galvanized Plain (GP) coil (0.8 mm/CTL, 120 GSM, IS 277) increased by INR 300/t w-o-w to INR 83,000/t ex-Mumbai, from INR 82,700/t last week.
Mumbai Pre-painted galvanized iron (PPGI) (0.5 mm/CTL, 90 GSM, IS 14246) was assessed at INR 89,300/t ex-Mumbai, increasing by INR 1,100/t w-o-w from INR 88,200/t last week.
Meanwhile, Mumbai Galvalume (BGL) (0.5 mm/CTL, 1220 mm, AZ150) was assessed at INR 92,500/t ex-Mumbai, increasing by INR 700/t w-o-w from INR 91,800/t last week.
Raw material Prices:

India’s zinc ingot (99.995%) prices increased by INR 3,700/t w-o-w, with BigMint’s benchmark assessment at INR 438,700/t ex-Delhi, compared with INR 435,000/t in the previous week. The increase in zinc prices has added further cost pressure to the downstream coated steel segment.

BigMint’s bi-weekly benchmark assessment for Mumbai HRC (IS2062, Grade E250, 2.5-8 mm/CTL) increased by INR 200/t w-o-w to INR 63,900/t ex-Mumbai as of 22 September 2026.
Meanwhile, Mumbai CRC (IS513, Grade O, 0.9 mm/CTL) was assessed at INR 73,700/t ex-Mumbai, increasing by INR 500/t w-o-w from INR 73,200/t in the previous assessment.

Market Update:
India’s coated flat steel market remained relatively firm in the western and northern regions, with demand holding steady despite continued week-on-week price increases. The rise in coated steel prices has been driven mainly by higher HRC and CRC prices announced by major domestic mills, which have increased input costs for downstream coated products.
Inventory levels in the northern and western markets are estimated at around 70-80% of normal levels, while inventories in the southern market remain comparatively lower at around 60-70% of normal levels. The relatively lower availability, particularly in the south, is providing additional support to market prices.
Market indications suggest that major domestic mills are considering further price increases in the coming week. This could keep coated flat steel prices under upward pressure, with the extent of the increase depending on mill pricing and demand conditions.
Outlook
Coated flat steel prices are expected to move higher in the near term, with elevated zinc and other raw-material costs adding to production costs. Recent mill price revisions are likely to continue influencing trade levels, particularly as suppliers maintain higher offer prices.
Market indications suggest that major domestic mills may raise coated flat steel prices by around INR 1,500-2,000/t over the coming month. Buying may remain focused on immediate requirements, but limited material availability could provide additional support to prices.
Further price movement is likely to remain mill-led, with the extent of the increase depending on raw-material costs, mill offers, inventory availability and downstream purchasing activity.
Leave a Reply