- Monsoon weakness and buyer resistance weigh on southern trade
- Festival-related disruptions restrict trading activity in eastern markets
Indian cement trade prices showed a mixed trend in the week ended Oct 23, with regional demand, supply availability and buyer acceptance of price increases shaping market movements. Prices rose in parts of the North and Central regions, while subdued offtake and monsoon-related disruptions weighed on southern markets. Extended festive closures restricted trading activity in the East, while improved buying and local supply tightness provided support in parts of the West.
Regional price trends and market sentiment
West: Supply tightness supports market sentiment
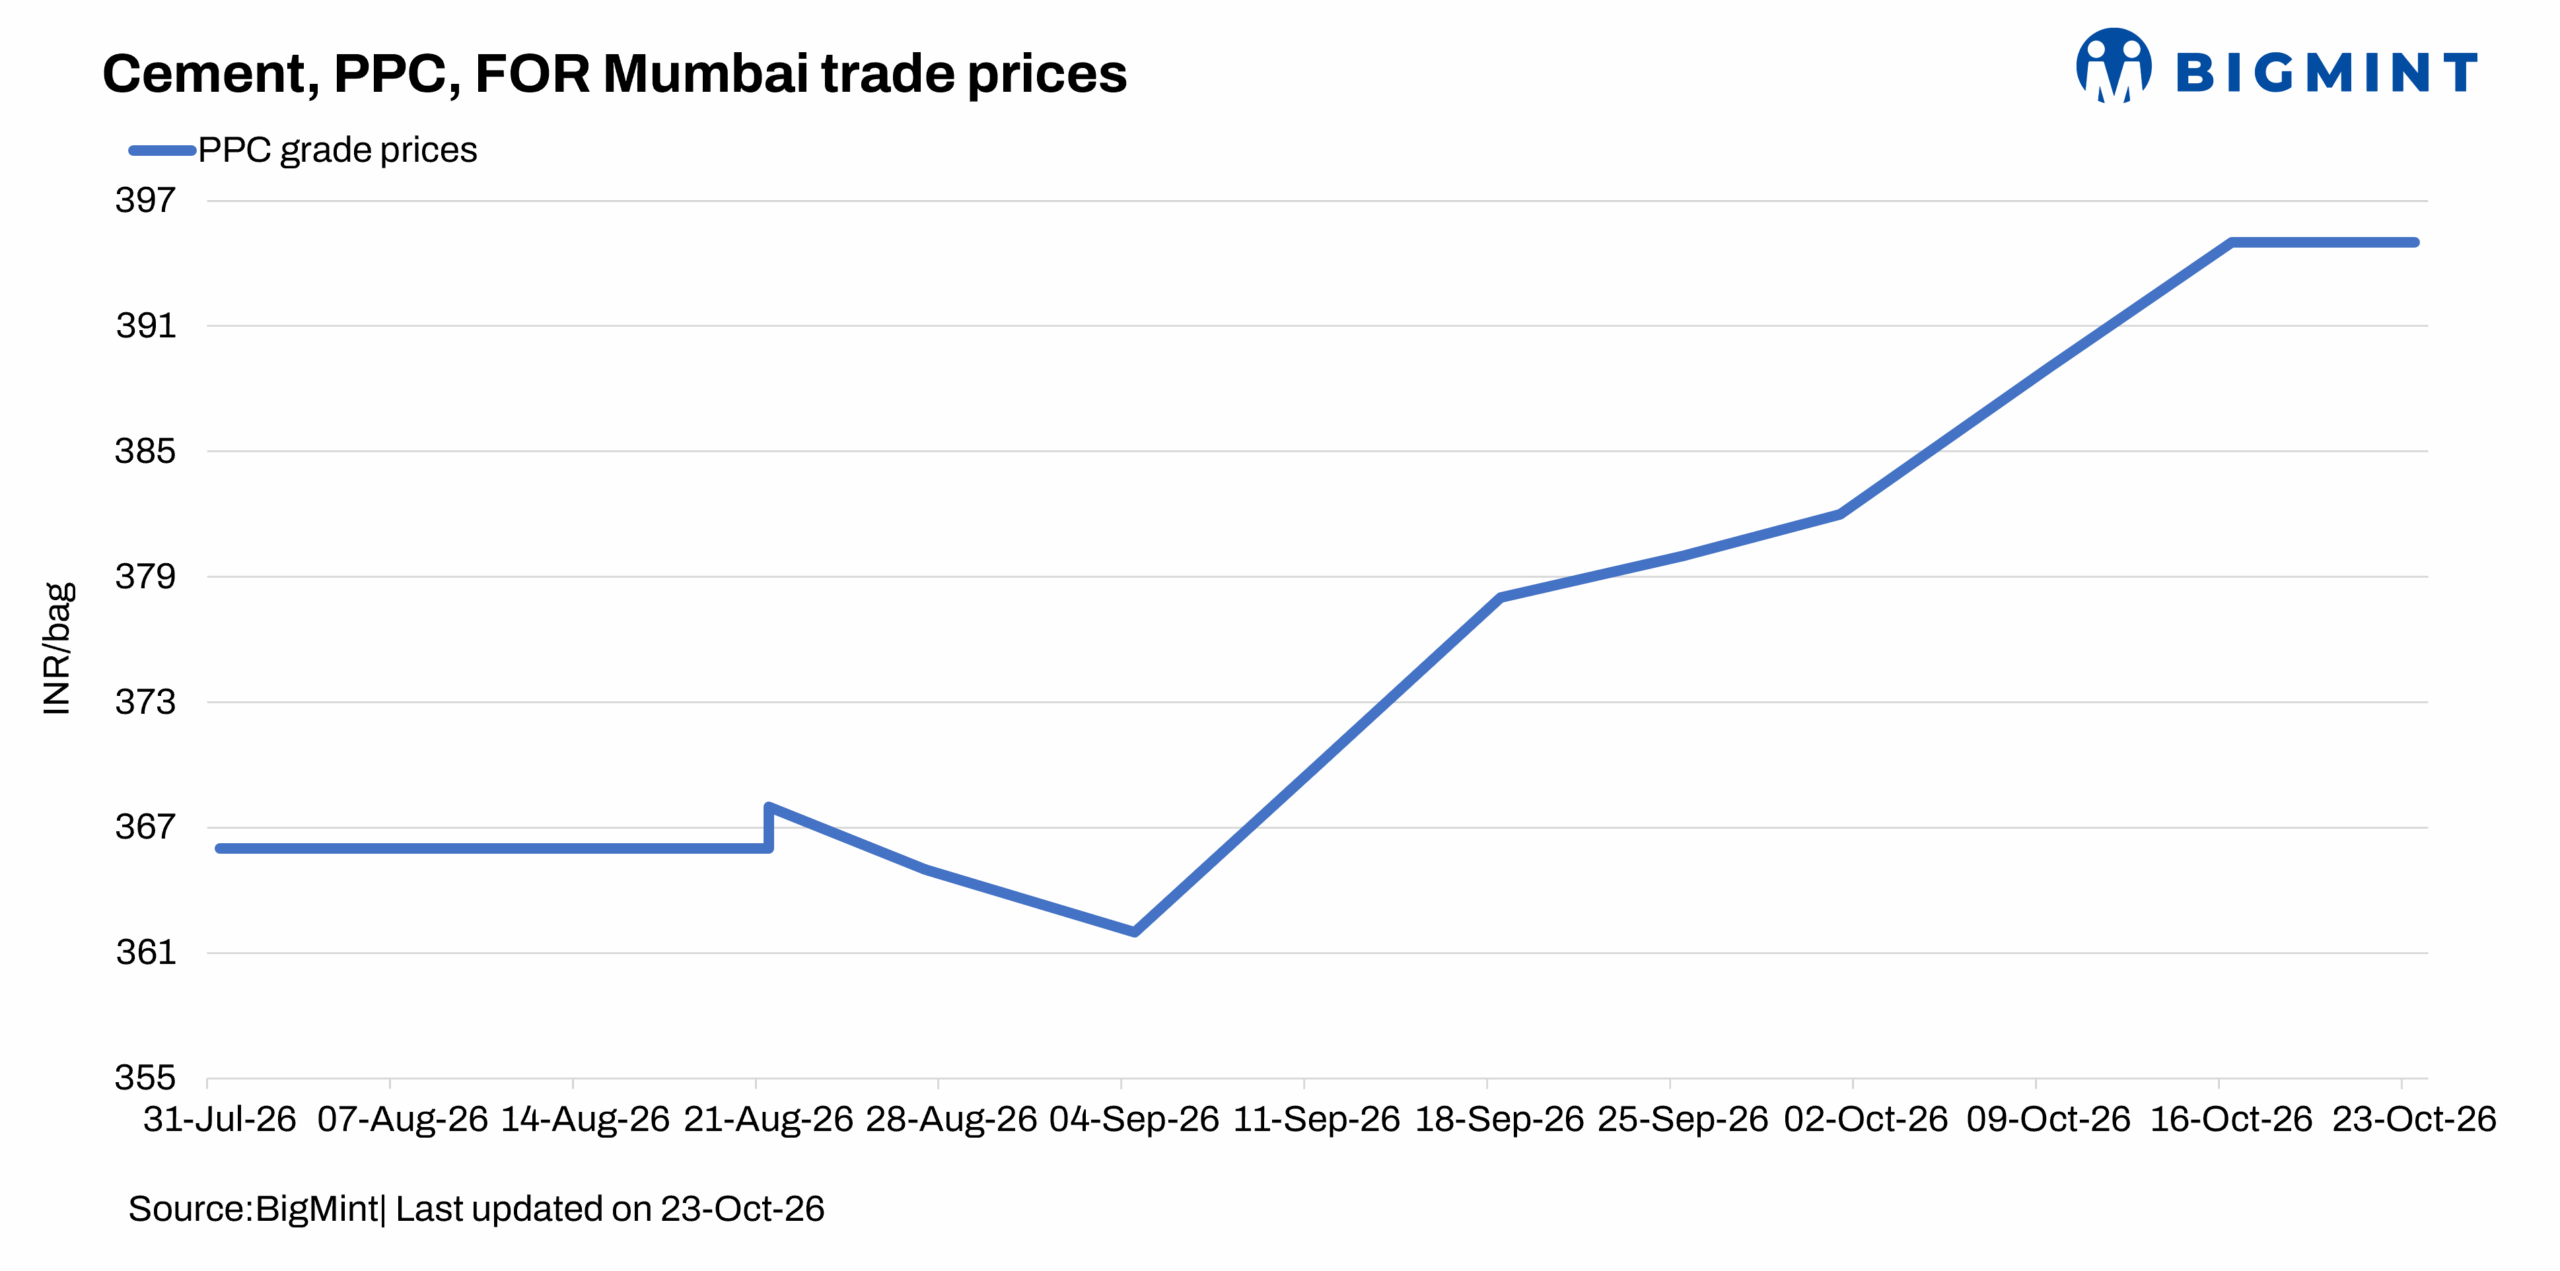
Western markets recorded mixed trends, with improved buying activity and material shortages supporting prices in selected locations. Cement trade prices remained stable w-o-w in Mumbai despite stronger dealer lifting and supply tightness. In Ahmedabad, improved post-festival buying supported market sentiment and kept prices firm.
East: Festive disruptions restrict trading activity
Trading activity remained subdued across eastern markets amid an extended festive period. Kolkata’s cement market remained largely inactive due to the post-Durga Puja slowdown and Lakshmi Puja. Limited market participation and restricted vehicle movement disrupted trading. Consequently, BigMint’s Kolkata Cement Price Assessment remained suspended on 23 October 2026.
South: Monsoon weakness and buyer resistance weigh on prices
Southern markets continued to face weak offtake and resistance to higher prices amid monsoon-related demand disruptions. Hyderabad trade prices declined by INR 4/bag w-o-w as subdued buying weighed on market sentiment. Chennai prices fell by INR 3/bag, reflecting weak demand and delayed market recovery following the Dussehra festive period.
In Bangalore, dealers attempted to raise prices, but weak demand limited their ability to pass on increases. Trade prices declined by INR 1/bag w-o-w to INR 384/bag.
Central: Producer hikes face buyer resistance
Raipur recorded the steepest weekly increase among the reported markets, with cement trade prices rising by INR 8/bag w-o-w to INR 286/bag following producer-led price revisions. However, the increase widened the gap between buyer bids and seller offers, as customers resisted higher prices and reduced lifting. Market sources indicated expectations of a further INR 10/bag increase in the coming days, although implementation and buyer acceptance remain uncertain.
North: Maintenance-related supply constraints support prices
Delhi trade prices increased by INR 2/bag w-o-w to INR 354/bag. Market sources reported strong demand across Delhi-NCR, while maintenance shutdowns at some major cement plants temporarily constrained supply. Pending orders and backlogs continued to support dispatches.
Anticipation of construction restrictions in Delhi from 1 November may also be encouraging some construction players to advance procurement and project execution ahead of the proposed measures.
Outlook
Cement prices could remain supported in selected markets as producers seek to pass on higher fuel costs and implement announced price increases. Imported pet coke prices rose to $190/t CNF Vizag in October from $167/t in September, while non-coking coal prices ex-Bilaspur increased by INR 300/t m-o-m to INR 6,500/t.
However, the extent of further price increases will depend on buyer acceptance and regional demand conditions. North and West markets have shown comparatively stronger buying support, while weak off take in the South and limited trading activity in the East could constrain price realizations. In Raipur, the ability of producers to sustain recent increases will depend on whether buyer resistance eases and trade volumes recover.
Leave a Reply