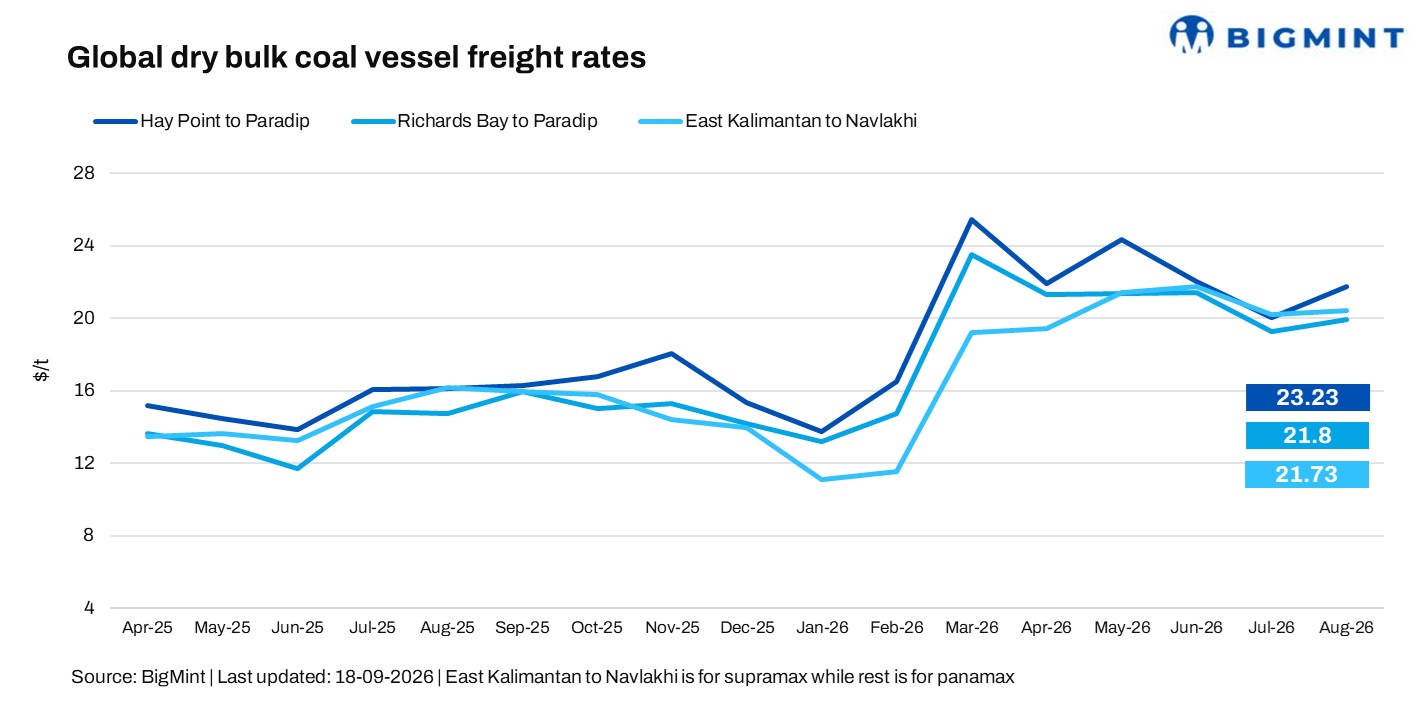
- Panamax stays supported as prompt tonnage remains tight
- Supramax activity picks up with fresh Pacific coal demand
India-bound coal freight markets remained firm but mixed in the week ended 18 September 2026. Panamax sentiment was supported by tighter prompt tonnage and steady India-bound enquiries, with South Africa-India gaining from firmer Atlantic activity.
Australia-India rates also remained firm, although charterers showed greater resistance to prevailing freight ideas. Supramax sentiment was more selective, with Indonesia-India rates declining as fixing remained limited and charterers resisted higher freight levels.

Panamax stays firm, but charterers turn cautious
Panamax sentiment remained firm on tighter prompt availability and steady India-bound coal demand. South Africa-India rates benefited from stronger Atlantic activity, while Australia-India continued to draw Pacific enquiries.
A shipbroker said, “Panamax rates are firm, although there are some signs of easing. Vessel availability and bunker prices remain key swing factors, with tighter tonnage supporting rates while weaker cargo enquiries could pressure freight.”
A charterer said, “Target freight levels are not being matched, leading to some delays in laycan decisions. The Pacific market is getting hotter, but buyers remain cautious about accepting higher levels.”
Supramax Pacific activity picks up
Supramax remained largely stable overall, although Indonesia-India activity was limited. The wider Pacific gained momentum as fresh coal cargoes entered the market, with around 10 new Supramax parcels reported, mainly for Indonesia-China trades.
A shipbroker said, “Around 10 fresh Supramax coal parcels have entered the Pacific market, mainly for Indonesia-China trades. The market could be hotter next week as cargo flow picks up, although fixing remains selective.”
A trader said, “Supramax remains firm, but the market is more or less flat for now. Vessel positioning and fresh cargo flow will decide the next move.”
Atlantic activity supports South Africa-India
Stronger cargo enquiries and tighter Atlantic tonnage supported South Africa-India freight, while firmer East Coast South America (ECSA) activity kept RBCT levels elevated. A shipbroker said, “RBCT is staying high as ECSA firms up. Stronger Atlantic enquiries and tighter tonnage are helping owners maintain firm ideas.”
The firmer Atlantic backdrop continues to support South Africa-India, while fuel costs and vessel availability remain key factors for freight sentiment.
Market highlights
- Baltic Dry Index (BDI) softens w-o-w: The BDI declined 5.3% (185 points) w-o-w to 3,336 as of 16 September, from 3,521 a week earlier, as weaker Panamax activity offset gains in the Supramax segment. Panamax fell 5.3% (127 points) to 2,282, reflecting softer demand and fixing activity, while Supramax rose 2.9% (49 points) to 1,762, supported by relatively firmer activity and tighter tonnage availability. The BDI snapped a five-session downtrend on 17 September, suggesting some stabilisation in the broader dry bulk market.
- Bunker prices ease after sharp mid-week gains: Singapore (Very Low Sulfur Fuel Oil) VLSFO prices eased to around $895/tonne (t) on 18 September, after climbing sharply from $877/t on 11 September and touching $906/t on 17 September. The recent volatility reflects continued uncertainty around fuel-oil supply and crude markets amid Middle East disruptions. While bunker availability has improved at major hubs, prices remain elevated, with Singapore VLSFO still more than double its level at the start of the year.
- Brent crude futures ease marginally w-o-w: Brent crude futures declined 0.4% ($0.41/barrel (bbl)) w-o-w to $103.44/bbl as of 18 September, from $103.85/bbl a week earlier. The marginal correction followed the sharp rally seen in the previous week, while ongoing Middle East tensions and disruption risks around the Strait of Hormuz continued to keep crude prices elevated. Elevated crude prices also continue to influence marine fuel costs and voyage economics.
- DCE coke futures extend losses w-o-w: January 2027 DCE coke futures fell 5.3% (RMB 110/t ($16.4/t)) w-o-w to RMB 1,952.50/t ($291.09/t) as of 18 September, from RMB 2,062.50/t ($307.54/t) a week earlier. The contract extended its downward trend for a second consecutive week, reflecting cautious market sentiment amid softer steel demand expectations and continued pressure on raw material markets.

Outlook
BigMint expects Panamax sentiment to remain firm but balanced, with tighter prompt tonnage and steady India-bound enquiries supporting owners’ ideas, while charterer resistance may cap gains. South Africa-India could retain support if Atlantic activity remains firm.
Supramax is likely to stay firm but selective, with fresh Pacific coal parcels supporting activity. Indonesia-India will depend on new cargo enquiries and vessel positioning, while bunker volatility remains a key swing factor.
Overall, the market could stay rangebound near term, with some softness possible towards late November-December if cargo momentum weakens.
Leave a Reply