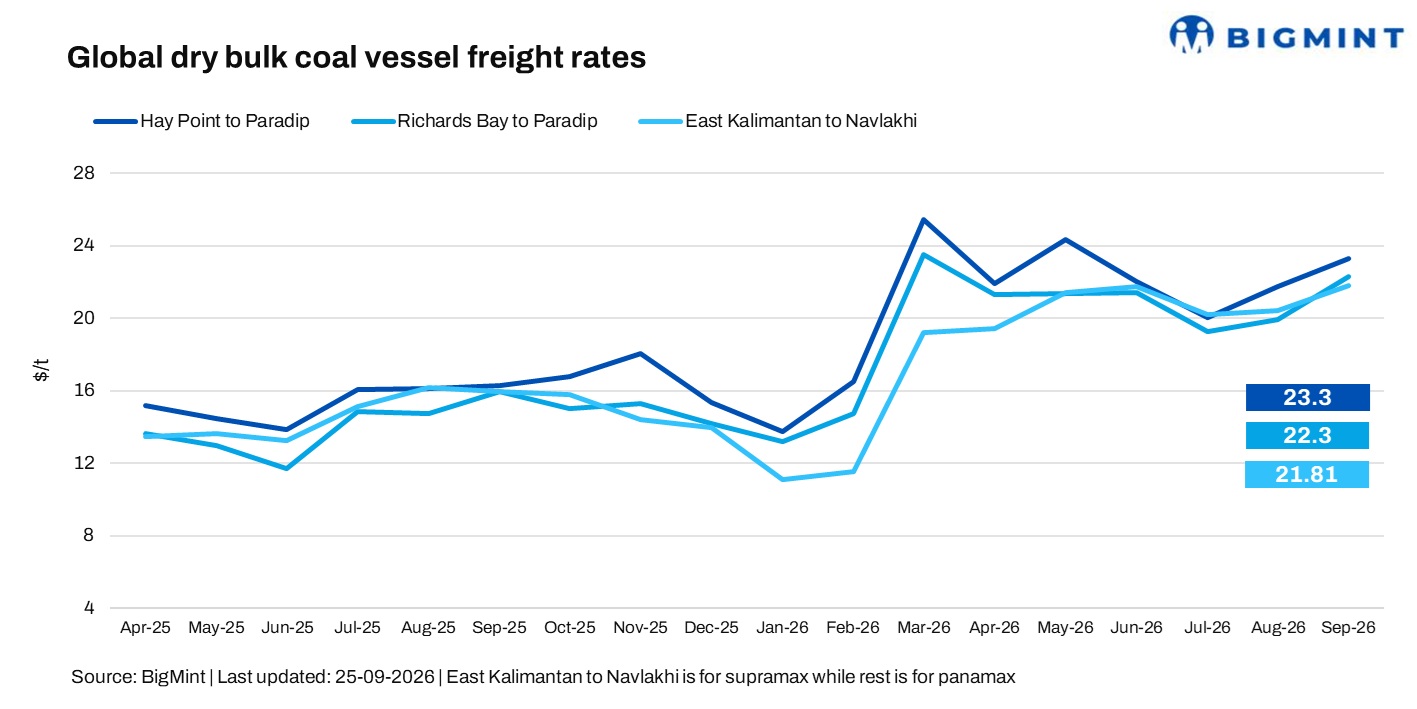
- Higher Panamax fixtures support rates despite thin Australia activity
- Supramax sentiment stays firm as holiday disruptions curb fresh fixing
India-bound coal freight markets turned firmer in the week ended 25 September 2026, with Panamax gaining momentum while Supramax held at higher levels despite limited physical activity. The approaching Asian holidays kept fresh cargo enquiry subdued across key Pacific loading regions, while firmer fixtures earlier in the week helped sustain owner rate ideas.

Panamax gains traction on firmer fixtures
The Panamax market started the week on a flat note before gaining traction as some vessels were fixed at higher levels. The firmer fixtures helped shift owner expectations, although fresh Australian enquiry remained thin ahead of the holidays.
A shipbroker told BigMint, “We have seen a hike in rates this week. The market started out flat, but some ships were fixed at higher rates, so I would say there has been a small increase.”
However, the physical market remained quiet, particularly in Australia. Another shipbroker said, “There have been no Supramax fixtures this week. The Panamax market has also been very quiet, with nothing from Australia at the moment due to the approaching holidays.”
Australian coal demand continues to provide a floor to Pacific sentiment, while many requirements have already been covered ahead of the Asian holidays, including Golden Week in China.
Supramax holds firm despite limited activity
Supramax trading remained thin through the week, but the market retained a firm undertone. Indonesian coal activity was relatively dull as participants moved closer to the holiday period, while higher levels seen earlier continued to underpin freight assessments.
A trader said, “The market remains firm despite slower activity. Indonesian coal movement has been relatively dull with the approaching Asian holidays, while bunker prices have also moved higher.”
The Pacific continues to draw support from Australian coal demand, although fresh cargo flow remains limited. Another market source mentioned, “Supramax freight rates have increased,” with vessel positioning and the return of fresh cargoes likely to shape the next move.
South Africa-India retains support
South Africa activity remained muted, with limited fresh fixing during the week. However, firmer levels established earlier and broader Atlantic vessel positioning continued to support owner ideas on the India-bound route.
Market highlights
- Baltic Dry Index (BDI) recovers w-o-w: The BDI increased 4.1% (137 points) w-o-w to 3,473 as of 24 September, from 3,336 a week earlier, supported by gains in both the Panamax and Supramax segments. Panamax rose 4.4% (100 points) to 2,382, indicating firmer demand and fixing activity, while Supramax increased 1.1% (20 points) to 1,782, reflecting a modest improvement in market conditions.
- Bunker prices remain elevated: Singapore Very Low Sulfur Fuel Oil (VLSFO) stood at around $904/tonne (t) on 25 September, compared with $895/t on 18 September, amid continued volatility in fuel-oil supply, crude markets and Middle East disruptions. While availability has improved at major hubs, elevated bunker costs and Middle East-related uncertainty continue to influence voyage economics and freight ideas.
- Brent crude futures rise w-o-w: Brent crude futures increased 1.4% ($1.50/bbl) w-o-w to $104.94/barrel (bbl) as of 25 September, from $103.44/bbl a week earlier. Ongoing Middle East tensions and disruption risks around the Strait of Hormuz continued to support crude prices, keeping marine fuel costs and voyage economics under focus.
- DCE coke futures edge lower w-o-w: January 2027 Dalian Commodity Exchange (DCE) coke futures fell 3.9% (RMB 78/t; $11.63/t) w-o-w to RMB 1,974.50/t ($294.20/t) as of 25 September, from RMB 2,052.50/t a week earlier, amid cautious market sentiment and softer steel demand expectations.

Outlook
BigMint expects Panamax sentiment to remain supported, although the holiday period could keep fresh Australian enquiry limited in the near term. The return of cargoes after the holidays, alongside prompt vessel availability, will be key to the next move. Supramax is likely to remain firm but selective, with limited Indonesian activity keeping fixing subdued in the short term. Fresh cargo flow and vessel positioning will remain central to the market once holiday-related disruptions ease.
Overall, freight sentiment has turned firmer, but the market still lacks strong fresh cargo momentum. The post-holiday return of enquiries will be crucial in determining whether the current levels can be sustained.
Leave a Reply