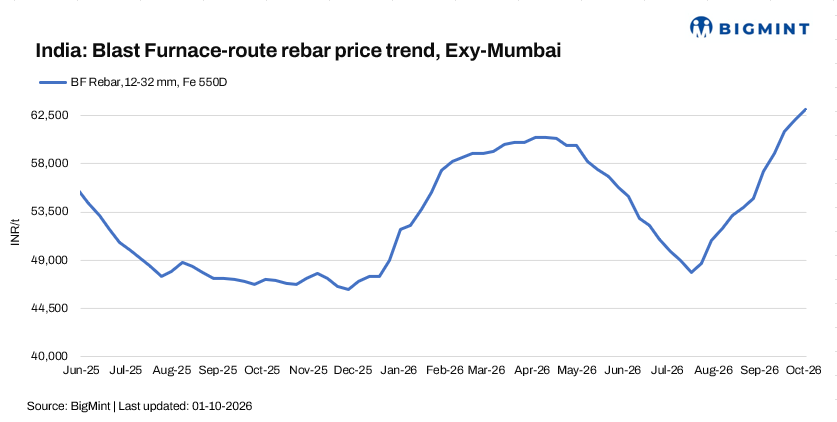
- Improving project demand, festive-season restocking lift prices
- IF rebar prices increase amid higher iron ore, coal costs
India’s trade-level blast furnace (BF)-route rebar prices rose by INR 1,000/t ($10/t) w-o-w to INR 63,000/t ($655/t) ex-Mumbai, according to BigMint’s assessment on 30 September 2026.
BF-route rebar prices increased by around INR 6,500/t m-o-m in September, supported by tighter availability, lean inventories and improving project demand.
Project prices were reported at around INR 62,000-64,000/t ($644-665/t) landed. Market participants reported stronger project enquiries and improved booking activity, with buyers increasingly securing material for near-term requirements amid expectations of further price increases.
A leading Indian steelmaker raised rebar list prices by INR 1,500/t ($15/t) for early-October deliveries. Following this increase, the company has raised prices by INR 4,500/t during September, taking the cumulative increase across September and early October to INR 6,000/t.
Distributor buying has also started to recover as the monsoon season nears its end and construction activity gradually improves. Market participants said distributors are beginning to replenish stocks ahead of the festive season, providing additional support to overall rebar demand.
Factors driving the market
Low inventories strengthen sellers’ pricing position
BLast furnace-route rebar inventories across the supply chain remain at very low levels, restricting the availability of readily deliverable material. The tight inventory position has strengthened mills’ pricing stance and encouraged buyers to cover immediate requirements despite elevated prices.
The current market environment differs from earlier periods when relatively high inventories and weak consumption limited price gains. With stocks now significantly leaner, even a moderate improvement in buying interest is translating into quicker gains in spot prices.
Project enquiries improve, mills remain selective on bookings
Project demand has strengthened with the gradual easing of monsoon-related disruptions and the corresponding improvement in construction activity. Buyers are increasingly looking to secure material for ongoing projects as well as upcoming requirements.
Despite stronger enquiries, mills remain selective in committing to large project volumes at prevailing prices. Market participants expect prices to remain firm, prompting some mills to restrict fresh project bookings, while others are yet to announce revised project prices.
This has kept the project market relatively tight, with buyers showing greater willingness to lock in volumes while mills remain cautious about forward commitments.
Mills focus on improving product-level price realisation
With availability remaining constrained, mills are also focusing on improving product-level price realisation. The combination of lean inventories, improving enquiries and firm mill offers is providing support to current rebar price levels.
IF-route rebar prices rise
IF-route rebar prices increased by INR 400-2,800/t w-o-w across major markets, with the sharpest hikes recorded in Delhi and Bengaluru at around INR 2,800/t and INR 2,500/t, respectively.
The upward movement was primarily supported by higher key raw material costs, particularly iron ore and coal, which increased input costs for producers and lifted finished steel offers. However, buying activity remained moderate, with no significant improvement in ground-level demand.
The market outlook remains positive but range-bound, as higher price levels continue to face limited acceptance from buyers. Market participants are largely adopting a wait-and-watch approach, with procurement restricted to immediate requirements. Further price movement will largely depend on raw material trends and any improvement in underlying steel demand. Meanwhile,the price differential between BF- and IF-route rebar in Mumbai widened further w-o-w to around INR 10,000/t ($100/t). IF-route rebar continues to account for an estimated 65-70% share of India’s overall rebar market.
Raw material costs provide mixed signals
BigMint’s Odisha iron ore fines (Fe 62%) index increased by INR 300/t w-o-w to INR 5,500/t ex-mines as of 26 September.
Meanwhile, premium hard coking coal (PHCC) prices remained stable w-o-w at $296/t CNF Paradip.
The rise in iron ore costs provides some upward cost pressure for BF-route producers, while stable coking coal prices have limited additional pressure from key raw materials.
Project details
NHAI: Four projects worth around INR 8,611 crore, including G R Infraprojects’ INR 4,263 crore Agra-Gwalior project and Dilip Buildcon’s INR 3,653 crore Pagote-Chowk highway project.
Water & irrigation: Projects worth around INR 1,123 crore, led by NCC’s INR 1,077 crore Yeleru Reservoir water scheme.
Buildings: Vascon Engineers’ INR 661 crore Bengaluru office project and NBCC’s INR 215 crore Delhi infrastructure project.
Power & telecom: Vikran Engineering and Bondada Engineering secured orders worth around INR 301 crore.
Outlook
With inventories remaining lean, project enquiries improving and distributors gradually returning to the market, BF-route rebar prices are likely to remain supported in the near term. However, the pace of further price gains will depend on the sustainability of construction demand, mill booking availability and movements in key raw material costs.
Leave a Reply