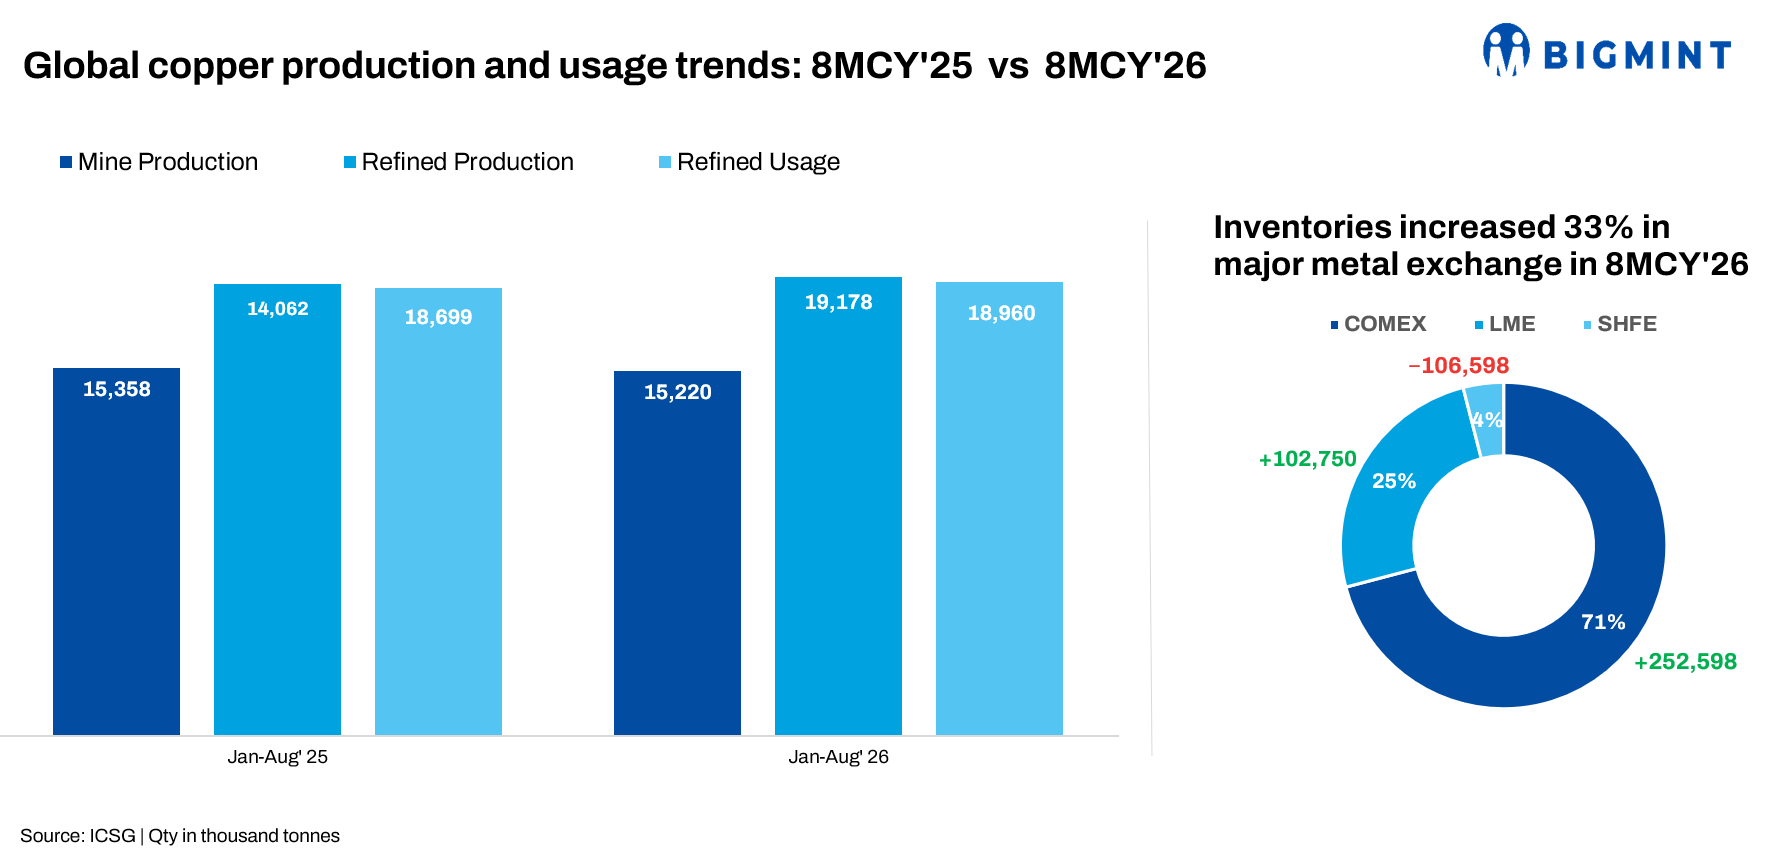
- Global refined copper production rises 1.7% y-o-y as secondary output grows 5.3%
- World mine production declines 0.9% y-o-y, while concentrate output falls 1.9%
The global refined copper market recorded a preliminary surplus of 218,000 t during January-August 2026, compared with 158,000 t in the same period last year, according to the International Copper Study Group (ICSG). After adjusting for estimated changes in Chinese bonded stocks, the surplus narrowed to 181,000 t, indicating a smaller underlying surplus than the headline balance suggests.
Global refined copper production increased 1.7% y-o-y during the first eight months of 2026. Higher output in China and the Democratic Republic of Congo (DRC), alongside stronger secondary production from scrap, supported growth. However, declining mine supply and operational constraints at Chilean smelters continued to weigh on the broader supply chain.
Mine supply remains under pressure
World copper mine production declined 0.9% y-o-y during January-August 2026. Concentrate production fell 1.9%, partly offset by a 2.7% increase in solvent extraction-electrowinning (SX-EW) output. Although projects ramping up across several countries added supply, disruptions in Chile, Indonesia and the DRC limited overall production.
Chile’s mine output declined 7%, mainly due to reduced production at El Teniente, Escondida and Spence. Concentrate production fell 9.3%, while SX-EW output increased 0.5%.
In Indonesia, concentrate production declined an estimated 29% as operations at Grasberg remained constrained following the severe mud-rush incident in September 2025. Mine production in the DRC fell an estimated 1%, as a 26% decline in concentrate output linked to reduced production at Kamoa offset 4.5% growth in SX-EW output.
Elsewhere, Peru’s mine production increased 1.3%, supported by higher output at Antamina. Mongolian concentrate production rose around 20% as the Oyu Tolgoi underground project continued ramping up. In contrast, Australian mine output declined an estimated 10%, mainly following the closure of Mount Isa in July 2025.
Secondary production supports refined output growth
Despite weaker mine supply, global refined copper production increased 1.7% y-o-y during 8MCY’26. Primary refined production rose 1%, while secondary production from scrap increased 5.3%, mainly driven by higher output in China.
China and the DRC remained the principal sources of refined production growth. Their combined output increased 4.3%, with China rising 4.2% and the DRC gaining 4.5%. Together, the two countries accounted for around 59% of global refined copper production. Excluding them, global refined output declined approximately 1.7%.
India’s refined copper production increased an estimated 23%, supported by improved operating rates and the ramp-up of the Adani refinery. In contrast, Chilean refined production fell 7.6%, as electrolytic production from concentrates declined 24% amid smelter maintenance and operational constraints. Electrowinning output in Chile increased 0.5%.
Refined production in Asia excluding China declined an estimated 1.7%, as lower output in Japan, Indonesia and the Philippines outweighed growth elsewhere in the region.
Demand growth remains concentrated in China
World apparent refined copper usage increased 1.4% y-o-y during the first eight months of 2026. Chinese apparent demand rose 2.8%, while usage outside China declined 0.6%. Meanwhile, China’s net refined copper imports fell 12%, indicating a weaker contribution from imported refined metal.
China accounted for approximately 59% of global refined copper usage during the period. Its demand performance therefore remained central to the global market balance, while declining consumption outside China limited overall demand growth.
The faster growth in refined production compared with usage widened the preliminary market surplus to 218,000 tonnes, up from 158,000 t a year earlier. However, the adjusted surplus stood at 181,000 tonnes after accounting for an estimated 37,000-tonne decline in Chinese bonded stocks from end-2025 levels.
Exchange inventories remain high
Visible copper inventories continued to rise, with combined stocks across the London Metal Exchange (LME), COMEX and Shanghai Futures Exchange (SHFE) reaching 992,865 tonnes at end-September 2026. This marked the highest level since June 2003.
Combined exchange stocks increased by 248,750 tonnes, or approximately 33%, from end-December 2025. COMEX recorded the largest increase, with stocks rising by 252,598 tonnes. LME inventories increased by 102,750 tonnes, while SHFE stocks declined by 106,598 tonnes.
The divergent exchange movements indicate that the inventory build-up was concentrated in COMEX and LME warehouses, while SHFE stocks contracted. Nevertheless, the overall increase in visible inventories highlights the availability of substantial above-ground stocks despite weaker mine supply.
Copper prices elevated
Copper prices remained firm in September despite rising exchange inventories. The average LME cash price increased 0.9% month-on-month to $14,483.39/t, compared with $14,353.40/t in August, according to ICSG.
The LME copper price reached a 2026 high of $14,768/t on 10 September before experiencing subsequent fluctuations. The year-to-date average stood at $13,520/t through the period covered by the October release, approximately 36% above the 2025 annual average.
The combination of elevated prices and rising exchange inventories points to a market in which visible stock accumulation has not fully translated into sustained price weakness. However, the widening refined copper surplus suggests that supply growth continues to outpace apparent demand, even as declining mine output and regional production constraints provide support to the market.
Outlook
The global refined copper market is likely to remain in surplus in the near term, with refined production growth continuing to exceed demand growth. Higher secondary production and expanding output in China, the DRC and India could support supply, although persistent mine disruptions and constrained concentrate availability remain important risks.
Elevated exchange inventories could limit further price gains if demand fails to accelerate. However, China’s dominant share of global copper consumption, declining mine production and lower Chinese bonded stocks will remain key factors shaping the market balance and price direction in the coming months.
Leave a Reply