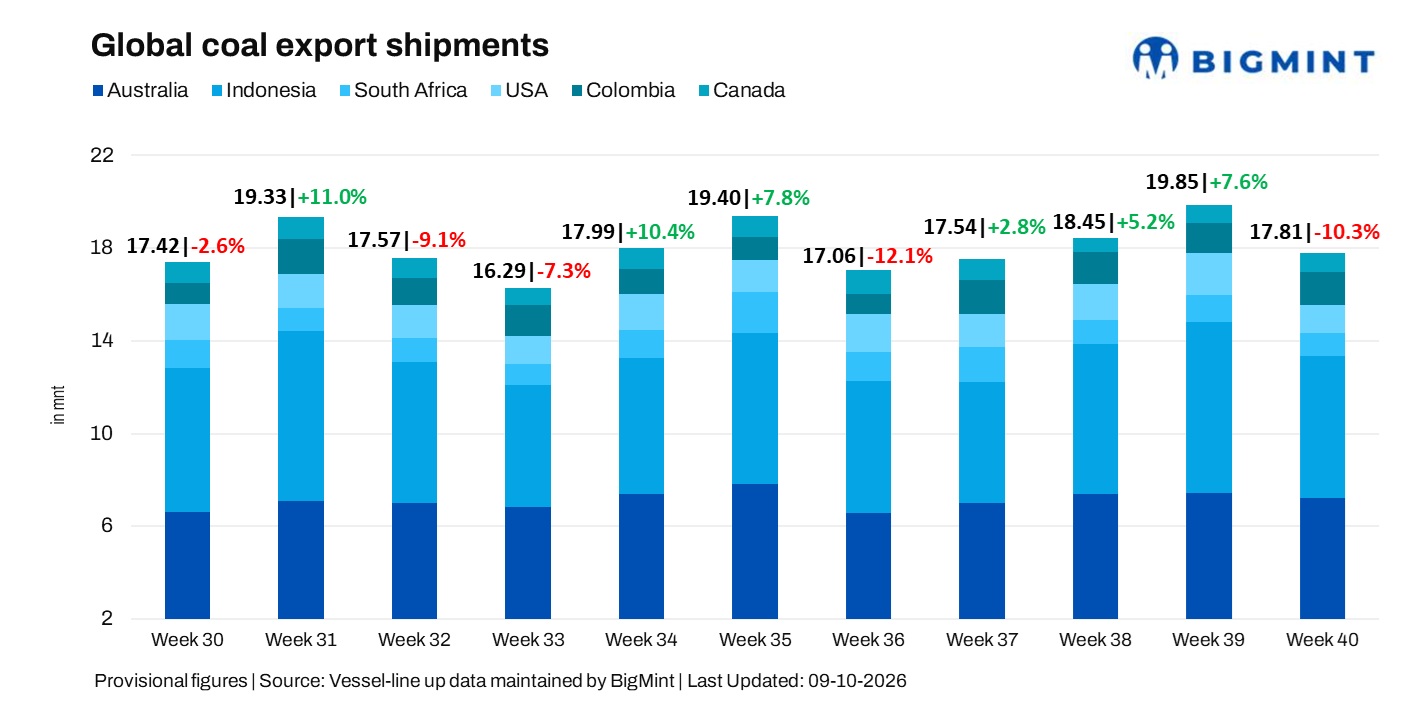
- Softer Indonesian and US volumes drag global coal exports lower
- Colombia and Canada post gains as Australian flows ease marginally
Global seaborne coal exports fell 10.3% w-o-w to 17.81 million tonnes (mnt) in week 40 (26 September-2 October 2026), as lower volumes from Indonesia, the US, South Africa and Australia weighed on overall trade flows. Indonesia and the US recorded the steepest declines among major exporters, offsetting gains from Colombia and Canada.
Australia remained the largest exporter at 7.23 mnt, followed by Indonesia at 6.10 mnt. Colombia and Canada bucked the broader trend, with stronger export volumes providing partial support amid weaker shipments across other key suppliers.
Country-wise exports

Port-wise exports
Australia, Indonesia dominate Pacific coal flows
- Australia exported 7.23 mnt, led by Newcastle at 2.74 mnt, Gladstone at 1.52 mnt and DBCT at 1.36 mnt. China (2.93 mnt) and Japan (1.09 mnt) were the top destinations, while Glencore (0.97 mnt) and BHP (0.71 mnt) led shipper activity.
- Indonesia exported 6.10 mnt, with Samarinda (0.89 mnt), Bunati (0.71 mnt), Muara Pantai (0.61 mnt) and Taboneo (0.60 mnt) as key ports. India (1.59 mnt), China (1.21 mnt), the Philippines (0.77 mnt) and South Korea (0.46 mnt) were the leading destinations. Bukit Asam (0.54 mnt), Kaltim Prima Coal (0.53 mnt) and Jhonlin Group (0.52 mnt) led shipper activity.
- Canada exported 0.86 mnt, with Roberts Bank at 0.41 mnt, Vancouver at 0.29 mnt and Prince Rupert at 0.16 mnt. South Korea (0.34 mnt), Indonesia (0.16 mnt) and Hong Kong (0.15 mnt) were the leading destinations, while Elk Valley Resources accounted for 0.29 mnt.
Colombia, South Africa and US contribute to Atlantic flows
- Colombia exported 1.41 mnt, with Prodeco Group accounting for 0.84 mnt and Cerrejón Mines 0.53 mnt. The Netherlands (0.50 mnt) was the leading destination, followed by Mexico (0.13 mnt) and Brazil (0.10 mnt).
- South Africa exported 1.02 mnt, entirely through Richards Bay. India (0.35 mnt) and Pakistan (0.20 mnt) were the leading reported destinations, with rail-linked deliveries and terminal availability remaining key factors.
- US exports stood at 1.19 mnt, led by Norfolk (0.47 mnt), Baltimore (0.30 mnt) and Mobile (0.21 mnt). India was the leading reported destination at 0.42 mnt, amid weaker overall exports.
India-bound coal freight stays mixed amid subdued fixing activity
India-bound coal freight markets remained mixed, with tight tonnage supporting owners’ rate ideas despite limited cargo enquiries. Panamax activity on the Australia-India route remained selective, while Supramax sentiment on the Indonesia-India route drew support from restricted vessel availability.
South Africa-India activity remained subdued, with vessel positioning and elevated bunker costs influencing freight negotiations. The gap between owners’ expectations and charterers’ workable levels continued to limit fresh fixtures.
Outlook
Global coal exports may remain uneven in the coming week, with Australian loading activity and Indonesian supply availability likely to influence Pacific flows. US volumes and Colombian rail operations will remain important watchpoints, while South African exports will depend on rail-linked deliveries and terminal availability.
In freight, Panamax sentiment will hinge on fresh Australian cargo enquiries and vessel availability, while Supramax rates will remain sensitive to Indonesian demand and tonnage positioning. With fixing activity subdued, the gap between owners’ rate ideas and charterers’ workable levels could continue to limit transactions. Bunker costs will also remain a key factor shaping freight negotiations.
Leave a Reply