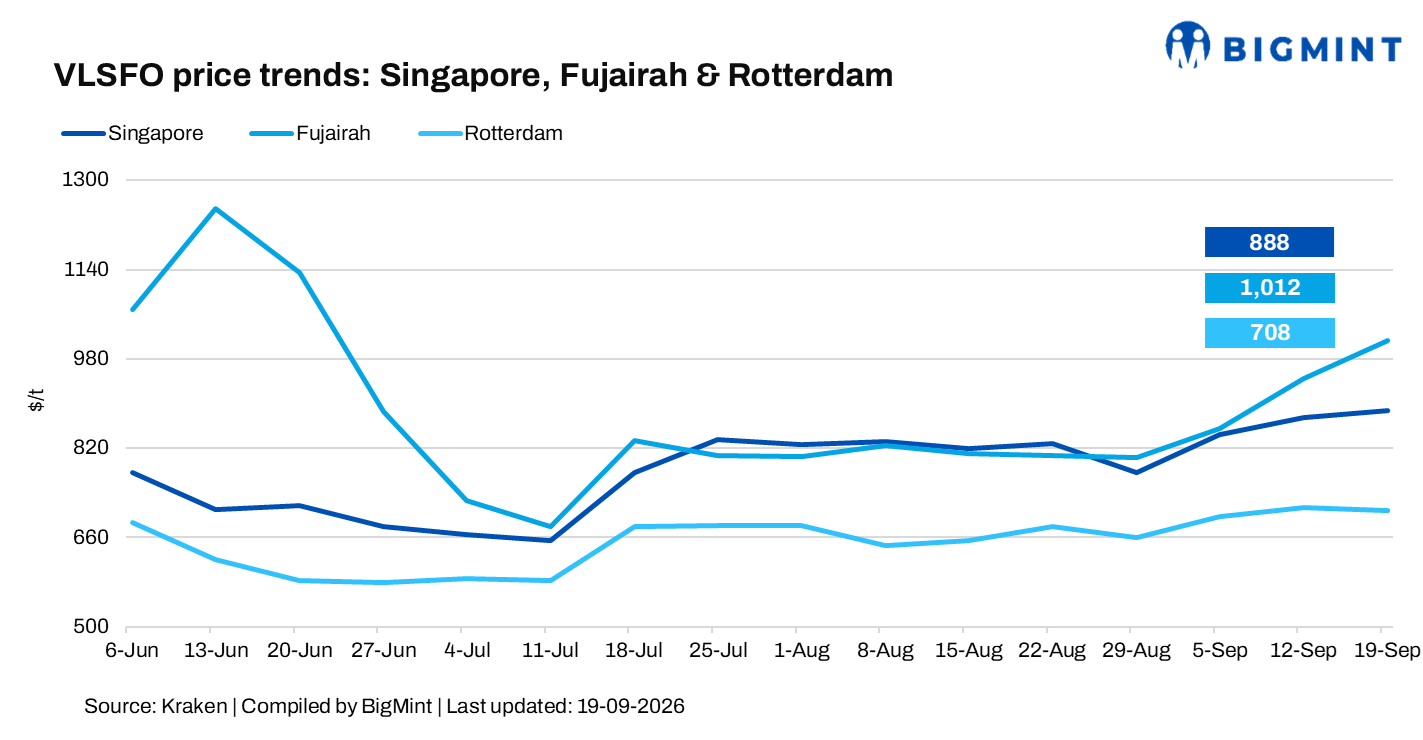
- Fujairah records sharpest gains across all three fuel grades
- MGO posts the strongest absolute increase as crude remains above $100/bbl
Global bunker prices increased across most major hubs in the week ended 19 September 2026, with Fujairah recording the strongest gains. Marine Gas Oil (MGO) saw the largest absolute increases, while Very Low Sulphur Fuel Oil (VLSFO) and High Sulphur Fuel Oil (HSFO) also strengthened in Singapore and Fujairah. Rotterdam was comparatively stable, with VLSFO and HSFO edging lower. The mixed regional movement came as crude prices remained elevated amid Middle East supply risks, although easing concerns over Saudi disruptions and alternative supply routes capped the oil-price upside.

Regional bunker markets
- Singapore: VLSFO increased $14/tonne (t) (1.6%) w-o-w to $888/t, while MGO and HSFO rose sharply. The broad-based increase indicates continued upward pressure on regional fuel replacement costs despite the recent easing in crude prices.
- Rotterdam: VLSFO declined $5/t (0.7%) to $708/t, while MGO rose and HSFO was broadly stable. The divergent movement reflects relatively softer fuel-oil pricing compared with continued strength in middle-distillate markets.
- Fujairah: VLSFO recorded the largest weekly increase, rising $68/t (7.2%) to $1,012/t. MGO and HSFO surged w-o-w. The sharp gains underline continued sensitivity to regional supply and shipping risks around the Middle East. Current bunker-market data also shows Fujairah maintaining a premium over Singapore and Rotterdam for VLSFO and MGO.
Market factors
- Brent crude eases marginally: Brent futures declined $0.41/barrel (bbl) (0.4%) w-o-w to $103.44/bbl on 18 September from $103.85/bbl. Crude remained elevated as Middle East supply disruptions continued to pose risks, while expectations of alternative supply routes and improving Saudi flows limited further gains.
- WTI crude falls: WTI crude futures fell to $99.4/bbl on 19 September 2026, from $100.05/bbl in the previous week, declined $0.65/bbl (0.6%) w-o-w. Despite the weekly decline, oil prices remained around the $100/bbl threshold amid continued geopolitical uncertainty and supply-chain disruptions in the region.
Outlook
Global bunker prices are likely to remain elevated and volatile in the near term, with Middle East supply risks, crude prices and regional fuel availability remaining key drivers. Fujairah is likely to remain particularly sensitive to regional disruptions, while MGO could retain upward pressure given its stronger recent gains. Any improvement in Middle East shipping and crude flows could ease the risk premium, but persistent disruptions would continue to support bunker prices.
Leave a Reply