- MGO declines sharply across all hubs, led by Rotterdam and Fujairah
- VLSFO falls, while HSFO shows mixed regional movements
Global bunker prices declined broadly across Very Low Sulphur Fuel Oil (VLSFO) and Marine Gas Oil (MGO) markets in the latest week, while High Sulphur Fuel Oil (HSFO) movements remained mixed across Singapore, Rotterdam and Fujairah. The decline in middle-distillate prices indicated some easing in crude-oil price pressure.
Middle-distillate supply remains a key risk despite lower MGO prices during the week, refined-fuel markets remain vulnerable to supply disruptions. China’s suspension of fuel exports beyond Hong Kong and Macau has tightened Asian refined-product availability, while ongoing disruptions to regional refinery and shipping activity continue to support elevated diesel-market risks.

Regional bunker markets
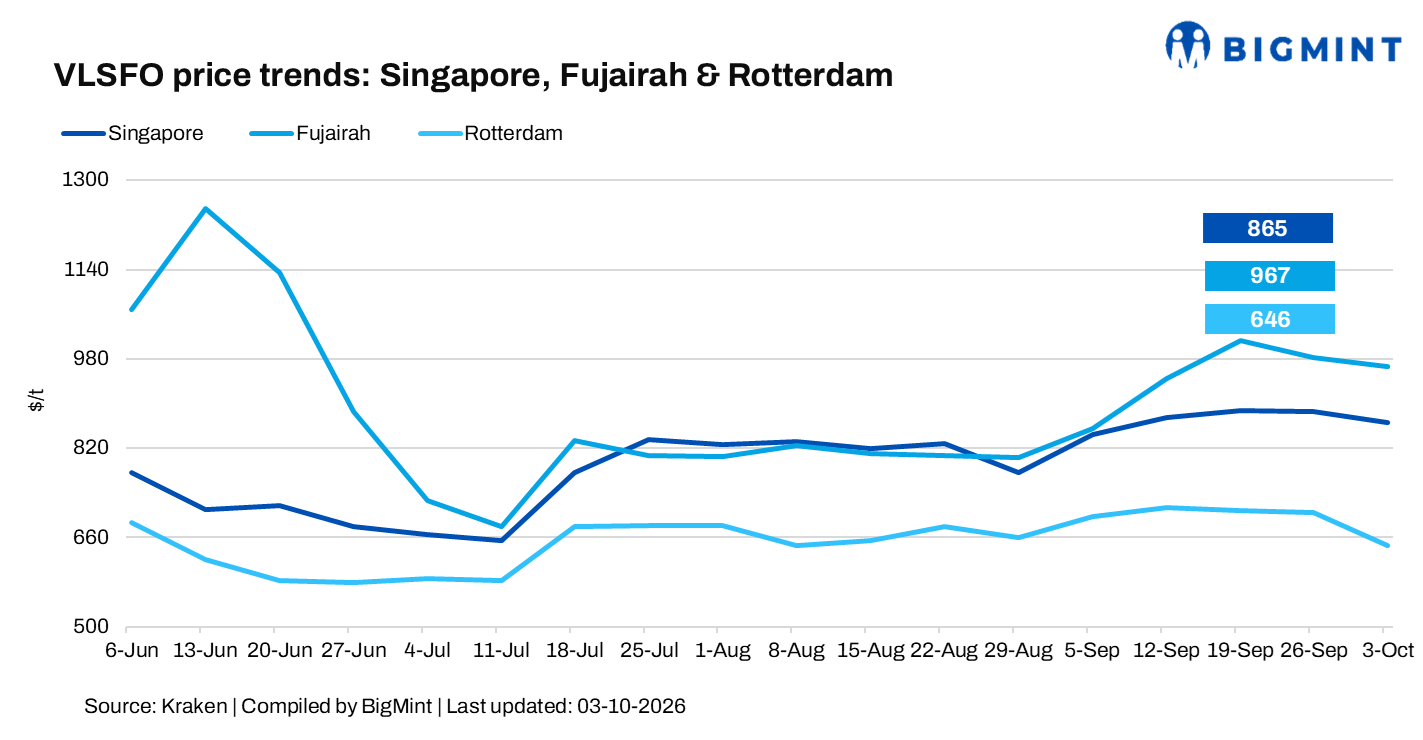
- Singapore: VLSFO declined $20/tonnes (t) (2.3%) w-o-w to $865/t, while MGO fell w-o-w. In contrast, HSFO increased $16/t (2.2%) to $753/t, indicating firmer demand or tighter availability for high-sulphur fuel despite softer low-sulphur and middle-distillate prices.
- Rotterdam: VLSFO dropped sharply by $59/t (8.4%) to $646/t, while MGO declined w-o-w, recording the largest absolute and percentage fall among the three hubs. HSFO also decreased, reflecting broadly softer fuel-market sentiment in the region.
- Fujairah: VLSFO fell $16/t (1.6%) to $967/t, while MGO declined sharply w-o-w. Despite the weekly decline, Fujairah continued to command a significant premium, particularly in MGO, reflecting the continued sensitivity of the Middle East bunkering market to regional supply and shipping risks.
Market factors
- Crude prices ease, but volatility remains: December Brent futures declined 4.2% w-o-w to $100.54/barrel (bbl), from $104.94/bbl, suggesting some easing in crude-price pressure. However, oil markets remain highly sensitive to developments around the Middle East and the Strait of Hormuz. Recent reporting indicates that crude flows through the Strait have recovered substantially, but refined-product flows remain more constrained, particularly for diesel.
- WTI crude futures decline further: WTI crude futures fell to $91.11/bbl on 3 October, from $92.82/bbl on 26 September, declining $1.71/bbl (1.8%) w-o-w. The decline reflects easing concerns over near-term supply disruptions and softer crude-market sentiment, although persistent Middle East tensions and uncertainty surrounding the Strait of Hormuz continue to pose upside risks to prices.
Outlook
Global bunker prices are likely to remain volatile despite the recent w-o-w decline, with crude-price movements, Strait of Hormuz security and refined-product availability remaining key drivers. MGO could remain particularly sensitive to supply disruptions, while VLSFO may continue to track changes in crude and regional replacement costs. Any sustained recovery in Middle East oil flows could ease bunker premiums, but renewed shipping disruptions or tighter Asian refined-fuel supplies could quickly reverse the recent decline.
Leave a Reply