- Brazilian domestic scrap prices remain unchanged
- Winter supply concerns, strong US mill demand support prices
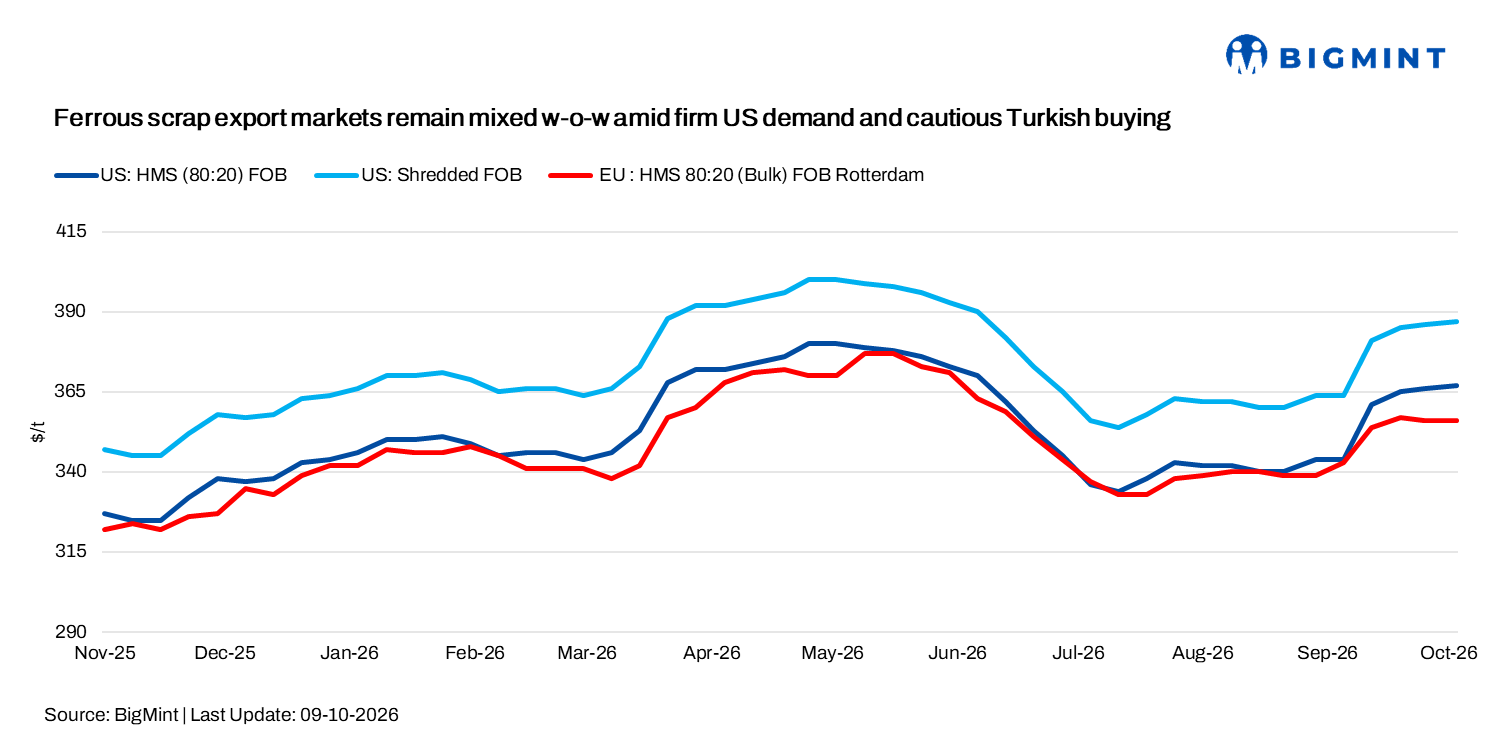
Ferrous scrap export markets remained mixed during the week ended 9 October, with tight US supply and firm domestic mill demand supporting prices, while weaker Turkish buying limited gains in Europe. In Brazil, domestic prices remained stable despite improved market sentiment following the presidential election’s first round, while export prices held firm after recent increases. Meanwhile, higher slab offers in Europe reflected firmer semi-finished steel prices, although cautious buying continued to constrain market activity.
US
US ferrous scrap prices strengthened for select grades on 9 October, supported by tight supply and stronger demand from domestic steelmakers. Midwest mills offered higher prices for October deliveries to secure feedstock ahead of winter, while export demand, particularly from Turkiye, further tightened obsolete scrap availability.
US shredded scrap export prices rose by $1/t w-o-w to $387/t FOB East Coast, while HMS 80:20 increased by $1/t to $367/t FOB. In the domestic market, shredded scrap prices climbed by $20-22/t to $475-480/t DAP in both the Midwest and Southeast. PNS scrap remained unchanged at $450-452/t DAP Midwest but increased by $20-22/t to $455-460/t in the Southeast. Busheling prices held steady at $518-520/t DAP Midwest and $500-502/t in the Southeast, although some Midwest mills bid $10-12/t higher for higher grades.
Looking ahead, HMS, plate and structural (PNS), shredded scrap and turnings prices are expected to increase by $25-30/t, while prime grades are projected to remain sideways or rise by up to $8-10/t.
Tight supply and elevated finished-steel prices supported buying, with Midwest hot-rolled coil steady at a four-year high of $1,379/t exw. Turkish higher grade HMS 80:20 import prices rose to $404/t CFR on 9 October, from $380-385/t a month earlier.

Europe
European ferrous scrap prices remained broadly stable, although Benelux HMS 80:20 prices increased by Euro 5/t ($6/t) to Euro 285-290/t ($320-326/t) DAP. Turkish buying activity remained subdued, with only two Netherlands- and UK-origin scrap deals reported at $390-391/t CFR to a Mediterranean-based mill. Dockside HMS 80:20 prices were assessed at Euro 285-295/t ($320-331/t), largely unchanged w-o-w, while BigMint’s Rotterdam bulk HMS 80:20 assessment held steady at $356/t FOB.
In Italy, export prices stood at Euro 330-340/t ($66-68/t) FOB for shredded scrap (E8), Euro 280-305/t ($56-61/t) FOB for HMS 80:20 (E3) and Euro 315-320/t ($63-64/t) FOB for HMS 90:10 (E2).
In the semi-finished steel market, Chinese and Vietnamese slab offers into Italy rose to $590-600/t CFR, from around $575-580/t previously. Turkish slab offers were reported at $630/t CFR.
Brazil
Brazil’s ferrous scrap market remained stable, although market sentiment improved following the first round of presidential elections on 4 October. Some participants reported more positive expectations after the vote, but this did not translate into immediate price changes.
Domestic scrap prices were largely unchanged. Two sellers reported stable prices for industrial clean steel scrap, while two recyclers noted that a steel mill was revising its prices without providing further details.
HMS 80:20 was assessed at BRL 800-850/t ($159-169/t) FOT, clean steel scrap at BRL 900-950/t ($179-189/t) FOT and turnings scrap at BRL 700-750 ($139-149/t)/t FOT. Export prices also held steady at $305-310/t FOB for HMS 80:20 and $330-335/t FOB for shredded scrap. Both grades had increased by $5-7/t, supported by improved operating conditions for some exporters and lower freight rates.
Leave a Reply