- Safety curbs, weak steel demand suppress coal and coke output
- Gradual mine restarts and tight supply may limit price downside
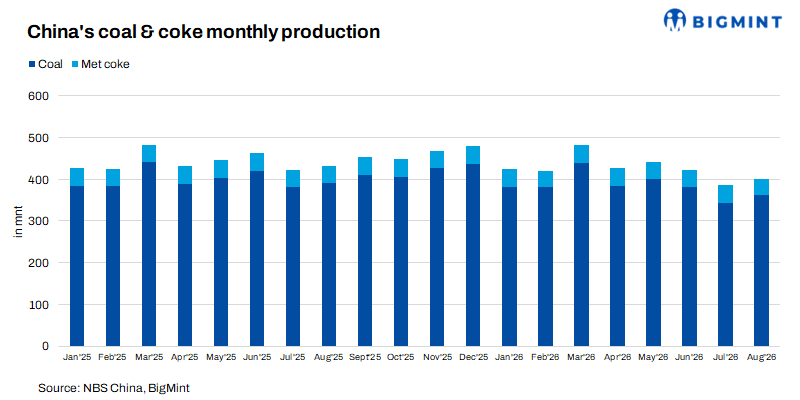
China’s coal production declined 7.7% y-o-y to 361.82 mnt in August 2026, extending the year-on-year contraction amid intensified mine-safety inspections following fatal mining accidents. However, output increased 5.4% m-o-m from 343.21 mnt in July, indicating a gradual recovery in production activity.
Cumulative output during Jan-Aug 2026 stood at 3.06 billion tonnes, down 3.3% y-o-y.
Safety curbs continue to restrain coal supply
The sharp y-o-y decline was primarily driven by stricter safety inspections, temporary mine suspensions and tighter regulatory controls following recent mining accidents. Enhanced scrutiny has constrained operating rates and delayed the full restoration of some mining capacity.
Despite the annual decline, the August m-o-m increase suggests that some production capacity gradually resumed, supporting a partial recovery in domestic supply.
Coke output slips amid weak steel sector demand
China’s coke production declined 6% y-o-y and 3.5% m-o-m to 39.92 mnt in August. However, cumulative production during Jan-Aug reached 334.1 mnt, marginally up 0.3% y-o-y.
The monthly decline reflects weaker steelmaking activity, subdued mill margins and production restrictions, which reduced coke consumption. Meanwhile, the near-flat cumulative growth indicates that the broader coke market has remained relatively stable despite recent monthly weakness.
Key factors behind production decline
- Stringent mine-safety inspections following fatal mining accidents.
- Temporary production suspensions and slower mine restarts.
- Regulatory focus on eliminating unsafe mining capacity, limiting near-term supply growth.
- Weak steel margins and production curbs, weighing on coke demand.
- Seasonal and regional operating constraints, contributing to fluctuations in monthly output.
Outlook
China’s coal production is expected to recover gradually but remain below year-ago levels in the near term, as safety inspections continue to constrain mining operations. Any easing of restrictions and resumption of suspended capacity could improve domestic availability, although regulators are likely to prioritise safety over aggressive production growth.
For coke, weak steel demand and subdued mill profitability may keep production under pressure, limiting upside in the near term. However, continued supply discipline in coal could keep coking-coal and coke markets relatively supported, particularly if steel demand improves.
Leave a Reply