- Iron ore prices rise on pre-holiday mill restocking
- Production cut concerns weigh on market sentiment
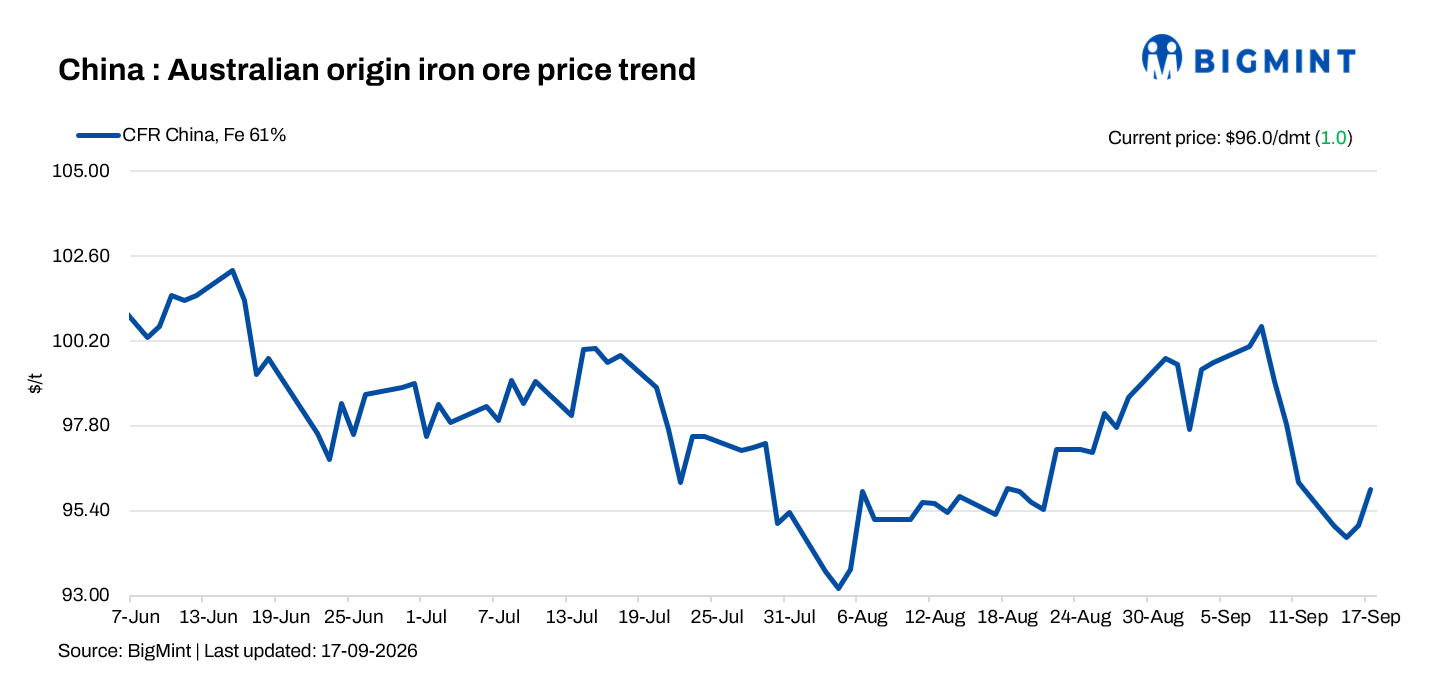
Iron ore fines (Fe 61%) spot prices increased by $1/dmt d-o-d to $96/dmt CFR China on 17 September 2026, supported by the start of pre-holiday restocking by Chinese steelmakers. However, the increase remained limited as weak steel demand and a hawkish stance from the US Federal Reserve continued to weigh on market sentiment. Short-term procurement ahead of the upcoming holidays provided some support to prices, with Chinese integrated steelmakers increasing purchases of imported sintering fines mainly to meet production requirements during the holiday period.
The increase in procurement, however, did not indicate a significant improvement in underlying iron ore demand. Mills’ immediate consumption requirements increased only marginally, suggesting that most of the additional buying was aimed at replenishing inventories ahead of the National Day holidays (1-7 October). At the same time, weak steel-market conditions continued to restrict price gains, with the traditional peak season yet to show a meaningful recovery in demand.
Overall spot trading activity eased slightly compared with the prior day, as an improvement in seaborne transactions was only partly able to offset lower portside trading volumes. Nevertheless, buying volumes remained generally sufficient. Market sentiment stayed subdued amid expectations of steel production cuts and continued pressure on finished steel prices. China’s portside iron ore prices increased for a second consecutive day, while lump premiums weakened amid elevated coking coal costs. As per reports, currently sellers holding lower-cost port inventories were more willing to sell, whereas those carrying higher-cost cargoes from earlier purchases faced greater difficulty in finding buyers.
DCE iron ore futures remain under pressure
January 2027 iron ore futures on the Dalian Commodity Exchange (DCE) rose by RMB 1/tonne (t) ($0.2/t) to RMB 713/t ($106.3/t) on 17 September, from RMB 712/t ($106.2/t) on 16 September. The marginal gain had limited impact on the broader market outlook, which remained cautious amid subdued steel demand, production-cut expectations and uncertainty over inventory replenishment beyond the holiday restocking cycle.
Leave a Reply