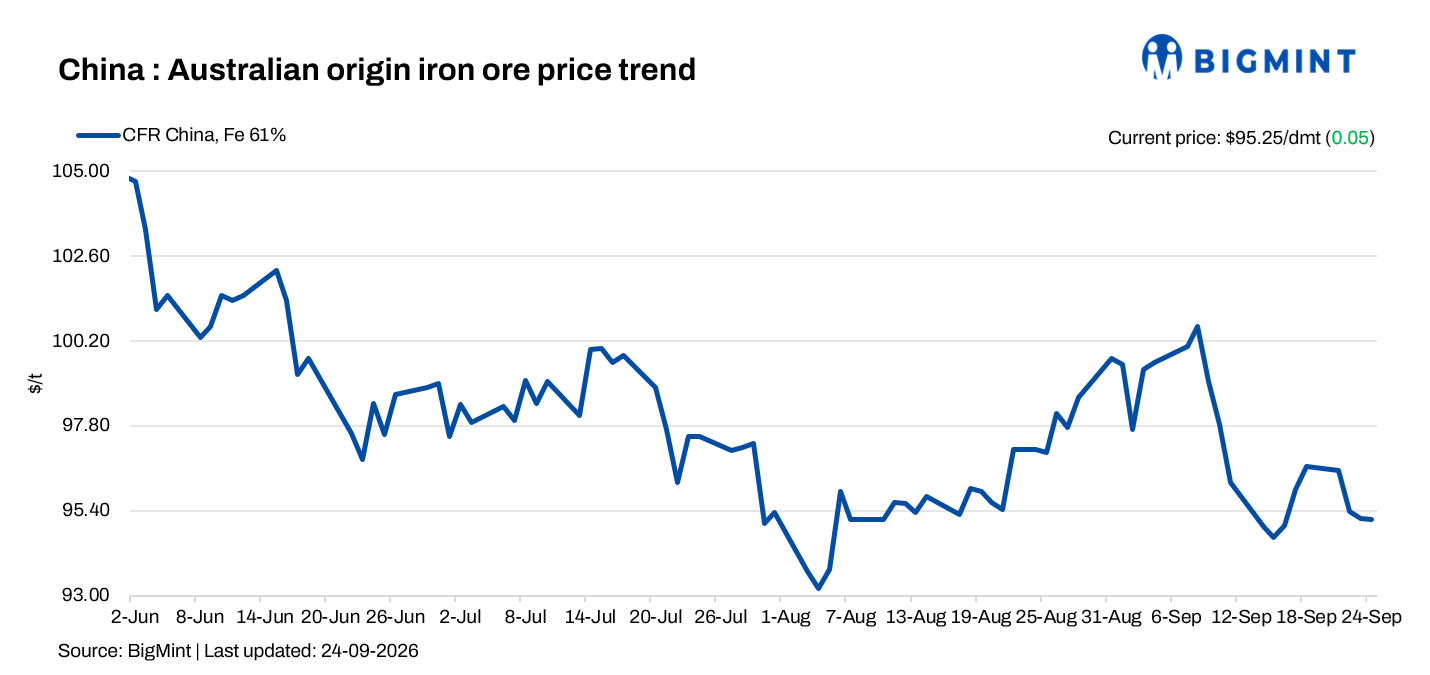
- Market remains muted ahead of Mid-Autumn Festival holidays
- Rising Brazilian freights, elevated coke costs keep buyers cautious
Iron ore fines (Fe 61%) spot prices remained steady d-o-d at $95/dmt CFR China on 24 September 2026, as the market remained subdued ahead of the Mid-Autumn Festival holidays.
Trading activity remained limited as market participants began preparing for the 25-27 September holiday period. Spot buying slowed, with Chinese mills having largely finished their pre-holiday replenishment. Some market participants remained watchful about Brazilian cargoes amid rising freight concerns, as higher shipping costs could affect the competitiveness of Brazilian material.
However, other sources noted that elevated coke prices may limit any potential support to iron ore demand. Meanwhile, relatively steady steel output and recent inventory building continued to offer some underlying support to the market.
Imported iron ore sintering fines stocks at 64 Chinese blast-furnace mills rose for the fourth consecutive week as of 23 September, climbing 6.1% w-o-w to 15.3 million tonnes (mnt), the highest in seven months, Mysteel data showed.
Meanwhile, average daily crude steel output at China Iron and Steel Association (CISA) member mills was 1.922 mnt in mid-September, only 0.1% lower than in early September. The limited decline in steel production suggests that mills’ iron ore consumption remains relatively stable. However, weak spot activity and high raw material costs continue to pressure steelmaking margins, keeping mills cautious about additional purchases.
DCE iron ore futures remain weak
January 2027 iron ore futures on the Dalian Commodity Exchange (DCE) remained stable d-o-d at RMB 713.5/t ($106.9/t) on 24 September. The subdued futures market reflected cautious sentiment, with spot demand remaining soft ahead of the holidays. As most steelmakers had already completed their pre-holiday inventory requirements, buyers remained selective and showed limited urgency to make fresh purchases.
Leave a Reply