- Transpacific rates gain on capacity management, resilient US imports
- European freights face pressure from softer demand, recovering Suez capacity
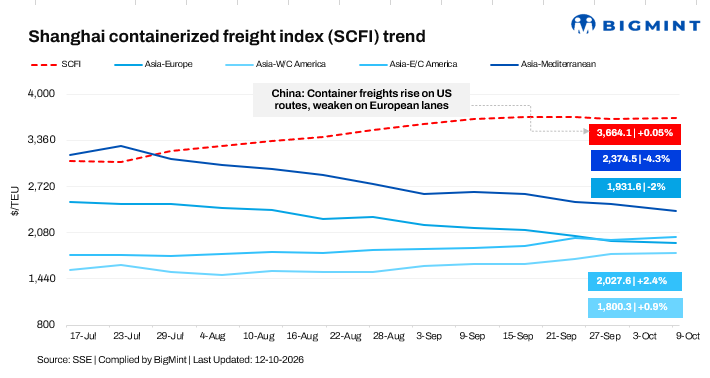
The Shanghai Containerized Freight Index (SCFI) edged up 0.05% to $3,664.11/twenty-foot equivalent unit (TEU) on 9 October 2026, from $3,662.3/TEU on 30 September, indicating largely stable container freight sentiment despite mixed trends across major trade routes.
Asia-Europe freights declined w-o-w, as post-Golden Week cargo demand softened and increasing Suez Canal transits added effective capacity to the market. Asia-Mediterranean rates recorded a sharper decline, reflecting recovering vessel capacity and sustained downward pressure on spot prices. Industry reports also indicate that the return of services via the Suez Canal and additional vessel capacity are weighing on Europe-bound freight rates.

In contrast, transpacific rates edged higher, with Asia-West Coast America rising and Asia-East Coast America increasing. Firm pricing was supported by carrier capacity management and resilient US import activity. The Port of Los Angeles handled a record 1.04 million TEUs in September, supported by holiday shipments and inventory replenishment, indicating sustained cargo flows despite the Golden Week slowdown. However, emerging signs of spot-rate softening suggest that upward momentum may be moderating.
Outlook
Container freight markets are likely to remain divided in the near term, with transpacific rates receiving support from carrier capacity management and US import demand, while Europe-bound trades face continued pressure from the restoration of Suez Canal services and softer post-holiday bookings. Congestion at Asian ports, blank sailings and further changes in carrier routing will remain key factors influencing rate movements.
Leave a Reply