- Rebar prices rise across routes on low inventories
- Distributor restocking keeps HRC, CRC prices firm
- Coking coal, coke rally reinforces steel price strength
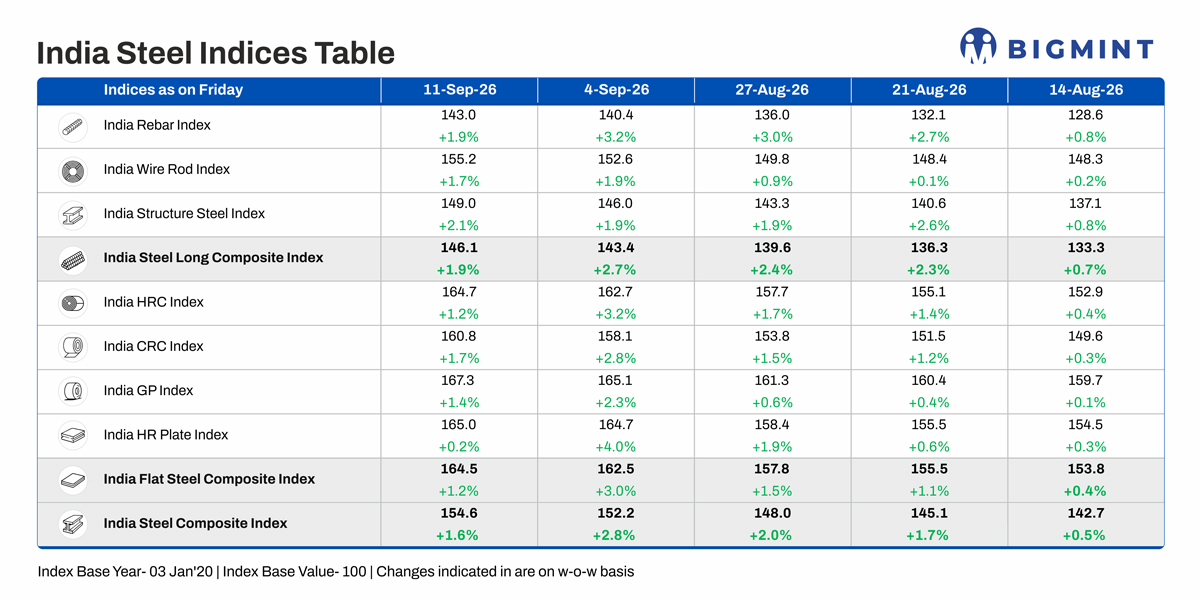
Morning Brief: BigMint’s India steel composite index increased by 1.6% w-o-w on 11 September 2026, rising for the eighth consecutive week to a two-and-a-half-year high. These price levels were last witnessed in April 2023. The uptick reflects firm sentiments across both long and flat steel segments on improving post-monsoon demand, high raw material costs, low trader- and mill-level inventories, and sustained mill pricing discipline.
While the pace of the increase moderated from the previous week’s 2.8%, domestic steel prices continued to move higher as buyers replenished inventories ahead of the festive season and expectations of further price increases encouraged advance procurement. Tight material availability in both rebar and flat steel markets, coupled with firm raw material costs, continued to support sentiment.

The longs composite index rose by 1.9% w-o-w, while the flats index increased by 1.2% w-o-w.
Highlights of price movements
BF-rebar market momentum continues: Trade-level BF-route rebar prices increased by INR 1,700/t ($18/t) w-o-w to INR 59,000/t ($617/t) ex-Mumbai on 11 September.
The market benefited from a gradual recovery in construction activity as the monsoon season neared its end across several regions. Project demand improved noticeably, with buyers increasingly securing material for ongoing and upcoming infrastructure projects.
Low inventories across the distribution channel continued to strengthen sellers bargaining power. Market participants reported improved booking activity from project customers, while distributors also increased procurement to replenish stocks ahead of the festive season.

Several mills remained cautious about accepting large forward bookings amid expectations of further price appreciation. Tight project market availability and lean inventories supported prices throughout last week.
Distributor buying also showed signs of improvement as market participants prepare for post-monsoon demand recovery and the upcoming festive season.
IF steel prices edge up: IF-route rebar prices increased by INR 100-1,900/t w-o-w across markets. Demand improved during the first half of the week as rising sponge iron, iron ore and coal prices pushed up finished steel costs, while expectations of further raw material price increases prompted buyers to procure proactively.
However, buying moderated in the latter half of the week amid buyer resistance to higher prices. Mill inventories declined to around six-seven days, while order booking visibility remained limited at three-five days.
HRC, CRC prices continue uptrend: The flat steel segment continued to record gains, although at a slower pace than long products.
BigMint’s bi-weekly assessment for HRC (IS2062, Grade E250, 2.5-8 mm/CTL) stood at INR 62,700/t ($656/t) ex-Mumbai as of 11 September, up INR 700/t w-o-w. The benchmark assessment for cold-rolled coil (CRC) prices (IS513, Grade O, 0.9 mm/CTL) increased to INR 72,200/t ($757/t) ex-Mumbai compared with INR 70,500/t ($741/t) in the previous week. All prices exclude 18% GST.
Domestic HRC prices remained stable following sharp gains in recent weeks. However, mills September list price hikes, firm raw material costs and relatively tight spot availability continued to support market sentiment.
Material availability in the trader channel remained constrained as mills prioritised supplies to automotive and large B2B customers. Distributors continued to operate with lean inventories, limiting spot availability and reducing the scope for aggressive discounts. Demand was requirement-based, although confidence improved as expectations of further mill price increases encouraged selective restocking.

A combination of controlled dispatches, improving sentiment and tight inventories helped maintain the price momentum.
HRC export offers to EU rise w-o-w: Indian HRC export offers to the EU rose by $35/t w-o-w to around $640/t FOB, with BigMint’s India HRC export index to the EU reaching a four-month high, supported by stronger domestic realisations and limited availability from mills. However, offers to the Middle East and Vietnam remained on hold as mills prioritised domestic sales amid stronger realisations what with domestic HRC touching a four-year high.
Coking coal surge keeps steel prices strong: BigMint’s premium hard coking coal (PHCC) index was assessed at $306/t CNF India on 11 September, up $7/t w-o-w. The index continued its rally for yet another week amidst global cues. The domestic coke market also continued its uptrend driven by tight availability and higher coking coal costs. BF-grade coke prices ticked up by INR 1,500-3,000/t across markets.
High-grade iron ore prices also increased, with NMDC increasing DR-grade iron ore lumps prices by INR 250/t. Domestic scrap, too, staged a late-week rebound after remaining somewhat subdued due to surging long steel prices.
Outlook
Buyers are increasingly returning to the market as weather disruptions ease in several regions. Distributors are also preparing for stronger seasonal consumption during the festive period, leading to higher inventory replenishment. Although end-user demand remains below peak levels, market sentiment has improved considerably compared with July and early August.
In the long steel segment, improving construction activity, stronger project bookings and lean inventories are expected to support prices. In the flats segment, controlled mill dispatches, firm list prices and tight trader-channel availability are likely to keep prices stable to firm. Demand from automotive, engineering and infrastructure sectors is expected to remain supportive.
At the same time, elevated coking coal costs continue to provide a strong cost-side floor for steel prices.
Leave a Reply